
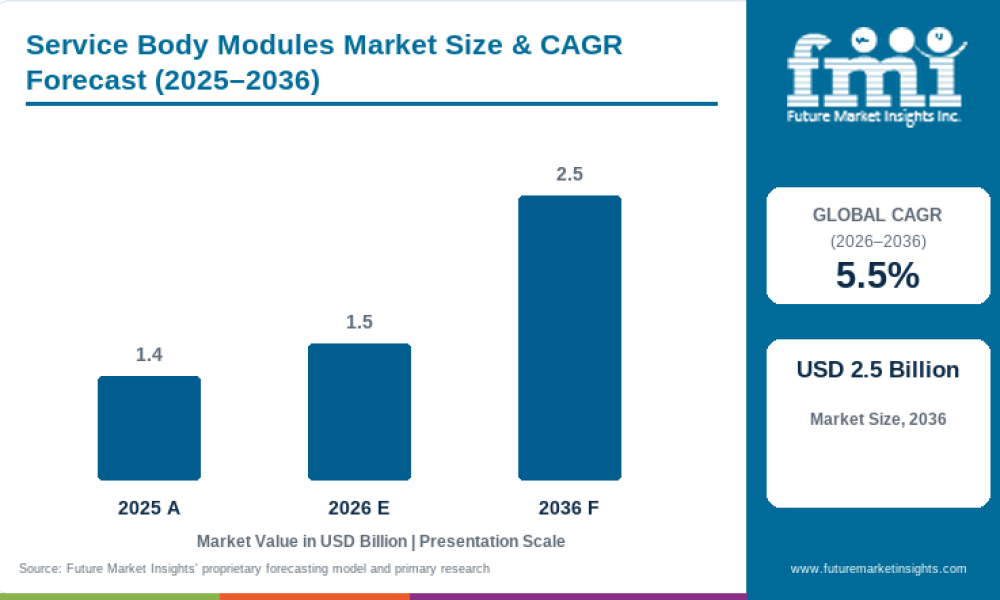
The global service body modules market is projected to grow from USD 1.5 billion in 2026 to USD 2.5 billion by 2036, registering a 5.5% CAGR over the forecast period. Demand is being supported by utility expansion, infrastructure maintenance, and telecommunications deployment, as commercial fleets require vehicles that can transport tools, compressors, cranes, and storage systems directly to distributed worksites.
Service body modules convert a bare commercial vehicle chassis into a dedicated mobile work platform. By integrating storage compartments, equipment mounts, and job-specific accessories, these modules help crews carry the equipment needed for maintenance, installation, and repair activities. As field operations move beyond fixed depots, service bodies increasingly function as mobile equipment bays that organize tools and support repeatable work procedures.
Infrastructure investment is reinforcing this demand. The U.S. Department of Energy’s approximately USD 1.9 billion SPARK funding initiative for transmission upgrades illustrates the scale of investment that can generate downstream requirements for utility maintenance vehicles and specialized fleet equipment. Converting infrastructure budgets into vehicle orders depends on fleet specifications, procurement cycles, and the operational needs of field crews.
What Are the Key Segments in the Service Body Modules Market?
The service body modules market is segmented by module type, vehicle type, material, sales channel, end use, and region. Demand varies according to crew requirements, chassis capacity, equipment configuration, and the need to balance storage with payload limits.
- Tool Compartment Modules – 29.0%: Tool compartment modules account for the leading share of module-type demand in 2026. They provide organized storage for tools and frequently used equipment, supporting field technicians who need direct access to supplies at the worksite.
- Pickup Service Bodies – 28.0%: Pickup service bodies lead the vehicle-type segment in 2026, reflecting demand from crews that need external storage and work-ready configurations without moving to a heavier vocational chassis.
- Steel – 42.0%: Steel represents the leading material category in 2026. Familiar fabrication and repair practices support its use across vocational applications where payload constraints do not outweigh other cost and durability considerations.
- Truck Upfitters – 36.0%: Truck upfitters account for the leading sales-channel share in 2026 because service bodies must be matched to chassis specifications, equipment layouts, and intended work functions.
- Utility Service – 27.0%: Utility service represents the leading end-use segment, supported by recurring requirements for maintenance, network installation, and field repairs.
Get detailed market forecasts, competitive benchmarking, and pricing trends:
https://www.futuremarketinsights.com/reports/sample/rep-gb-35476
Other module types include electrical service modules, compressor and generator modules, drawer and shelf modules, and crane-ready body modules. Vehicle categories also include light-duty trucks, medium-duty trucks, utility vans, and fleet maintenance trucks.
Material options extend to aluminum, stainless steel, and composite panels. Sales channels include body builders, fleet procurement teams, and aftermarket distributors, while end-use applications span construction service, telecommunications, municipal fleets, and mobile repair.
Which Countries Are Growing Fastest in the Service Body Modules Market?
Mexico is projected to record the fastest growth among the profiled countries, with a 6.2% CAGR from 2026 to 2036. Expanding infrastructure activity and commercial vehicle requirements create opportunities for service body manufacturers serving utility, construction, and field maintenance fleets. Suppliers that coordinate body configurations with chassis availability and upfitter requirements can support more repeatable fleet specifications.
Australia is expected to grow at a 5.7% CAGR. Utility network maintenance, geographically dispersed worksites, and the need to transport tools and equipment across long distances support demand for practical, job-specific service vehicles. Payload management and durable body construction remain important considerations for fleet operators.
Brazil is projected to expand at a 5.6% CAGR, supported by infrastructure development and requirements for commercial vehicles used in maintenance, construction, and field service. Suppliers that offer repairable configurations and adaptable storage systems can address a range of operating conditions and fleet needs.
Canada is forecast to grow at a 5.4% CAGR. Utility maintenance and infrastructure service requirements support demand for vehicles that can carry equipment to distributed worksites. Fleet operators must also consider chassis suitability, payload capacity, and the durability of body systems used in demanding operating environments.
The United States is projected to record a 5.0% CAGR through 2036. A mature truck upfitting ecosystem and recurring fleet replacement cycles support demand for service bodies across utility, municipal, telecommunications, and mobile repair applications. Compliance with final-stage vehicle requirements remains important when integrating specialized bodies and equipment.
Germany is expected to grow at a 4.4% CAGR, with demand influenced by commercial vehicle specifications, industrial service requirements, and emissions-related considerations affecting material and powertrain choices.
Japan is projected to record a 3.8% CAGR. Demand is linked to fleet maintenance and service operations, with vehicle packaging, efficient equipment storage, and manufacturing consistency remaining relevant to supplier selection.
What Is Driving Demand for Service Body Modules?
Utility and Infrastructure Investment Supports Fleet Requirements
Electricity transmission, telecommunications, and public infrastructure networks require ongoing installation, inspection, and maintenance. These activities create demand for service vehicles that can carry tools, replacement parts, lifting equipment, and auxiliary systems to field locations.
Service body modules help fleet operators configure vehicles around the tasks crews perform. Utility technicians may need electrical storage and specialized equipment mounts, while construction and maintenance teams may prioritize tool compartments, compressors, generators, or lifting capabilities. Infrastructure spending can therefore influence demand for specific body configurations as projects move from planning to field execution.
Mobile Workflows Increase the Value of Integrated Storage
Field crews often operate away from central depots, making onboard storage and equipment organization important to daily productivity. Tool compartment modules can help keep frequently used equipment accessible and separate tools from other supplies.
A well-configured service body can also reduce the need for separate equipment transport. However, the benefits depend on the job scope, the crew’s workflow, and the amount of payload available after accounting for the body, tools, and auxiliary equipment.
Truck Upfitters Connect Body Design with Chassis Requirements
Truck upfitters account for 36.0% of sales-channel demand in 2026. Their role extends beyond installing a body: they must match the module configuration to the vehicle chassis, intended load, equipment mounts, and operating requirements.
Pre-engineered configurations can help simplify repeat orders across fleets. By validating common layouts against specific chassis platforms, suppliers and upfitters can reduce repeated engineering work and make vehicle replacement programs easier to standardize.
Material Selection Balances Durability and Payload
Steel accounts for 42.0% of material demand in 2026, supported by familiar manufacturing and repair processes. Yet body weight directly affects the payload remaining for tools, personnel, and equipment.
Aluminum and composite options can help reduce body mass in applications where payload is a key constraint. The appropriate choice depends on durability requirements, purchase cost, repair practices, fabrication capabilities, and the intended duty cycle.
Drive Your Business Growth Strategy: Checkout the Report for Key Insights!
https://www.futuremarketinsights.com/checkout/35476
What Are the Key Challenges in the Service Body Modules Market?
Payload capacity and final-stage integration remain central constraints. Every compartment, crane mount, compressor bracket, and auxiliary system adds weight, reducing the payload available for tools and other equipment. A configuration that provides extensive storage or lifting capability may therefore exceed the vehicle’s practical carrying limits unless the body and equipment are carefully specified.
Regulatory requirements add another layer of complexity. In the United States, final-stage manufacturers and vehicle modifiers must consider applicable requirements under 49 CFR Parts 567 and 568. Body installation, weight distribution, equipment mounting, and vehicle certification obligations need to be addressed as part of the upfit process.
Customization can also increase engineering time and complicate repeat procurement. Variations in chassis dimensions, crew requirements, and equipment layouts may require changes to mounting arrangements or body design. Standardized modules and validated configurations can help reduce these challenges, although they must still match the specific vehicle and operating application.
What Opportunities Exist for Service Body Modules Manufacturers?
Manufacturers can expand their value by offering lightweight, pre-engineered modules designed around common chassis platforms and recurring crew workflows. Validated configurations can help fleet managers select equipment layouts while reducing repeated design work and integration delays.
There are also opportunities to develop modular systems that can accommodate changing job requirements. Interchangeable storage layouts, configurable equipment mounts, and well-planned access points can help operators adapt vehicles for multiple work packages while maintaining practical payload limits.
Regional manufacturing and upfitter partnerships represent another opportunity. Suppliers that coordinate with body builders, fleet procurement teams, and service networks can improve product availability and provide support throughout the vehicle’s operating life. This is particularly relevant where fleets require repeatable configurations across multiple locations.
What Is the Outlook for the Service Body Modules Market?
The service body modules market is projected to increase from USD 1.5 billion in 2026 to USD 2.5 billion by 2036, expanding at a 5.5% CAGR. Demand is expected to remain connected to utility network investment, infrastructure maintenance, telecommunications deployment, and the need to equip field crews with mobile work platforms.
As fleet operators evaluate service body configurations, purchasing decisions will increasingly depend on the balance between equipment capacity, payload, compliance, durability, and ease of maintenance. Suppliers that provide validated body-and-chassis combinations, efficient storage layouts, and repeatable integration processes can strengthen their position in OEM upfitting and fleet replacement programs.
According to Nikhil Kaitwade, Principal Consultant at Future Market Insights, “The commercial bottleneck sits at the body-chassis interface. A fleet may want more storage or lifting capacity, yet the configuration still has to stay inside the payload envelope and reach service without repeated engineering changes. Suppliers that validate common crew packages around specific chassis can shorten the specification cycle and make replacement orders easier to repeat.”
About Future Market Insights
Future Market Insights (FMI) provides market research, consulting, and industry analysis across automotive, industrial, energy, and other sectors. Its research combines market data, industry analysis, and forecasting to help businesses assess market developments, competitive positioning, and growth opportunities.



