
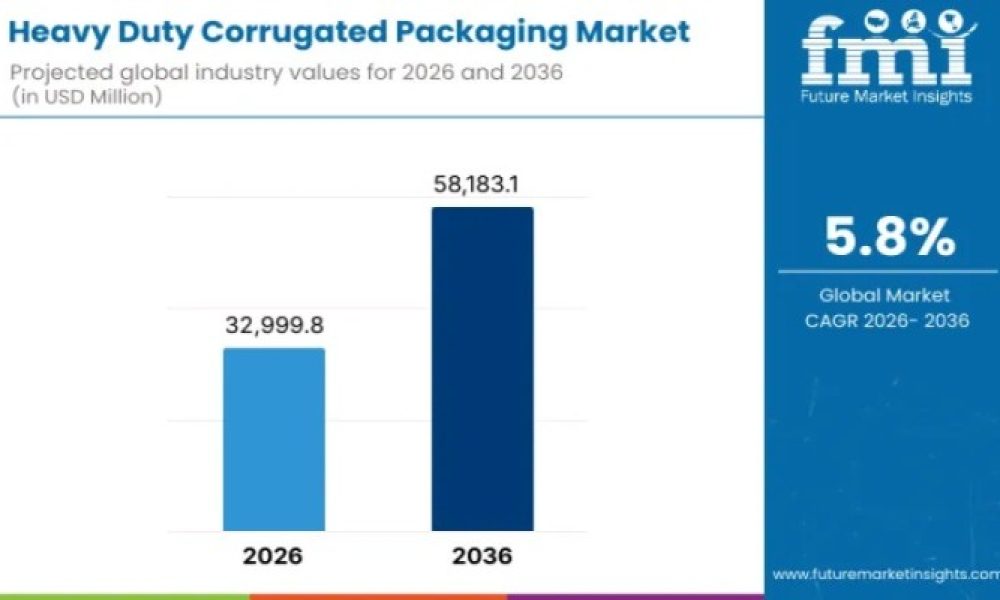
The global heavy duty corrugated packaging market is entering a decade of steady, performance-driven growth as industries worldwide prioritize durability, cost efficiency, and sustainability in logistics and transportation. Valued at USD 32,999.8 million in 2026, the market is projected to reach USD 58,183.1 million by 2036, expanding at a CAGR of 5.8% over the forecast period. This growth reflects the rising demand for packaging solutions capable of protecting high-value, heavy, and industrial goods across increasingly complex supply chains.
Heavy duty corrugated packaging has become a cornerstone for sectors such as logistics, automotive, food & beverage, industrial machinery, and consumer goods, where product integrity during storage and long-distance transportation is critical. Its high load-bearing capacity, resistance to compression, and cost-effectiveness make it a preferred alternative to wooden and plastic packaging formats.
Discover Growth Opportunities in the Market – Get Your Sample Report Now
Market Momentum Driven by E-commerce and Sustainability
One of the strongest growth drivers is the continued expansion of global e-commerce and omnichannel distribution networks. As shipment volumes rise and delivery routes become longer and more fragmented, businesses are turning to reinforced corrugated solutions that offer superior protection without significantly increasing shipping weight.
At the same time, the global shift toward eco-friendly and recyclable packaging is accelerating adoption. Heavy duty corrugated packaging aligns closely with circular economy goals, as it is widely recyclable, reusable, and increasingly manufactured using responsibly sourced paper fibers. Ongoing innovations in board design are enabling manufacturers to achieve greater strength with lighter materials, improving both sustainability and logistics efficiency.
Quick Market Snapshot (2026–2036)
- Market Value (2026): USD 32,999.8 million
- Forecast Value (2036): USD 58,183.1 million
- Forecast CAGR: 5.8%
- Leading Board Type: Triple Wall (52% share)
- Largest Application Segment: Industrial (46%)
- Key Growth Regions: North America, Europe, Asia Pacific
Triple Wall Boards Dominate Global Demand
Among board types, triple wall corrugated packaging is expected to account for 52% of global demand in 2026, making it the dominant segment. Its ability to withstand extreme compression, moisture exposure, and heavy loads makes it ideal for shipping industrial equipment, automotive components, and bulk materials. The versatility of triple wall boards has positioned them as the go-to solution for industries requiring maximum protection under challenging transport conditions.
Industrial Applications Lead Consumption
From an application perspective, the industrial segment is projected to hold 46% of total market share in 2026. Manufacturing expansion, infrastructure development, and global trade activity are driving demand for packaging that provides both structural support and impact resistance. As factories scale production and adopt stricter shipping standards, heavy duty corrugated packaging is becoming an essential part of industrial logistics strategies.
Regional Outlook: Growth Anchored Across Major Economies
North America: Innovation and Performance Focus
North America remains a key contributor, supported by advanced logistics infrastructure and high adoption of automated packaging systems. The United States, growing at a 6.0% CAGR, is leading innovation through moisture-resistant coatings, reinforced board structures, and digitally optimized packaging designs that enhance supply chain efficiency.
Europe: Precision and Sustainability
Europe continues to grow steadily, driven by strict environmental regulations and strong industrial output. Germany, with a 5.4% CAGR, plays a central role, particularly in automotive and machinery exports. European manufacturers are prioritizing compression-resistant, recyclable packaging that meets rigorous quality and sustainability standards.
Asia Pacific: Fastest-Growing Regional Market
Asia Pacific is emerging as the fastest-growing region, fueled by rapid industrialization and export growth. China leads with a 6.6% CAGR, supported by government-backed manufacturing initiatives and massive export volumes. India, expanding at 6.3% CAGR, is witnessing rising demand across automotive, machinery, and e-commerce sectors, especially in industrial hubs such as Gujarat, Tamil Nadu, and Maharashtra.
Competitive Landscape: Scale, Engineering, and Customization
The heavy duty corrugated packaging market is shaped by a mix of global leaders and strong regional players. International Paper, WestRock, and Smurfit Kappa dominate through extensive converting networks, advanced board engineering, and long-standing relationships with industrial and FMCG clients.
Challenger firms such as DS Smith, Mondi, and Packaging Corporation of America differentiate themselves through customized, high-performance solutions tailored to heavy machinery, bulk shipping, and specialized industrial needs. Regional players including Georgia-Pacific, Cascades, Sonoco, and Rengo add competitive strength through flexible manufacturing, faster lead times, and localized customer support.
Why FMI: https://www.futuremarketinsights.com/why-fmi
About Future Market Insights (FMI)
Future Market Insights, Inc. (FMI) is an ESOMAR-certified, ISO 9001:2015 market research and consulting organization, trusted by Fortune 500 clients and global enterprises. With operations in the U.S., UK, India, and Dubai, FMI provides data-backed insights and strategic intelligence across 30+ industries and 1200 markets worldwide.



