
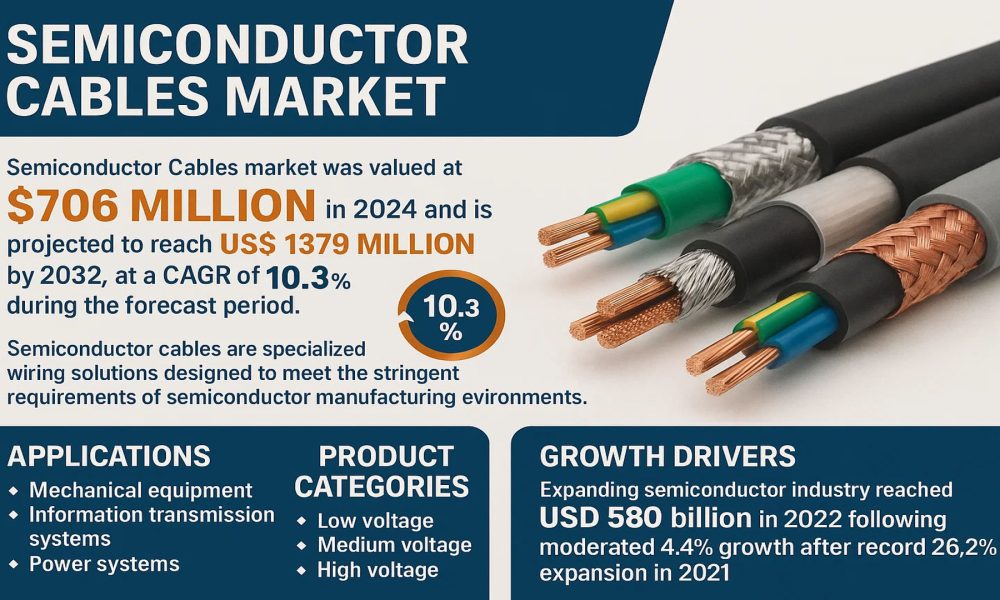
Semiconductor Cables Market was valued at 706 million in 2024 and is projected to reach US$ 1379 million by 2032, at a CAGR of 10.3% during the forecast period.
Semiconductor cables are specialized wiring solutions designed to meet the stringent requirements of semiconductor manufacturing environments. These high-performance cables must endure rapid, precise movements while preventing particle contamination that could compromise chip integrity. Key product categories include low voltage, medium voltage, and high voltage cables, which are critical for applications in mechanical equipment, information transmission systems, and power systems.
Market growth is driven by the expanding semiconductor industry, which reached USD 580 billion in 2022 despite a moderated 4.4% growth rate following record 26.2% expansion in 2021. Regional dynamics show strong performance in the Americas (17% growth) and Europe (12.6% growth), while Asia Pacific—the largest market—experienced a 2.9% decline. Leading manufacturers including Helukabel, Gore, and Staubli are innovating to meet rising demand from foundries and equipment manufacturers, particularly as advanced node production requires cables with enhanced durability and contamination control.
Receive Your Sample Report at No Cost-https://semiconductorinsight.com/download-sample-report/?product_id=107128
MARKET DYNAMICS
MARKET DRIVERS
Rising Demand for Advanced Semiconductor Manufacturing to Fuel Cable Market Growth
The semiconductor industry is experiencing unprecedented demand, driven by the rapid adoption of 5G, IoT devices, and artificial intelligence applications. This increased production output directly boosts the requirement for high-performance semiconductor cables that can endure extreme processing conditions while maintaining signal integrity. The global semiconductor market, valued at around $580 billion in 2022, continues to expand despite economic headwinds, with sectors like Analog and Logic showing particularly strong double-digit growth. Semiconductor cables play a critical role in wafer processing equipment, inspection tools, and vacuum systems where they must resist chemical corrosion, high temperatures, and particle contamination.
Expansion of Electric Vehicle Production Accelerates Specialized Cable Needs
The automotive semiconductor market is undergoing fundamental transformation as electric vehicles become mainstream, requiring more sophisticated power management systems. EVs contain semiconductor content worth 3-4 times that of conventional vehicles, with the global EV market projected to grow at a compound annual rate exceeding 25% through 2030. This creates substantial demand for medium and high voltage semiconductor cables capable of handling increased power loads while minimizing electromagnetic interference. Cable manufacturers are responding with innovations in materials science to meet automotive industry standards for durability and safety.
Technological Advancements in Cable Materials Drive Performance Improvements
Material science breakthroughs are enabling semiconductor cable manufacturers to overcome traditional limitations. New fluoropolymer compounds, ceramic coatings, and nanocomposite materials demonstrate superior resistance to extreme temperatures (up to 300°C continuous operation) while maintaining flexibility and dielectric properties. These innovations are critical as semiconductor fabrication nodes shrink below 5nm, where even minor cable outgassing can contaminate cleanroom environments. Leading manufacturers report productivity gains of 15-20% when upgrading to latest-generation cable systems, making the investment increasingly attractive despite higher upfront costs.
Recent Market Developments (in detail):
- Rising Demand in Electronics Manufacturing: The semiconductor industry’s rapid growth, driven by consumer electronics, automotive electronics, and industrial automation, has significantly increased the demand for high-performance semiconductor cables. These cables ensure reliable power transmission and signal integrity in semiconductor fabrication and assembly equipment.
- Technological Advancements: Manufacturers are introducing cables with enhanced durability, higher temperature resistance, and improved flexibility to meet the stringent requirements of semiconductor fabrication processes, such as lithography, etching, and wafer handling.
- Expansion of Semiconductor Fabrication Facilities: Companies are investing heavily in new semiconductor fabs (fabrication plants) across Asia-Pacific, North America, and Europe. This expansion is driving the adoption of advanced semiconductor cables to support equipment operations and automation systems.
- Focus on High-Speed Data Transmission: The growth of AI, IoT, and 5G applications has created a need for semiconductor cables capable of supporting high-speed data transfer with minimal signal loss, particularly in cleanroom and high-frequency environments.
- Strategic Collaborations and Partnerships: Key players in the market are forming collaborations with semiconductor equipment manufacturers to supply custom-designed cables that optimize performance and reliability in advanced production processes.
- Sustainability Initiatives: The market is seeing a shift toward eco-friendly and recyclable materials in semiconductor cable manufacturing to comply with global environmental standards and reduce carbon footprints in electronics production.
MARKET OPPORTUNITIES
Emerging Semiconductor Packaging Technologies Create New Cable Applications
Advanced packaging methods like 3D IC and chiplet architectures are driving innovation in interconnects and cabling solutions. The heterogeneous integration trend requires specialized low-profile cables capable of high-density signal transmission between stacked dies. Market analysis indicates that packaging-related cable demand will grow at nearly twice the rate of traditional front-end cabling solutions through 2030. Leading cable manufacturers are developing ultra-thin coaxial and ribbon cable variants with pitch dimensions below 100μm to meet these emerging requirements.
Geographic Expansion of Semiconductor Fabs Opens New Regional Markets
The global semiconductor industry’s geographical diversification presents substantial growth potential for cable suppliers. With over $200 billion in new fab construction planned across North America, Europe, and Southeast Asia through 2025, cable manufacturers have opportunities to establish local supply chains near major production clusters. This regional expansion is particularly significant given that semiconductor cables often require customized solutions based on facility design and local environmental conditions. Suppliers establishing early presence in emerging semiconductor hubs can secure long-term maintenance and replacement business.
Receive Your Sample Report at No Cost-https://semiconductorinsight.com/download-sample-report/?product_id=107128
List of Key Semiconductor Cables Companies Profiled
- Helukabel (Germany)
- Gore (U.S.)
- Staubli (Switzerland)
- Comet (Austria)
- Totoku (Japan)
- JEM Electronics (U.S.)
- Schmalz (Germany)
- BizLink (U.S.)
- CeramTec (Germany)
- Allectra (Germany)
- Tatsuta (Japan)
- Pfeiffer Vacuum (Germany)
- Accu-Glass Products (U.S.)
- LEONI (Germany)
- VACOM (Germany)
- Agilent (U.S.)
- Gamma Vacuum (Atlas Copco) (U.S.)
- MKS Instruments (U.S.)
- Keycom (Japan)
- MDC Precision (U.S.)
- Kurt J. Lesker (U.S.)
- LewVac (U.S.)
- Shanghai Electric (China)
- Luoyang Zhengqi Machinery Co (China)
- Hefei Huaerte (China)
Segment Analysis:
By Type
Low Voltage Cables Lead Market Share Due to High Demand in Semiconductor Equipment
The market is segmented based on type into:
- Low Voltage
- Medium Voltage
- High Voltage
By Application
Mechanical Equipment and Instrumentation System Segment Dominates Owing to Critical Usage in Wafer Processing
The market is segmented based on application into:
- Mechanical Equipment and Instrumentation System
- Information Transmission System
- Power System
By Material
Copper-Based Cables Remain Prevalent for High Conductivity Requirements
The market is segmented based on material into:
- Copper
- Aluminum
- Fiber Optic
- Others
By End-User
Semiconductor Fabrication Plants Drive Majority of Demand
The market is segmented based on end-user into:
- Foundries
- IDMs (Integrated Device Manufacturers)
- OSAT (Outsourced Semiconductor Assembly and Test)
- Research Facilities
Other Topic-Motorcycle Intercom System Market
CONTACT US:
City vista, 203A, Fountain Road, Ashoka Nagar, Kharadi, Pune, Maharashtra 411014
[+91 8087992013]




