
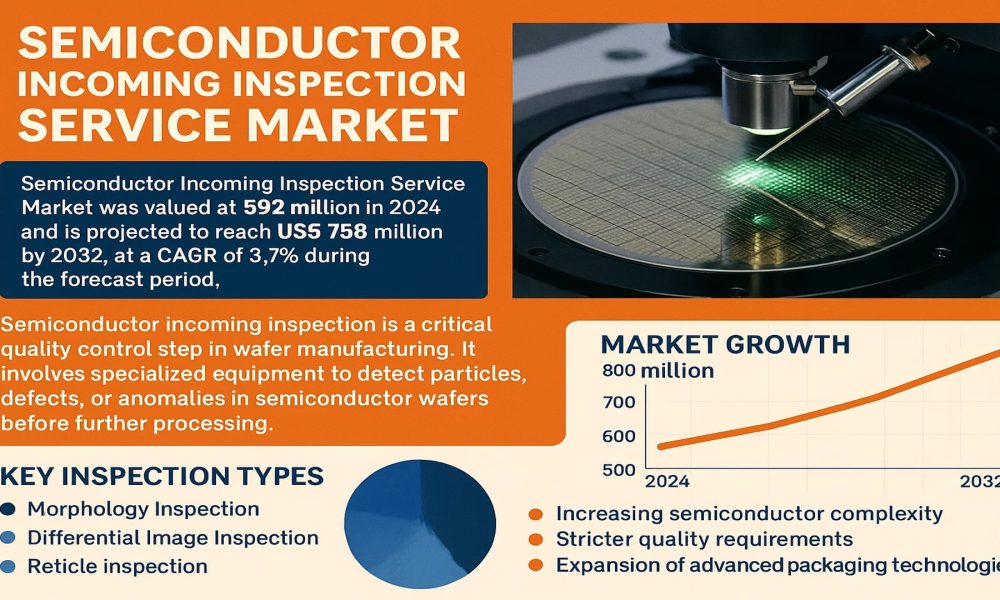
Semiconductor Incoming Inspection Service Market was valued at 592 million in 2024 and is projected to reach US$ 758 million by 2032, at a CAGR of 3.7% during the forecast period.
Semiconductor incoming inspection is a critical quality control step in wafer manufacturing. It involves specialized equipment to detect particles, defects, or anomalies in semiconductor wafers before further processing. Key inspection types include morphology inspection, differential image inspection, and reticle inspection, each serving distinct quality assurance purposes across the semiconductor supply chain.
Market growth is driven by increasing semiconductor complexity, stricter quality requirements, and the expansion of advanced packaging technologies. While the broader semiconductor market reached USD 579 billion in 2022 (projected to grow to USD 790 billion by 2029), inspection services remain a niche but essential segment. The rise of IoT applications and automotive semiconductors particularly demands precise inspection protocols, as these sectors require exceptionally high reliability standards.
Get Your Free Sample Report Today-https://semiconductorinsight.com/download-sample-report/?product_id=107121
MARKET DRIVERS
Increasing Semiconductor Manufacturing Complexity to Fuel Inspection Demand
The semiconductor industry is witnessing unprecedented complexity with nodes shrinking below 5nm, driving the need for more sophisticated inspection solutions. As feature sizes approach atomic scales, even nanometer-scale defects can render chips non-functional, making incoming inspection services critical. The global semiconductor market, valued at $579 billion in 2022, is projected to reach $790 billion by 2029, creating parallel growth opportunities for inspection services. With advanced nodes requiring up to 100x more inspection points than mature nodes, foundries and IDMs are increasingly outsourcing these specialized services to maintain yields while controlling capital expenditure.
Rising Quality Standards in Automotive Electronics to Accelerate Adoption
Automotive semiconductor demand, particularly for autonomous driving and electrification systems, requires near-zero defect rates – often below 1 defect per billion units. This stringent quality requirement is driving substantial growth in semiconductor incoming inspection services, as automotive chips undergo exhaustive qualification processes. The shift toward higher-reliability components has led to a 35% increase in inspection intensity for automotive-grade semiconductors compared to consumer electronics applications.
Furthermore, regulatory pressures continue to intensify.
➤ Automotive Safety Integrity Level (ASIL) D certification now mandates particle inspection resolutions below 10nm for critical components in advanced driver-assistance systems (ADAS).
This regulatory landscape is compelling semiconductor suppliers to invest heavily in third-party inspection services to meet automotive OEM requirements while avoiding costly recalls.
Expansion of Advanced Packaging Technologies to Create New Inspection Paradigms
The rapid adoption of 2.5D/3D packaging and chiplet architectures is generating demand for novel inspection methodologies. As die-to-die interconnects and through-silicon vias (TSVs) become more prevalent, traditional inspection techniques often prove inadequate. The market for advanced packaging is growing at 8% annually, requiring inspection service providers to develop new capabilities for detecting microcracks, bonding defects, and thermal stress points in three-dimensional structures.
Recent Market Developments: Semiconductor Incoming Inspection Service Market
The Semiconductor Incoming Inspection Service Market is witnessing significant growth due to the rising complexity of semiconductor devices and the increasing demand for high-quality components in electronics manufacturing. Key recent developments include:
- Enhanced Inspection Technologies: Companies are adopting advanced inspection techniques, including automated optical inspection (AOI), X-ray inspection, and 3D scanning, to detect micro-defects and ensure higher reliability of semiconductor components.
- Integration with Industry 4.0: Inspection services are increasingly integrating with smart manufacturing and IoT-based monitoring systems, enabling real-time quality analysis and predictive defect detection.
- Growth in Outsourcing: Semiconductor manufacturers are increasingly outsourcing incoming inspection services to specialized service providers to reduce operational costs and ensure adherence to global quality standards.
- Expansion in Asia-Pacific: The market is expanding rapidly in Asia-Pacific, driven by the growth of electronics manufacturing hubs in China, Taiwan, South Korea, and India. This region has become a major demand center for inspection services due to the rising production of chips and electronic devices.
- Focus on Compliance and Standards: Inspection service providers are emphasizing compliance with international quality standards such as ISO 9001 and JEDEC, ensuring that inspected components meet rigorous industry requirements.
- Adoption of AI & Machine Learning: Companies are leveraging AI and machine learning algorithms to improve defect detection accuracy, reduce inspection time, and enhance overall efficiency.
- Strategic Partnerships and Collaborations: Leading service providers are forming partnerships with semiconductor manufacturers to offer customized inspection solutions for complex devices like MEMS sensors, power semiconductors, and advanced ICs.
MARKET OPPORTUNITIES
AI-Powered Defect Recognition to Transform Inspection Economics
Machine learning algorithms are showing promise in automating defect classification, potentially reducing inspection costs by 30-40%. By training models on millions of defect images, service providers can significantly reduce human analysis time while improving classification accuracy. Early adopters report 20% improvements in false positive rates, directly translating to increased production yields for their clients.
Emerging Materials Innovation to Create Specialized Inspection Niches
The adoption of novel semiconductor materials like gallium nitride (GaN) and silicon carbide (SiC) requires customized inspection approaches. These wide-bandgap materials exhibit unique defect signatures that conventional silicon inspection methodologies often miss. Service providers developing specialized capabilities for compound semiconductors can capture premium pricing in these high-growth segments.
Furthermore, the rapid scaling of photonic chips presents another frontier.
➤ Integrated photonics require inspection solutions capable of evaluating optical performance characteristics in addition to physical defects – a capability few current providers possess.
This creates opportunities for service differentiation through technology partnerships and specialized equipment investments.
Vertical Integration with Failure Analysis to Offer Comprehensive Solutions
Service providers expanding into correlated failure analysis can create significant value for clients by linking incoming inspection results with root-cause failure diagnostics. This integrated approach helps semiconductor manufacturers accelerate yield learning curves while reducing time-to-market for new products. The ability to connect defect observations with electrical performance impacts represents a key differentiator in an increasingly competitive market.
Get Your Free Sample Report Today-https://semiconductorinsight.com/download-sample-report/?product_id=107121
Report Scope
This market research report provides a comprehensive analysis of the Global Semiconductor Incoming Inspection Service Market, covering the forecast period 2024–2032. It offers detailed insights into market dynamics, technological advancements, competitive landscape, and key trends shaping the industry.
Key focus areas of the report include:
- Market Size & Forecast: Historical data and future projections for revenue, unit shipments, and market value across major regions and segments. The Global Semiconductor Incoming Inspection Service market was valued at USD 592 million in 2024 and is projected to reach USD 758 million by 2032, growing at a CAGR of 3.7%.
- Segmentation Analysis: Detailed breakdown by type (Morphology Inspection, Differential Image Inspection, Reticle Inspection, Others), application (On-site Service, Outsourced Laboratory Services, Others), and end-user industry to identify high-growth segments.
- Regional Outlook: Insights into market performance across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. Asia-Pacific dominates with over 45% market share in 2024 due to semiconductor manufacturing concentration.
List of Key Semiconductor Incoming Inspection Service Providers
- ASE Global (Taiwan)
- SGS Group (Switzerland)
- EAG Laboratories (U.S.)
- MA-tek International (Taiwan)
- TSI Semiconductors (U.S.)
- Newport Wafer Fab (UK)
- Advanced Material Technology Services (Singapore)
Segment Analysis:
By Type
Morphology Inspection Dominates the Market Due to Rising Demand for Defect Detection in Semiconductor Wafers
The market is segmented based on type into:
- Morphology Inspection
- Subtypes: Particle detection, surface roughness analysis, and others
- Differential Image Inspection
- Reticle Inspection
- Subtypes: Photomask inspection, pellicle inspection, and others
- Others
- Subtypes: Electrical testing, chemical analysis, and others
By Application
On-site Service Segment Leads Due to Immediate Quality Control Needs in Semiconductor Manufacturing
The market is segmented based on application into:
- On-site Service
- Outsourced Laboratory Services
- Others
- Subtypes: Third-party verification, remote monitoring services, and others
By End-User
Foundries Segment Dominates Due to High Volume Semiconductor Production Requirements
The market is segmented based on end-user into:
- Integrated Device Manufacturers (IDMs)
- Foundries
- Outsourced Semiconductor Assembly and Test (OSAT) Providers
- Research Institutions
- Others
- Subtypes: Equipment manufacturers, material suppliers, and others
Other Topic-Heat-based RF Power Sensors Market
CONTACT US:
City vista, 203A, Fountain Road, Ashoka Nagar, Kharadi, Pune, Maharashtra 411014
[+91 8087992013]




