
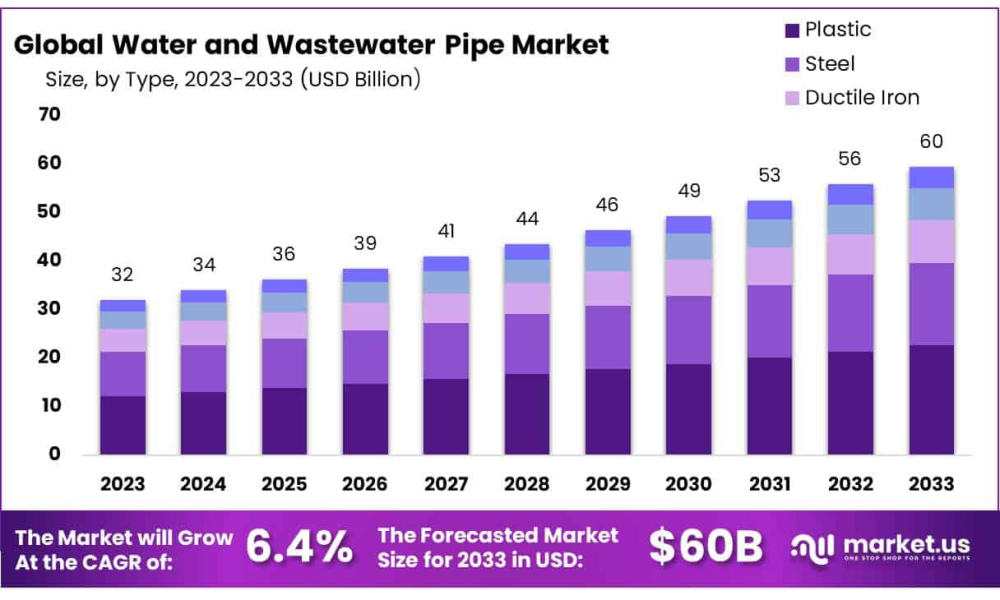
New York, NY – July 18, 2025 – The Global Water and Wastewater Pipe Market is experiencing strong growth, driven by increasing urbanization, aging infrastructure, and the need for efficient water management systems. In 2023, the market was valued at USD 32 billion and is projected to reach USD 60 billion by 2033, growing at a 6.4% CAGR.
Rising demand for clean water, stricter environmental regulations, and government investments in water infrastructure are key factors fueling this expansion. Rapid urbanization in developing countries is boosting the need for modern pipelines, while developed regions are replacing old, leaking pipes to reduce water loss. Plastic pipes (like PVC and HDPE) are gaining popularity due to their durability, cost-effectiveness, and resistance to corrosion.
Additionally, wastewater treatment projects and smart city initiatives are creating new opportunities for market players. Emerging economies in Asia-Pacific, Africa, and Latin America are expected to see the fastest growth due to increasing industrialization and government water supply programs. With climate change and water scarcity concerns rising, investments in sustainable and leak-proof piping solutions will drive further market expansion, making this a high-potential industry in the coming decade.
Important Revelation
- Market Growth Projection: The market is expected to reach USD 60 billion by 2033, with a CAGR of 6.4%.
- Pipe Material Preferences: Plastic pipes lead with 38.3% market share, favored for lightweight and corrosion resistance.
- Segment Analysis: Pipes up to 1200 mm diameter dominate with 39.4% Water and Wastewater Pipe Market share, versatile for various applications.
- Application Insights: The water supply & distribution segment holds a 67.4% share, crucial for clean water infrastructure.
- Regional Analysis: Asia Pacific leads with a 44.5% market share, driven by investments in China and India.
- In 2023, the leakage rate from water distribution systems in England and Wales was estimated to be around 20%
- In the United States, it is estimated that aging water distribution systems account for around 14% to 18% of treated water being lost through leaks and breaks
- In Canada, it is estimated that over $25 billion will be needed to replace and upgrade aging water and wastewater infrastructure in the next 10 years
➤ Download Exclusive Sample Of This Premium Report (Including Full TOC, Table & Figures): https://market.us/report/water-and-wastewater-pipe-market/request-sample/
Report Segmentation
By Material Type
In 2024, Plastic pipes led the water and wastewater pipe market, commanding over 38.3% of the market share. Their lightweight design, ease of installation, and corrosion resistance make them a top choice for potable water and wastewater systems. Variants like PVC and HDPE are prized for their flexibility and durability across diverse environmental conditions.
Steel pipes, valued for their strength and durability, hold a significant role in high-pressure and industrial applications. While their market share is smaller than plastic pipes, their ability to endure physical and chemical stresses ensures their importance in robust infrastructure projects.
Ductile Iron pipes remain a reliable choice for main water supply and critical wastewater systems due to their resilience and vibration-absorbing properties. Despite competition from newer materials, their long service life and proven performance maintain a strong market presence.
Concrete pipes are essential for large-diameter applications, particularly in stormwater drainage and large-scale wastewater management. Their strength, durability, and cost-effectiveness make them a staple in major infrastructure projects, where high water volumes and environmental resistance are critical.
Clay pipes, with their historical significance and natural corrosion resistance, cater to niche sewer system applications. Their sustainability and durability ensure continued demand, though they hold a smaller market share compared to other materials.
By Diameter
In 2024, pipes with a diameter up to 1200 mm dominated, capturing over 39.4% of the Water and Wastewater Pipe Market share. These smaller pipes are versatile, widely used in residential, commercial, and industrial applications due to their ease of installation.
Pipes in the 1200 mm to 3600 mm range held a substantial market share with steady growth. These medium-sized pipes are critical for municipal water supply, wastewater management, and industrial applications requiring higher flow capacities.
Pipes with a diameter above 3600 mm showed promising growth potential, despite a smaller market share. These large-diameter pipes are vital for major infrastructure projects, including urban water distribution, sewage systems, and drainage networks.
By Business Type
The Aftermarket segment led the Water and Wastewater Pipe Market in 2024, securing over 72.3% of the share. This segment, encompassing replacement parts, maintenance, and repair services, reflects the ongoing need to maintain and extend the life of existing water and wastewater infrastructure.
The Original Equipment Manufacturer (OEM) segment, while smaller, showed steady growth by supplying new pipes, fittings, and equipment for infrastructure development. Though less dominant, OEMs remain essential for new projects and market expansion. The Aftermarket’s dominance underscores the critical role of maintenance in ensuring infrastructure efficiency, while OEMs support new installations and growth.
By Application
In 2024, the Water Supply & Distribution segment held the largest Water and Wastewater Pipe Market share, over 67.4%, driven by the demand for pipes to transport clean water from treatment plants to homes, businesses, and facilities. The Wastewater Management segment maintained a significant share with steady growth, supporting the collection and transport of wastewater to treatment facilities.
This segment is vital for environmental protection and public health. The Water Supply & Distribution segment’s dominance highlights the critical role of clean water infrastructure, while wastewater management addresses growing environmental and health concerns.
By End-Use
The Municipal segment led in 2024, capturing over 64.6% of the Water and Wastewater Pipe Market share, driven by the need for water supply and wastewater systems in urban areas. The Industrial segment held a significant share with steady growth, supporting applications in manufacturing, processing, and power generation.
The Agriculture segment, though smaller, showed growth potential, serving irrigation, drainage, and water distribution needs in farming. The Municipal segment’s dominance reflects the critical role of water infrastructure in urban development, while the Industrial and Agriculture segments meet diverse sectoral demands, contributing to overall market growth.
Market Key Segmentation
By Type
- Plastic
- Steel
- Ductile Iron
- Concrete
- Clay
By Diameter
- Up to 1200 mm
- 1200 mm to 3600 mm
- Above 3600 mm
By Business Type
- Original Equipment Manufacturer (OEM)
- Aftermarket
By Application
- Water Supply & Distribution
- Wastewater Management
By End-use
- Municipal
- Industrial
- Agriculture
Regional Analysis.
The Asia Pacific region is projected to dominate the global water and wastewater pipe market, accounting for a substantial 44.5% share. This leadership is primarily attributed to the increasing demand for advanced water management systems across vital sectors such as manufacturing, construction, and environmental sustainability.
Robust investments in water and wastewater infrastructure across countries like China, India, South Korea, Thailand, Malaysia, and Vietnam are anticipated to significantly propel market growth. This expansion is further supported by rising industrial activity and a strong regional focus on implementing sustainable water solutions to accommodate growing consumption needs and environmental objectives.
In North America, market growth is expected to be driven by economic development and the increasing demand for dependable water infrastructure in industries such as manufacturing and large-scale construction. The region’s dedication to reducing environmental impact and achieving renewable energy goals further reinforces the adoption of the water and wastewater pipe market.
Europe is also poised for notable growth in this market, supported by the widespread shift toward sustainable water practices among both industrial users and consumers. Rising demand from manufacturing, infrastructure modernization efforts, and resource conservation projects are contributing factors. Europe’s strategic emphasis on sustainability, environmental accountability, and energy autonomy continues to enhance the uptake of advanced water and wastewater piping solutions across the region.
Competitive Landscape
- Compagnie de Saint-Gobain S.A
- China Lesso Group Holdings Limited
- Aliaxis S.A.
- Mexichem
- S.A.B. de C.V.
- Sekisui Chemical Co.Ltd.
- Tenaris S.A.
- Welspun Corp Limited
- Nan Ya Plastics Corporation
- Advanced Drainage Systems Inc.
- Tata Steel Limited
- Wienerberger AG
- ISCO Industries LLC
Get in Touch with Us:
Market.us (Powered By Prudour Pvt. Ltd.)
Address: 420 Lexington Avenue, Suite 300, New York City, NY 10170, United States
Send Email: [email protected]
Refer To More Related Reports:
Hydrogen Cyanide
Hydrogen Generation Market
Hydrogen Peroxide Market



