
Paper-Based Wraparound Packaging Market to Reach USD 2.7 Billion by 2036 as Brands Qualify Recyclable, Machine-Ready Wraps
Market growth is being supported by recycled paperboard, beverage multipacks, retail-ready formats, and packaging redesign requirements
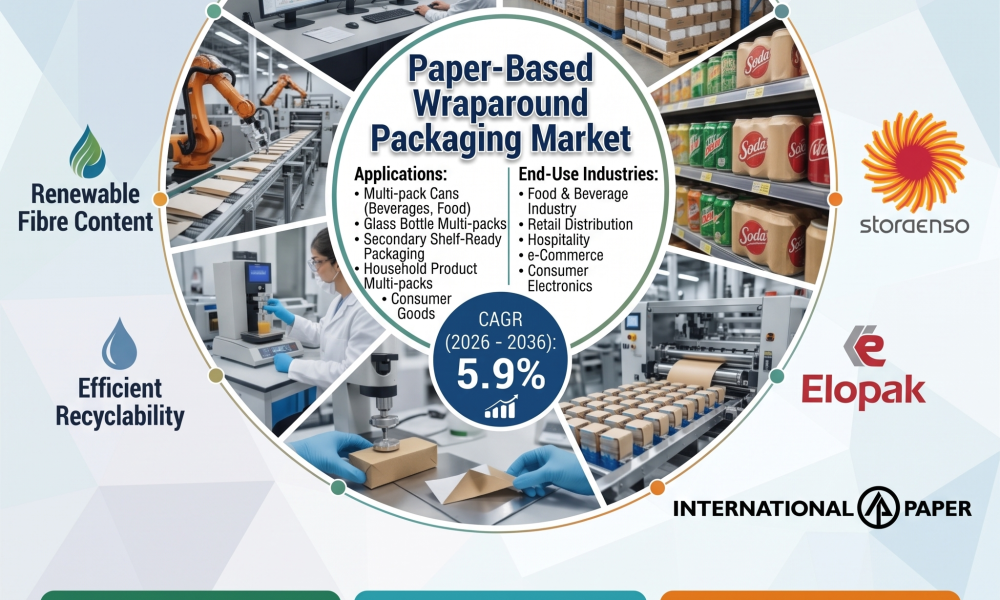
The global paper-based wraparound packaging market is projected to grow from USD 1.5 billion in 2026 to USD 2.7 billion by 2036, registering a 5.9% CAGR during the forecast period, according to Fact.MR analysis.
The market crossed USD 1.4 billion in 2025 as grouped-product packaging programs expanded across consumer-goods manufacturing. The market is expected to create an absolute opportunity of USD 1.2 billion through 2036, led by demand for wraparound cases and recycled paperboard, particularly across beverage applications.
Packaging engineers are evaluating paper-based wraps as brands seek to reduce plastic exposure without compromising compression performance during transport and retail handling. Beverage plants, food manufacturers, and retail teams are also assessing formats that can operate reliably on high-speed packing lines while supporting product identification and shelf handling.
Get detailed market forecasts, competitive benchmarking, and pricing trends https://www.factmr.com/connectus/sample?flag=S&rep_id=15830
Recycled Paperboard and Wraparound Cases Lead Key Segments
Wraparound cases are projected to account for 44.0% of the market in 2026, supported by repeatable machine formation. These structures allow grouped products to be contained while balancing board usage, transport protection, and printable surface area.
Recycled paperboard is expected to hold 48.0% share in 2026. Established recovery routes and board availability support its use in high-volume applications where stiffness and stable performance during scoring and gluing are required.
Preprinted formats are forecast to capture 46.0% share in 2026. Controlled graphics, recurring color requirements, and product coding support adoption across repeat packaging programs.
Beverages are expected to represent 34.0% share in 2026, reflecting standardized multipack production. Food and beverage is forecast to account for 62.0% of end-use demand, while direct-brand OEM sales are expected to represent 52.0% of the market.
Packaging Performance Remains Central to Adoption
Packaging redesign is creating opportunities for paper-based wraparound structures, but conversion requires detailed production-line qualification.
Packaging engineers must assess compression, moisture exposure, score depth, adhesive patterns, and feeding reliability before replacing established grouping formats. Chilled and humid distribution routes can create additional requirements because condensation and moisture may affect corners or adhesives.
High-speed qualification is identified as a major restraint. Differences in friction or score depth can interrupt production feeding and delay conversion until repeated plant trials demonstrate reliable performance.
Lightweight beverage wraps represent an opportunity where redesigned panels can reduce board use without weakening bundle control. Recycled-board food formats and nearby plant-trial support also provide opportunities for converters and packaging suppliers.
Regional Growth Varies Across Major Markets
India is projected to record an 8.3% CAGR through 2036, while China is expected to advance at 7.5%.
Brazil is forecast to register a 6.3% CAGR, supported by long distribution routes and packaging requirements. Germany and the United Kingdom are each estimated to grow at 5.6%.
Country-level demand is being shaped by packaging regulation, recyclability documentation, automated packing requirements, retail specifications, and the need for reliable performance across regional distribution networks.
Competitive Landscape
The competitive landscape includes Graphic Packaging International, Smurfit Westrock, Mondi Group, Stora Enso, and International Paper.
The market remains divided between integrated paperboard groups and regional converters. Qualification favors providers that can combine consistent board quality with technical support near recurring multi-plant programs.
Graphic Packaging International and Smurfit Westrock are profiled for direct wraparound coverage, while Mondi Group and Stora Enso add packaging and testing capabilities. International Paper provides industrial packaging coverage across European plants.
Shambhu Nath Jha, Principal Consultant at Fact.MR, states:
“Paper wraps create value once design teams prove line performance and retail handling across programs. Adoption is expected to favor converters that control board quality and support trials near packing lines.”
Report Scope
The Fact.MR analysis covers converted paper structures formed around grouped products for transport protection and retail handling. The study evaluates product type, material, print-finish, application, end use, sales channel, and regional demand.
The report covers 2026 to 2036 and includes analysis across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. The analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews.
To view related Reports
About (Fact.MR)
(Fact.MR) provides market research and business intelligence covering emerging markets, industry trends, demand patterns, competitive developments, and growth opportunities. Its research combines primary interviews, desk research, market sizing, forecasting, and data validation.



