
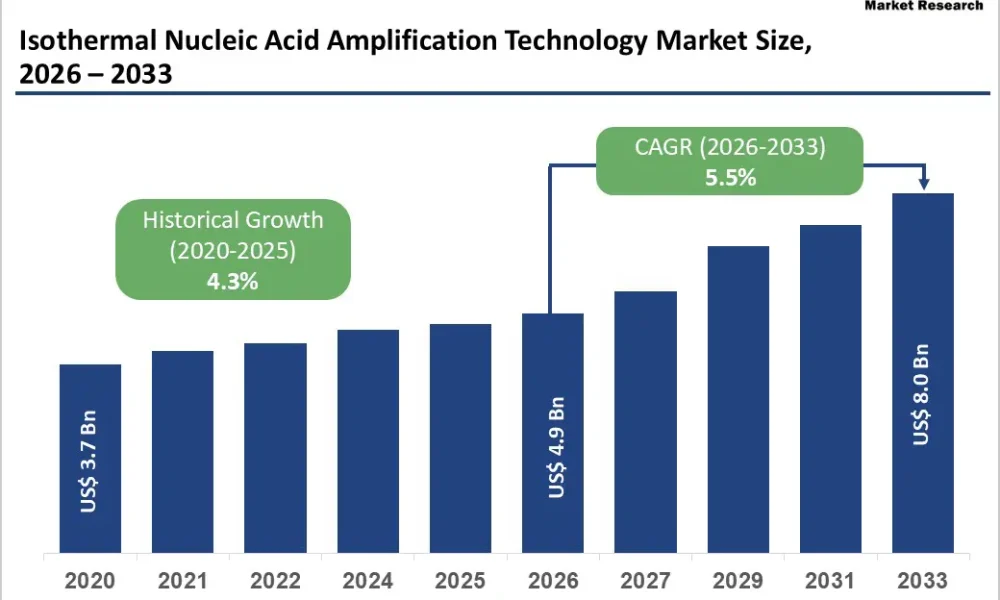
The global isothermal nucleic acid amplification technology market is poised for substantial growth, with its size estimated at US$ 4.9 billion in 2026 and projected to reach US$ 8.0 billion by 2033. The market is expected to expand at a compound annual growth rate (CAGR) of 5.5% from 2026 to 2033. This growth is primarily driven by the rising demand for rapid, sensitive, and cost-effective molecular diagnostic solutions across clinical, public health, and decentralized testing environments.
The adoption of isothermal nucleic acid amplification technologies (INAAT) is increasing as they allow nucleic acid detection without the need for complex thermal cycling, enabling faster turnaround times and simplified workflows compared with conventional PCR. Technological advancements in enzyme performance, assay chemistry, and signal detection have enhanced sensitivity and specificity, allowing broad applications in blood screening, pathogen identification, and point-of-care diagnostics. The shift toward decentralized testing models, including near-patient and field-based applications, further accelerates market growth. Integration of isothermal platforms with portable instruments, automation, and digital reporting tools is enhancing operational efficiency and scalability. Public health funding, increased diagnostic preparedness initiatives, and rising healthcare investments in emerging markets continue to reinforce long-term market demand. Continuous innovation in reagents, multiplex assay development, and workflow integration supports sustained growth across hospitals, diagnostic laboratories, and research institutions.
Download Your Free Sample & Explore Key Insights: https://www.persistencemarketresearch.com/samples/33206
Key Industry Highlights
Leading Region: North America holds the largest share at 47.3%, supported by advanced diagnostic infrastructure, high healthcare spending, strong public health surveillance systems, early adoption of rapid molecular testing, and the presence of leading diagnostics companies.
Fastest-Growing Region: Asia Pacific is expanding the fastest due to increasing healthcare investments, strengthening laboratory infrastructure, rising infectious disease burden, rapid expansion of hospitals and diagnostic laboratories, and growing adoption of point-of-care molecular testing.
Leading Product Segment: Instruments dominate the market due to widespread deployment of isothermal amplification systems in clinical laboratories, blood banks, and decentralized testing environments.
Fastest-Growing Product Segment: Reagents are growing steadily as rising testing volumes, repeat screening, and routine infectious disease diagnostics drive recurring consumable demand.
Leading Application Segment: Blood screening remains the top segment, driven by high-volume testing requirements, transfusion safety regulations, and growing emphasis on early pathogen detection.
Fastest-Growing Application Segment: Infectious disease diagnostics is witnessing strong growth due to rising outbreak preparedness efforts, expanding point-of-care testing, and increasing reliance on rapid molecular detection technologies.
Global Market Attributes
Isothermal Nucleic Acid Amplification Technology Market Size (2026E): US$ 4.9 Bn
Market Value Forecast (2033F): US$ 8.0 Bn
Projected Growth (CAGR 2026 to 2033): 5.5%
Historical Market Growth (CAGR 2020 to 2025): 4.3%
Market Dynamics
Driver – Rising Demand for Rapid, Decentralized Molecular Diagnostics and Point-of-Care Testing
Market growth is being propelled by the increasing need for fast, accurate, and infrastructure-light molecular diagnostic solutions across healthcare and public health settings. Isothermal nucleic acid amplification technologies enable nucleic acid detection without complex thermal cycling, making them ideal for point-of-care, near-patient, and field-based testing. Rising incidence of infectious diseases, recurring outbreak scenarios, and the necessity for timely clinical decision-making have intensified adoption of rapid amplification platforms in hospitals, diagnostic laboratories, and emergency care environments.
Public health surveillance programs increasingly rely on isothermal methods for large-scale screening and outbreak monitoring due to their short turnaround times and operational simplicity. Expanding use of molecular diagnostics in blood screening, transplant safety, and antimicrobial resistance testing is supporting sustained demand. Technological advancements have improved assay sensitivity, specificity, and multiplexing capabilities, enabling broader clinical utility beyond infectious disease detection. Integration of isothermal platforms with portable detection systems and digital reporting tools enhances usability in decentralized settings. Government and healthcare provider investments in diagnostic preparedness are expanding installed bases, collectively driving consistent adoption across developed and emerging healthcare systems.
Restraints – Performance Variability, Standardization Gaps, and Integration Challenges
Several factors restrict wider adoption of isothermal nucleic acid amplification technologies. Performance variability across different methods can affect sensitivity and specificity, particularly in low-viral-load samples or complex biological matrices. Unlike conventional PCR, some isothermal assays face challenges related to nonspecific amplification and assay optimization, impacting clinical confidence. Lack of universal standardization across platforms and protocols complicates result comparability between laboratories. Operational constraints also persist, as integrating isothermal systems into existing workflows and information systems may require additional validation and training.
Reagent stability, storage requirements, and supply chain reliability pose challenges in resource-limited settings. Regulatory approval pathways for newer assays can be lengthy, delaying commercialization. Limited awareness among smaller healthcare facilities and uneven reimbursement policies across regions can further slow adoption. These technical, regulatory, and operational barriers moderate expansion, particularly outside well-established diagnostic markets.
Opportunity – Expansion into Emerging Markets, Home Testing, and Multiplex Assay Development
Significant opportunities are emerging from the expansion of molecular diagnostics beyond centralized laboratories into community, home-care, and low-resource settings. Isothermal amplification technologies support self-testing, mobile diagnostics, and decentralized screening programs due to their simplicity and minimal equipment requirements. Rising healthcare access initiatives and infectious disease screening programs in emerging economies create strong demand for cost-effective and scalable amplification solutions.
Development of multiplex assays capable of detecting multiple pathogens simultaneously presents additional growth potential, particularly for respiratory infections, sexually transmitted diseases, and blood-borne pathogens. Integration with digital health platforms, smartphone-based readers, and cloud-connected reporting systems enhances clinical value and adoption. Biotechnology startups and contract manufacturers are accelerating assay innovation and localized production, improving affordability and supply resilience. Partnerships between diagnostic companies, public health agencies, and non-governmental organizations expand deployment in surveillance and outbreak response programs. As global focus shifts toward early detection, prevention, and rapid response, these advancements are expected to unlock new revenue streams and support long-term market expansion.
Get Custom Insights Designed for Your Businecss: https://www.persistencemarketresearch.com/request-customization/33206
Category-wise Analysis
By Product, Instruments Dominate Owing to Widespread Deployment in Rapid Molecular Testing
Instruments are projected to dominate the market in 2026, accounting for a revenue share of 58.0%. This dominance is driven by increasing adoption of automated and semi-automated isothermal amplification platforms across clinical diagnostics, point-of-care testing, and public health laboratories. Hospitals and diagnostic laboratories rely on compact amplification systems and integrated detection platforms to meet rising demand for rapid, sensitive, and decentralized molecular diagnostics. Technological improvements in assay sensitivity, multiplexing capability, portability, and workflow integration are encouraging replacement of conventional PCR systems with isothermal platforms. Deployment in emergency care, remote settings, and resource-limited environments supports sustained capital spending. Instruments are expected to retain their leading revenue contribution throughout the forecast period.
By Application, Blood Screening Leads Due to High-Volume Testing and Regulatory Mandates
Blood screening is expected to lead the market in 2026, capturing a revenue share of 21.6%. Isothermal nucleic acid amplification technologies are critical for ensuring transfusion safety through rapid and highly sensitive pathogen detection. Blood banks increasingly adopt these methods for early identification of viral and bacterial contaminants, including HIV, hepatitis, and emerging infectious agents. Rapid results without complex thermal cycling make these technologies suitable for high-throughput workflows. Regulatory emphasis on minimizing transfusion-transmitted infections reinforces adoption. Expanding voluntary blood donation programs and rising demand for safe blood products in surgical and trauma care further drive testing volumes. Blood screening is expected to maintain its leading position among application segments.
By End User, Diagnostic Laboratories Lead Driven by Large-Scale Testing Demand
Diagnostic laboratories are projected to dominate the market in 2026, accounting for a revenue share of 34.5%. Centralized and reference laboratories conduct high volumes of molecular diagnostic testing and increasingly rely on isothermal amplification technologies for infectious disease testing, outbreak surveillance, and routine molecular screening due to speed, scalability, and operational efficiency. The shift toward decentralized sample collection, combined with centralized testing models, strengthens laboratory demand for reliable amplification platforms. Investments in laboratory automation, quality control, and regulatory compliance enable rapid adoption of advanced diagnostics. Collaborations with hospitals, public health agencies, and research institutions expand testing volumes, maintaining diagnostic laboratories as the leading end-user segment throughout the forecast period.
Region-wise Insights
North America Isothermal Nucleic Acid Amplification Technology Market Trends
North America is expected to dominate the market with a value share of 47.7% in 2026, led by the United States. The region benefits from a mature diagnostics ecosystem, strong molecular testing infrastructure, and early adoption of advanced diagnostic technologies. High prevalence of infectious diseases and preparedness for outbreak response drive demand for rapid amplification methods. Government funding and public health programs support large-scale deployment across hospitals and laboratories. The presence of leading diagnostic manufacturers accelerates innovation and commercialization. Favorable reimbursement policies, well-established regulatory frameworks, and strong intellectual property protection further support growth. Awareness of point-of-care diagnostics, skilled laboratory professionals, and integration of automation and digital health solutions sustain North America’s leadership.
Europe Isothermal Nucleic Acid Amplification Technology Market Trends
Europe is projected to grow steadily, supported by robust public healthcare systems, strong academic research networks, and emphasis on rapid diagnostics. Germany, the U.K., France, Italy, and Spain are leading adoption due to established laboratory infrastructure and proactive infectious disease surveillance programs. EU-backed research initiatives and cross-border collaborations advance molecular diagnostics and standardize testing protocols. Public healthcare reimbursement ensures broad diagnostic access. Growing adoption in hospitals, blood banks, and emergency care settings, alongside investments in laboratory modernization, workforce training, and digital integration, support consistent market expansion while maintaining Europe’s strong position.
Asia Pacific Isothermal Nucleic Acid Amplification Technology Market Trends
Asia Pacific is expected to register the highest CAGR of around 7.6% between 2026 and 2033, driven by expanding healthcare infrastructure, rising diagnostic awareness, and increasing government investments in molecular testing. China, India, Japan, South Korea, and Australia are strengthening diagnostic capabilities through public health initiatives and laboratory expansion. Population growth, rising infectious disease burden, and frequent outbreaks accelerate demand for rapid and scalable testing solutions. Local diagnostic manufacturers and cost-effective production further support penetration. Point-of-care diagnostics in rural and semi-urban areas are expanding, while participation in global surveillance programs and integration of digital health platforms enhance regional capabilities. These factors position Asia Pacific as the fastest-growing regional market.
Checkout Now & Download Complete Market Report: https://www.persistencemarketresearch.com/checkout/33206
Market Competitive Landscape
The global isothermal nucleic acid amplification technology market is highly competitive, with leading companies including QIAGEN, Quidel Corporation, Thermo Fisher Scientific, Inc., BD, and Alere, Inc. These players leverage global distribution networks, brand equity, and diversified life science and diagnostics portfolios to address demand for rapid, sensitive, and cost-effective molecular testing solutions.
Product portfolios include isothermal amplification–based instruments, reagents, and assay kits for infectious disease detection, blood screening, and decentralized applications. Continuous innovation in assay design, point-of-care compatibility, workflow automation, and multiplexing capabilities, along with adherence to regulatory and quality standards, is critical for maintaining competitive advantage.
Key Industry Developments
In March 2025, a study highlighted advancements in isothermal nucleic acid amplification–based detection methods, emphasizing improvements in sensitivity, assay speed, and applicability for rapid molecular diagnostics. The findings underscored the increasing relevance of isothermal techniques as alternatives to conventional PCR for clinical and field-based testing.
Companies Covered in the Global Market
QIAGEN
Quidel Corporation
Thermo Fisher Scientific, Inc.
BD
Alere, Inc.
bioMerieux SA
Eiken Chemical Co. Ltd
Hologic Inc. (Gen-Probe)
Lucigen
Meridian Bioscience, Inc.
Ustar Biotechnologies Ltd.
OptiGene Limited
Conclusion
The global isothermal nucleic acid amplification technology market is on a strong growth trajectory, driven by the rising demand for rapid, sensitive, and cost-effective molecular diagnostic solutions. Its ability to detect nucleic acids without complex thermal cycling makes it ideal for point-of-care, near-patient, and field-based testing, which is increasingly critical in responding to infectious disease outbreaks, blood screening, and decentralized healthcare needs. Technological advancements in assay chemistry, enzyme performance, and detection methods are enhancing sensitivity, specificity, and multiplexing capabilities, further broadening clinical applications.
North America remains the largest market due to advanced infrastructure and strong adoption of molecular diagnostics, while Asia Pacific is the fastest-growing region owing to expanding healthcare access, rising infectious disease burden, and government investments. Instruments continue to dominate the product segment, supported by hospitals, diagnostic laboratories, and public health programs, while reagents and multiplex assays present significant growth opportunities. Blood screening and infectious disease diagnostics are key applications, reflecting high-volume testing needs and the global focus on early detection and outbreak preparedness.




