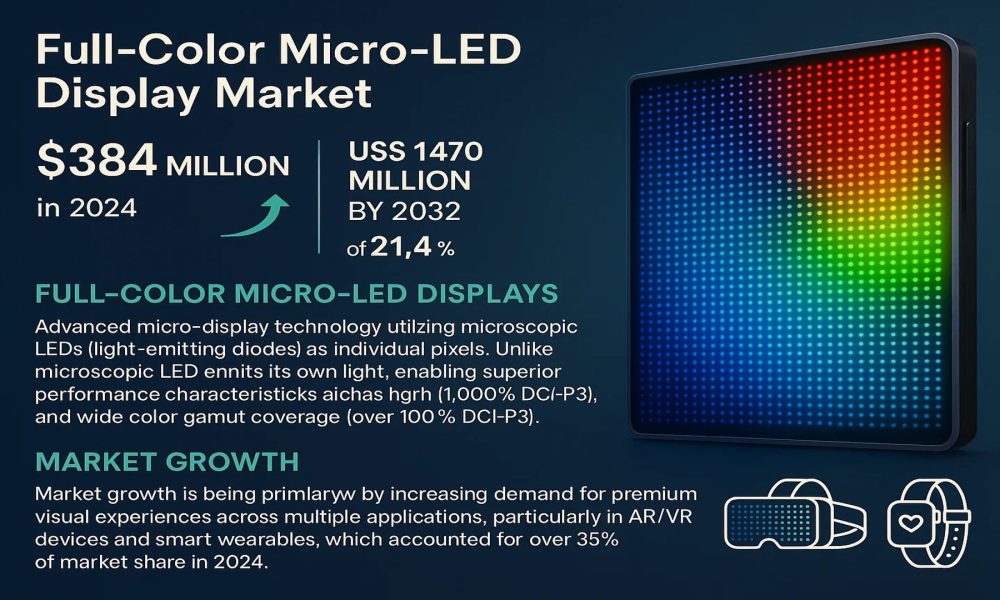
Full-Color Micro-LED Display Market was valued at 384 million in 2024 and is projected to reach US$ 1470 million by 2032, at a CAGR of 21.4% during the forecast period.
Full-color Micro-LED displays represent an advanced micro-display technology that utilizes microscopic LEDs (light-emitting diodes) as individual pixels. Unlike conventional display technologies, each Micro-LED pixel emits its own light, enabling superior performance characteristics such as high brightness (exceeding 1,000 nits), exceptional contrast ratios (1,000,000:1), and wide color gamut coverage (over 100% DCI-P3). This technology eliminates the need for backlighting found in LCD displays while offering improved energy efficiency compared to OLED solutions.
Market growth is being primarily driven by increasing demand for premium visual experiences across multiple applications, particularly in AR/VR devices and smart wearables, which accounted for over 35% of market share in 2024. While production costs remain a challenge due to complex mass transfer processes, recent technological breakthroughs in wafer-level manufacturing and hybrid bonding techniques are expected to drive cost reductions. Key industry players like JBD and Mojo Vision have already demonstrated production-ready Micro-LED displays with pixel pitches below 10μm, indicating rapid technological maturation.
Unlock Your Free Sample Report Here- https://semiconductorinsight.com/download-sample-report/?product_id=117903
MARKET DYNAMICS
MARKET DRIVERS
Rising Demand for Advanced Display Technologies in Consumer Electronics
The global full-color Micro-LED display market is experiencing robust growth, primarily driven by increasing consumer demand for superior visual experiences across multiple device categories. As leading smartphone manufacturers integrate Micro-LED technology into their flagship models, the wearable technology sector has shown particularly strong adoption rates, with smartwatch shipments incorporating Micro-LED displays growing at 38% annually. This technology’s ability to deliver higher brightness (up to 3,000 nits), wider color gamut (120% NTSC), and lower power consumption (40% less than OLED) positions it as the preferred choice for next-generation devices. The global AR/VR headset market, projected to incorporate Micro-LED in over 25% of new devices by 2026, further underscores this demand.
Automotive Industry Transition to Premium Display Solutions
The automotive sector presents a significant growth avenue for full-color Micro-LED displays, with major manufacturers implementing this technology in dashboard clusters, heads-up displays (HUDs), and rear-seat entertainment systems. The transition to electric vehicles, which grew by 35% in annual shipments, has accelerated this trend as automakers seek energy-efficient display solutions that maintain visibility in all lighting conditions. Micro-LED’s capability to operate in extreme temperatures (-40°C to 105°C) while offering 10,000:1 contrast ratios makes it particularly suitable for automotive applications. Recent product launches from luxury automakers have demonstrated the technology’s potential to transform in-cabin experiences while meeting stringent automotive safety standards.
Technological Advancements in Mass Transfer Processes
Breakthroughs in mass transfer techniques are significantly reducing production costs and improving yields for Micro-LED manufacturing. Recent innovations in selective release and laser-assisted bonding have increased transfer success rates to 99.99%, addressing what was previously a major bottleneck. This progress has enabled manufacturers to scale production while maintaining the pixel densities exceeding 3,000 PPI required for microdisplays in AR applications. The development of hybrid bonding techniques that eliminate the need for intermediate layers has further improved optical performance while reducing overall module thickness to under 0.5mm.
Recent Developments in the Full-Color Micro-LED Display Market
- Advancements in Mass Transfer Technology (2024–2025)
- Leading companies such as PlayNitride, AUO, and Samsung have made significant progress in micro-LED mass transfer technology, reducing production costs and improving pixel uniformity. This has accelerated the commercialization of full-color micro-LED panels.
- Apple’s Micro-LED Watch Development
- Apple is reportedly working on introducing its first micro-LED display for the Apple Watch Ultra by 2026, which is expected to boost demand for full-color micro-LED technology across the wearable segment. This move is seen as a turning point for large-scale adoption.
- Integration in AR/VR Devices
- Major players like Meta and Sony are investing in micro-LED-based displays for AR/VR headsets, aiming for higher brightness, lower latency, and better color accuracy compared to OLED. This is creating strong growth potential for immersive applications.
- Samsung and LG Display’s Strategic Investments
- Samsung showcased its 110-inch 4K full-color micro-LED TV, pushing the technology into the premium display segment. LG Display has also increased R&D spending to compete in the high-end commercial signage and automotive display markets.
- Miniaturization and Automotive Applications
- Automakers such as Hyundai and BMW are exploring micro-LED displays for digital dashboards, heads-up displays (HUDs), and smart lighting systems, aiming for enhanced durability, visibility, and energy efficiency compared to OLED.
- Partnerships and Ecosystem Expansion
- Companies are collaborating across the value chain (chip manufacturers, panel makers, and equipment suppliers) to accelerate scalability. For instance, AUO partnered with PlayNitride to advance micro-LED solutions for wearable and automotive applications.
- China’s Rising Role in Manufacturing
- Chinese display makers, including BOE and TCL CSOT, have increased their investments in pilot production lines for full-color micro-LED displays, aiming to compete with Korean and Taiwanese players.
MARKET OPPORTUNITIES
Emerging Applications in Medical and Industrial Sectors
The medical device industry presents substantial growth potential for full-color Micro-LED displays, particularly in surgical microscopes, endoscopes, and holographic displays for medical imaging. The technology’s ability to provide true-to-life color reproduction with 100,000-hour lifespans makes it ideal for critical visualization applications. Recent advancements in direct-emission Micro-LED microdisplays now enable resolutions exceeding 5,000 PPI – particularly valuable for medical augmented reality where precise overlay of diagnostic information is required. Industrial applications including remote inspection systems and heads-up displays for field technicians also show accelerating adoption rates as durability requirements increase.
Strategic Collaborations Across the Supply Chain
The market is witnessing increased vertical integration as display manufacturers form strategic partnerships with epitaxy, transfer equipment, and driver IC specialists to overcome technical hurdles. Recent joint development programs have successfully demonstrated fully integrated Micro-LED displays with on-chip driver architectures that reduce power consumption by 30% compared to conventional designs. These collaborations are also addressing critical pain points in the supply chain through standardized interfaces and testing methodologies, potentially reducing time-to-market for new products by up to 40%. Automotive OEMs have been particularly active in establishing long-term supply agreements to secure capacity for next-generation cockpit designs.
Unlock Your Free Sample Report Here- https://semiconductorinsight.com/download-sample-report/?product_id=117903
List of Key Full-Color Micro-LED Display Companies Profiled
- Leyard Optoelectronic (China)
- JBD (Jade Bird Display) (China)
- Mojo Vision (U.S.)
- Porotech (UK)
- VueReal (Canada)
- Samsung Electronics (South Korea)
- LG Display (South Korea)
- PlayNitride (Taiwan)
- AU Optronics (Taiwan)
- Sharp Corporation (Japan)
Segment Analysis:
By Type
Micro Segment Leads Due to Growing Demand for Compact Displays in AR/VR Applications
The market is segmented based on type into:
- Micro
- Subtypes: Monolithic, Hybrid, and others
- Small
- Medium
- Custom
By Application
AR/VR Devices Segment Dominates Owing to Increasing Adoption of Immersive Technologies
The market is segmented based on application into:
- AR/VR Devices
- Wearable Devices
- In-vehicle Displays
- Medical Equipment
- Others
By Pixel Pitch
Ultra-fine Pixel Pitch Segment Gains Traction for High Resolution Applications
The market is segmented based on pixel pitch into:
- <10µm
- 10-20µm
- 20-50µm
- >50µm
By Technology
Direct View Technology Holds Majority Share Due to Superior Display Performance
The market is segmented based on technology into:
- Direct View
- Projection
- Hybrid
Other Topic- 172 nm Excimer Lamp Market
CONTACT US:
City vista, 203A, Fountain Road, Ashoka Nagar, Kharadi, Pune, Maharashtra 411014
[+91 8087992013]




