
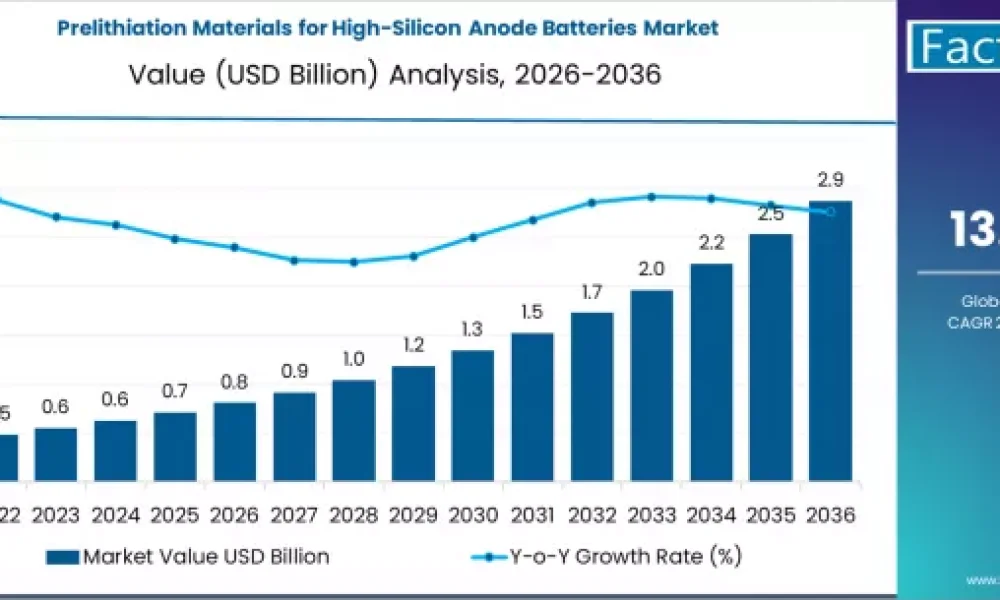
The global prelithiation materials for high-silicon anode batteries market is set for strong and sustained growth over the next decade, fueled by the rapid expansion of electric vehicles (EVs), rising demand for high-energy-density lithium-ion batteries, and advancements in next-generation battery chemistries. According to a new analysis by Fact.MR, the market is projected to grow from USD 0.81 billion in 2026 to USD 2.87 billion by 2036, reflecting a remarkable 254.3% total growth over the forecast period.
This expansion represents a robust compound annual growth rate (CAGR) of 13.5% between 2026 and 2036, underscoring the critical role of prelithiation technologies in enabling high-silicon anode adoption across EV and energy storage applications.
The increasing need to mitigate initial lithium loss, improve cycle life, and enhance energy density in silicon-rich anodes is positioning prelithiation materials as a key enabler in next-generation lithium-ion battery architectures.
To access the complete data tables and in-depth insights, request a Discount On The Report here: https://www.factmr.com/connectus/sample?flag=S&rep_id=13023
Strategic Market Drivers
High-Silicon Anode Adoption Accelerates Market Growth
Silicon anodes offer up to 10x higher theoretical capacity compared to traditional graphite anodes, making them essential for next-generation high-energy batteries. However, silicon’s inherent volume expansion and irreversible lithium loss during initial cycles have increased the need for effective prelithiation materials to stabilize performance.
Prelithiation solutions significantly improve:
- First-cycle efficiency
- Battery lifespan
- Energy retention
- Overall cell reliability
Electric Vehicles and High-Energy Traction Cells Fuel Demand
The EV and high-energy traction cells segment is expected to account for 58.0% of the global market in 2026, driven by rising EV penetration and OEM focus on longer driving ranges and faster charging.
Prelithiation materials are increasingly used in:
- Passenger EVs
- Commercial EV fleets
- Electric buses
- Performance-oriented EV platforms
OEMs and battery manufacturers are actively integrating prelithiated silicon anodes to meet stringent performance benchmarks.
Growing Investments in Advanced Battery R&D
Rising investments in solid-state batteries, lithium-metal hybrids, and silicon-dominant anode systems are accelerating commercialization of prelithiation technologies. Research institutions and battery startups are collaborating with material suppliers to improve scalability and cost efficiency.
Advancements in chemical prelithiation agents, stabilized lithium powders, and sacrificial lithium additives are broadening application potential across battery formats.
Regional Growth Highlights
East Asia: Battery Manufacturing Hub
China, Japan, and South Korea dominate the market due to:
- Strong lithium-ion battery supply chains
- High EV production volumes
- Aggressive investments in silicon anode innovation
China remains a major consumer of prelithiation materials, supported by large-scale battery gigafactories.
North America: EV Innovation and Battery Scaling
The U.S. market is witnessing rapid growth driven by:
- Expansion of domestic battery manufacturing
- Federal incentives for EVs and clean energy
- Increasing adoption of silicon-rich anode chemistries
Leading battery startups and automotive OEMs are accelerating prelithiation material adoption.
Europe: Sustainability and Energy Storage Push
Europe’s strong focus on:
- EV electrification
- Renewable energy storage
- Battery recycling and efficiency
is supporting demand for advanced battery materials, including prelithiation solutions, across Germany, France, and Nordic countries.
Market Segmentation Insights
By Material Type
- Stabilized Lithium Metal Powder (SLMP) – Widely adopted
- Lithium-Rich Alloys – Growing demand
- Chemical Prelithiation Agents – Emerging segment
By Application
- EV & High-Energy Traction Cells – Fastest-growing segment
- Consumer Electronics – Smartphones, laptops
- Energy Storage Systems (ESS) – Grid and renewable integration
- Industrial Batteries – Automation and backup power
By Battery Type
- Lithium-Ion Batteries
- Solid-State and Hybrid Batteries
Challenges Impacting Market Growth
High Material and Processing Costs
Prelithiation materials require controlled handling and specialized processing, increasing manufacturing costs and limiting adoption in cost-sensitive markets.
Scalability and Safety Concerns
Handling lithium-based materials presents challenges related to:
- Moisture sensitivity
- Process integration
- Safety compliance
Manufacturers are actively developing safer and more scalable prelithiation solutions.
Competitive Landscape
The market remains technology-driven and moderately consolidated, with companies focusing on:
- Material stabilization techniques
- Cost reduction strategies
- Compatibility with large-scale battery manufacturing
Key Players Operating in the Market
- FMC Corporation
- Albemarle Corporation
- Livent
- Materion Corporation
- Targray Technology
- Shenzhen Kejing
- Custom Battery Materials Developers
Strategic partnerships with battery OEMs and EV manufacturers remain a core growth strategy.
Recent Developments
- 2024: Battery manufacturers advance chemical prelithiation methods to improve silicon anode stability
- 2023: EV battery startups integrate prelithiation materials into high-capacity lithium-ion cells
- 2022: Pilot-scale commercialization of stabilized lithium powders accelerates adoption
Future Outlook: Powering the Next Generation of High-Energy Batteries
The coming decade will witness transformational growth in prelithiation materials driven by:
- Rapid EV adoption
- Demand for longer-range batteries
- Expansion of high-silicon anode technologies
- Advancements in lithium handling and safety
- Shift toward ultra-high energy density battery architectures
As battery manufacturers race to unlock higher performance, improved cycle life, and greater efficiency, prelithiation materials for high-silicon anode batteries are set to become a critical component of the global energy storage ecosystem through 2036.
Have a specific Requirements and Need Assistant on Report Pricing or Limited Budget please contact us – [email protected]
About Fact.MR
Fact.MR is a global market research and consulting firm, trusted by Fortune 500 companies and emerging businesses for reliable insights and strategic intelligence. With a presence across the U.S., UK, India, and Dubai, we deliver data-driven research and tailored consulting solutions across 30+ industries and 1,000+ markets. Backed by deep expertise and advanced analytics, Fact.MR helps organizations uncover opportunities, reduce risks, and make informed decisions for sustainable growth.



