
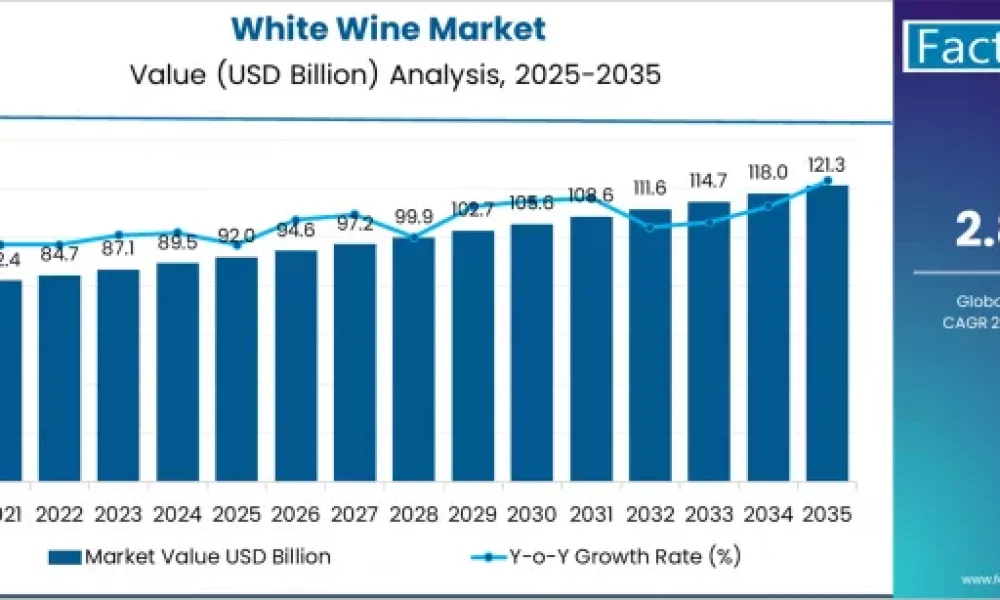
The global white wine market is projected to increase from approximately USD 92.0 billion in 2025 to around USD 122.0 billion by 2035, representing a compound annual growth rate (CAGR) of roughly 2.8% over the forecast period. Market expansion is underpinned by stable consumer demand, evolving preferences toward white varietals, growth in off‑trade channels, and broadening distribution in emerging markets.
White wine—covering styles such as Chardonnay, Sauvignon Blanc and Pinot Grigio—is increasingly seeing premiumisation in mature markets and growing acceptance in emerging geographies, supporting volume and value growth despite relatively modest overall CAGR.
Key Market Insights at a Glance
Market Value (2025): USD 92.0 billion
Forecast Value (2035): USD 122.0 billion
CAGR (2025–2035): ~2.8%
Leading Variety: Chardonnay (~28.0% share)
Dominant Channel: Off‑trade (~74.0% share)
Key Growth Regions: North America, Europe, Asia‑Pacific
Top Players: E. & J. Gallo; Constellation; Treasury; Pernod Ricard; Castel; Accolade; The Wine Group; Diageo; LVMH; Concha y Toro
To Access the Complete Data Tables & in-depth Insights, Request a Discount on this report: https://www.factmr.com/connectus/sample?flag=S&rep_id=159
Market Drivers / Growth Overview
The white wine market’s growth is driven by several structural factors:
Varietal preference and premiumisation: Chardonnay leads as a global staple, benefitting from strong brand recognition and broad consumer acceptance, helping maintain value‑growth amid slower overall market expansion.
Off‑trade channel dominance: With approximately three‑quarters of consumption taking place through off‑trade retail channels, increased supermarket penetration, convenience formats and retail promotions are supporting sustained demand.
Expansion in emerging markets: Growth in Asia‑Pacific, Latin America and Africa is generating incremental volume for white wine, as urbanisation, disposable income and Western dining trends extend reach.
Innovation and niche segmentation: Winemakers are exploring specialty white wines, organic/eco‑friendly offerings and novel packaging formats to attract younger and health‑conscious consumers.
Supply‑chain optimisation and mix improvements: Producers and distributors are refining logistics, packaging and variety portfolios to control costs and protect margins in a slow‑growth environment.
Challenges remain, including slower growth rates in mature regions (e.g., Europe), substitution by reds or other beverages in some markets, and input‑cost volatility (grape harvests, climate impacts) that can affect pricing and margins.
Segmentation & Key Drivers
By Variety:
Chardonnay (~28.0% share) remains the dominant variety, thanks to global recognition and broad availability.
Sauvignon Blanc, Pinot Grigio, and Other white varietals contribute significant shares and offer diversification opportunities for producers.
By Channel:
Off‑trade (~74.0%) leads, reflecting strong retail distribution, at‑home consumption and convenience purchase trends.
On‑trade (restaurants, bars) participates in value growth, though volume expansion is more limited and sensitive to economic cycles.
Segmental growth is influenced by consumer preference, retail expansion, varietal branding, packaging innovations and regional supply‑chain efficiencies.
Regional & Country Insights
Europe: A mature market supporting a large share of white wine consumption; major producers maintain strong export and domestic positions, though growth is modest.
North America: Growth driven by brand premiumisation, varietal experimentation and expansion of retail formats targeted at white wine.
Asia‑Pacific: The fastest growth potential region, with rising white wine adoption as per capita income grows, retail modernisation expands and western food‑pairing trends spread.
Latin America / Middle East & Africa: Opportunity zones for incremental volume, though currently smaller base, as distribution, retail infrastructure and wine culture continue to develop.
Regional performance depends on varietal penetration, retail channel growth, consumer education and supply‑chain sophistication.
Competitive Landscape
The white wine market is moderately competitive and characterised by large global wine companies, domestic producers and regional brands. Key players include E. & J. Gallo, Constellation, Treasury, Pernod Ricard, Castel, Accolade, The Wine Group, Diageo, LVMH and Concha y Toro.
Competitive strategies focus on:
Developing strong varietal branding and premium white‑wine line‑ups.
Investing in off‑trade retail partnerships, private‑label white‑wine programmes and convenience packaging (e.g., single‑serve, can formats).
Expanding presence in emerging markets through export strategies, local production and regional brand adaptation.
Monitoring grape‑supply risks and optimising vineyard/harvest operations to manage cost pressures and maintain margin stability.
Market Outlook & Strategic Insights
Over the forecast period through 2035, the white wine market is expected to deliver steady, moderate growth, driven by premiumisation, varietal leadership and expansion in emerging markets. Strategic imperatives for stakeholders include:
Focusing on Chardonnay and other high‑recognition varietals, which continue to anchor consumer preference and brand value.
Expanding presence in off‑trade retail channels and leveraging convenience formats to capture volume and value.
Prioritising Asia‑Pacific and other emerging regions where white‑wine consumption still has room to grow.
Investing in premium, niche and packaging innovations (e.g., premium blends, organic offerings, alternative packaging) to differentiate in competitive landscapes.
Managing raw‑material (grape) supply, climate risk and cost pressures carefully to protect margin and product availability.
Companies that align with these strategic priorities—while maintaining brand strength, varietal authenticity and global distribution—will be well‑positioned to capture value in a market projected to reach about USD 122.0 billion by 2035.
Purchase Full Report for Detailed Insights
For access to full forecasts, regional breakouts, company share analysis, and emerging trend assessments, you can purchase the complete report: https://www.factmr.com/checkout/159
Have specific requirements or need assistance on report pricing or have a limited budget? Please contact [email protected]
Contact:
US Sales Office
11140 Rockville Pike
Suite 400
Rockville, MD 20852
United States
Tel: +1 (628) 251-1583, +353-1-4434-232
Email: [email protected]
About Fact.MR:
Fact.MR is a global market research and consulting firm, trusted by Fortune 500 companies and emerging businesses for reliable insights and strategic intelligence. With a presence across the U.S., UK, India, and Dubai, we deliver data-driven research and tailored consulting solutions across 30+ industries and 1,000+ markets. Backed by deep expertise and advanced analytics, Fact.MR helps organizations uncover opportunities, reduce risks, and make informed decisions for sustainable growth.



