
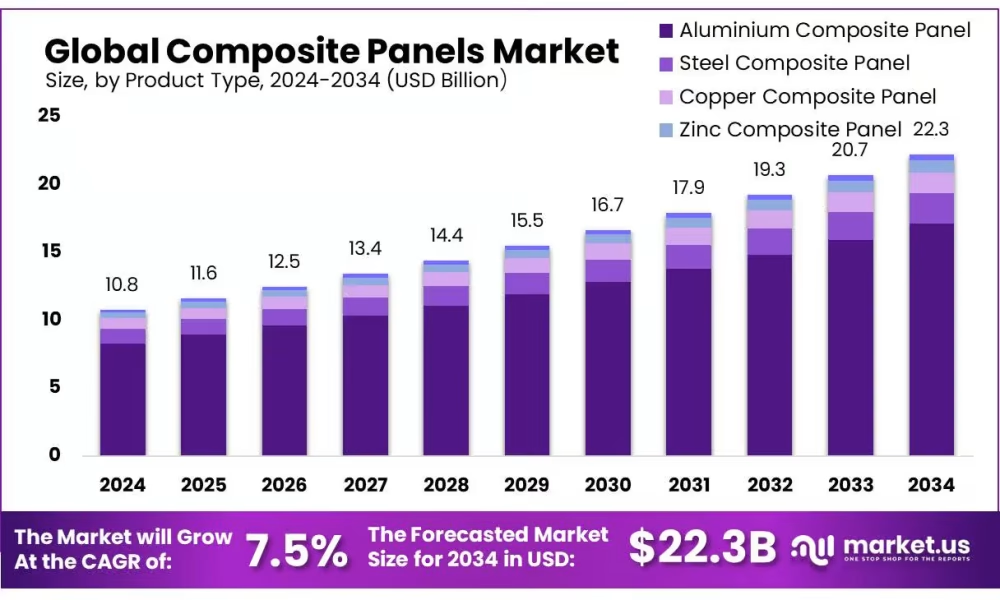
According to market.us, the global composite panels market is projected to reach approximately USD 22.3 billion by 2034, up from USD 10.8 billion in 2024, expanding at a CAGR of 7.5% during 2025–2034. Composite panels—made from thermoset or thermoplastic matrices reinforced with fibers such as glass or carbon—are widely used in building façades, transportation, aerospace, and renewable energy applications. Thermoset composites dominate the reinforced polymer composites market, accounting for approximately 80% of the market share due to their favorable processing properties and viscosity.
Market growth is driven by benefits such as reduced wall load from thinner panels, improved insulation, and design flexibility, all of which align with global trends in sustainable construction. Policy incentives and climate goals further fuel demand. For instance, India’s National Solar Mission targets 500 GW of renewable energy capacity by 2030—250 GW from solar, boosting the use of solar-ready materials like composite panels. Additionally, under India’s NMEEE, energy savings equivalent to 23 million tonnes of fuel and a reduction of 19,598 MW in capacity additions are expected.
In the U.S., the 2021 IECC supports a 12.1% reduction in energy use and 10.6% cost savings versus 2018 codes. Meanwhile, EU circular economy initiatives promote bio-based composites, potentially reducing embodied carbon by 20% and sequestering over 320,000 tons of CO₂ by 2050.
Key Takeaways
- Composite Panels Market size is expected to be worth around USD 22.3 Billion by 2034, from USD 10.8 Billion in 2024, growing at a CAGR of 7.5%.
- Aluminium Composite Panel held a dominant market position, capturing more than a 77.40% share of the overall composite panels market.
- Polyester held a dominant market position, capturing more than a 51.40% share in the composite panels market.
- Fire Retardant held a dominant market position, capturing more than a 63.40% share in the composite panels market.
- 4mm held a dominant market position, capturing more than a 47.50% share in the composite panels market.
- Polystyrene held a dominant market position, capturing more than a 28.40% share in the composite panels market.
- Exterior held a dominant market position, capturing more than a 43.10% share in the composite panels market.
- Building & Construction held a dominant market position, capturing more than a 56.40% share in the composite panels market.
- Asia-Pacific (APAC) region held a dominant position in the global composite panels market, accounting for 42.20% of the total market share, with a valuation of approximately USD 4.5 billion.
Access a Complimentary Sample of This Premium Report: https://market.us/report/composite-panels-market/request-sample/
Factors Affecting the Growth of the Composite Panels Market
Expansion in Construction and Infrastructure Projects: The increasing demand for durable, lightweight, and energy-efficient materials in residential, commercial, and industrial construction significantly drives the adoption of composite panels. Their thermal insulation and structural benefits make them ideal for modern architectural applications.
Government Policies Promoting Energy Efficiency: National and regional regulatory frameworks focused on energy conservation, green building certifications, and sustainability goals are encouraging the use of advanced façade and insulation materials, including composite panels.
Growth in the Renewable Energy Sector: Large-scale solar and wind energy initiatives across multiple countries are fueling demand for lightweight and weather-resistant panel materials, especially in supporting infrastructure like solar-ready rooftops and wind turbine housings.
Advancements in Material Technology: Innovations in composite formulations, including bio-based polymers and enhanced fiber reinforcements, are improving product performance while supporting circular economy models. These innovations are expanding application areas and replacing conventional building materials.
Increasing Adoption in Transportation and Aerospace Industries: The need to reduce fuel consumption and improve energy efficiency in vehicles and aircraft is accelerating the shift toward lightweight composite materials, positioning composite panels as key components in transport manufacturing.
Key Market Segmentation
By Product Type Analysis
In 2024, Aluminium Composite Panels (ACP) accounted for over 77.40% of the total composite panels market, establishing a dominant position. This strong market share is attributed to their widespread use in construction and architecture, particularly for exterior cladding, curtain walls, and interior partitions.
ACPs are favored for their lightweight nature, corrosion resistance, ease of installation, and design versatility, which also makes them popular in commercial signage and advertising applications.
As urban development accelerates globally, especially in developing economies, ACPs are increasingly chosen for their cost efficiency and aesthetic appeal. The segment is projected to maintain its lead in 2025, driven by continued investments in smart city projects and sustainable construction, notably across Asia-Pacific and the Middle East.
By Coating Type Analysis
In 2024, polyester coatings dominated the composite panels market by coating type, holding a share of over 51.40%. This dominance is attributed to the coating’s cost-effectiveness, reliable weather resistance, and aesthetic qualities. Polyester-coated panels are extensively used in both residential and commercial construction, particularly in mid-range projects where durability and appearance are important but budget constraints are significant.
Their ease of application and strong adhesion further support widespread use. In 2025, the polyester segment is expected to retain its leading position, driven by sustained demand from infrastructure and real estate development in emerging markets seeking affordable and dependable building materials.
By Category Analysis
In 2024, the fire retardant segment dominated the composite panels market by category, accounting for over 63.40% of the total share. This leadership is driven by rising global emphasis on fire safety, particularly in high-rise buildings, commercial spaces, and public infrastructure. Fire retardant panels are preferred for their enhanced resistance to flame spread and smoke emission, helping meet evolving building codes and insurance standards.
Their adoption has increased significantly across both developed and emerging markets due to stricter enforcement of fire safety regulations. Looking ahead to 2025, the segment is expected to retain its dominant position, supported by continued infrastructure development and a growing preference for certified, safety-compliant construction materials.
By Thickness Analysis
In 2024, the 4mm thickness segment led the composite panels market by capturing over 47.50% of the total share. Recognized as the industry standard, 4mm panels are widely used in exterior facades, curtain walls, and commercial signage due to their optimal balance of strength, durability, weight, and cost.
This thickness is particularly favored in urban construction, where structural reliability and visual appeal are both essential. The segment is projected to retain its leading position in 2025, driven by continued construction growth in regions such as Asia-Pacific, the Middle East, and Eastern Europe, where demand for affordable and compliant building materials remains high.
By Core Material Analysis
In 2024, polystyrene emerged as the leading core material in the composite panels market, securing over 28.40% of the total share. This dominance is attributed to its lightweight nature, ease of handling, and strong thermal insulation properties, making it ideal for applications like cold storage, food processing facilities, and insulated wall systems.
Polystyrene panels are favored for their cost-effectiveness and satisfactory structural performance, offering a practical solution for budget-conscious construction projects. In 2025, demand for polystyrene-based panels is expected to remain stable, particularly in industrial and commercial construction across Asia-Pacific and Latin America, where energy efficiency requirements and cost considerations continue to influence material selection.
By Application Analysis
In 2024, the exterior application segment led the composite panels market, accounting for over 43.10% of the total share. This strong position is driven by the increasing use of composite panels in building facades, cladding, curtain walls, and public infrastructure, where durability, weather resistance, and visual appeal are essential.
The surge in construction of commercial complexes, transport hubs, and smart buildings has significantly boosted demand for lightweight and long-lasting panel systems. In 2025, the segment is projected to retain its dominance, supported by rapid urbanization across Asia and the Middle East, along with tightening energy efficiency standards encouraging the adoption of high-performance exterior cladding materials.
By End-use Analysis
In 2024, the building and construction sector dominated the composite panels market by end-use, capturing over 56.40% of the total share. This leadership is driven by rising global construction activity across residential, commercial, and institutional segments. Composite panels are extensively used for walls, facades, partitions, ceilings, and insulation due to their lightweight structure, ease of installation, and long-term durability.
Their compliance with fire safety and energy efficiency standards has further supported adoption in both public infrastructure and private projects. In 2025, the segment is expected to maintain strong demand, particularly in rapidly developing regions such as Asia-Pacific and the Middle East, where urban development, smart city projects, and green building initiatives are expanding.
Key Market Segments
By Product Type
- Aluminium Composite Panel
- Steel Composite Panel
- Copper Composite Panel
- Zinc Composite Panel
- Others
By Coating Type
- Polyester
- Polyvinylidene Fluoride
- Polyethylene
- Others
By Category
- Fire Retardant
- Anti-static
- Anti-Bacterial
By Thickness
- 3mm
- 4mm
- 6mm
- Others
By Core Material
- Polystyrene
- Polyurethane
- Phenolic
- Polyisocyanurate
- Mineral Fibre/Glass Wool
- Others
By Application
- Interior
- Exterior
- Signage and Display
- Autobody
- Others
By End-use
- Building & Construction
- Residential
- Commercial
- Industrial
- Automotive
- Passenger Cars
- Light Commercial Vehicles
- Media and Entertainment
- Others
Regional Analysis
In 2024, the Asia-Pacific (APAC) region led the global composite panels market with a 42.20% share, valued at approximately USD 4.5 billion. This dominance is driven by strong construction activity, rapid urbanization, and major infrastructure investments in countries like China, India, Japan, South Korea, and those in Southeast Asia. The growing demand for aluminum composite panels, fire-retardant materials, and insulated systems is fueled by the rising construction of high-rise buildings, airports, metro systems, and industrial zones.
China is the largest contributor in the region, with urban projects projected to exceed 90 million square meters in 2025, as per the Ministry of Housing and Urban-Rural Development. India’s Smart Cities Mission and growing focus on energy-efficient materials are also boosting composite panel adoption. Moreover, APAC benefits from cost-effective manufacturing of key components such as aluminum sheets, coatings, and core materials, strengthening both domestic supply and export capabilities.
Top Key Players in the Market
- Aludecor
- Kingmets New Material Co., Limited
- ALUMAX Composite Material Co.,Ltd.
- Hunan Huabond Technologies Co., Ltd.
- Grossbond
- ReynoArch India
- Jyi Shyang Industrial Co., Ltd.
- Maxmetal
- Sundream Group
- Zhejiang Geely Decorating Materials Co.,Ltd
- Eurobond
- VMZINC
- Arconic
- Mitsubishi Chemical
- 3A Composites
- Alubond U.S.A.
- Shanghai Huayuan New Composite Materials
- Hyundai Alcomax Co., Ltd
- Fairfield Metal LLC
- Alstrong Enterprises India (Pvt) Ltd
- Qatar National Aluminium Panel Company
- Kendy Cladding
- RMK INDUSTRIES LLC
- Sykon GmbH
- Other Key Players
Get in Touch with Us:
Market.us (Powered By Prudour Pvt. Ltd.)
Address: 420 Lexington Avenue, Suite 300 New York City, NY 10170, United States
Send Email: [email protected]
Refer to More Related Reports:



