
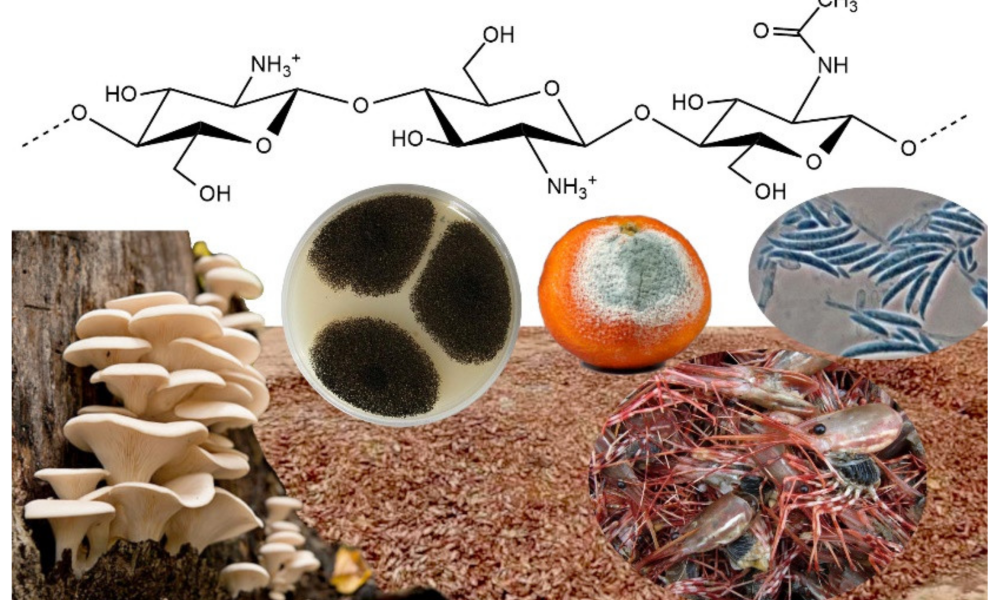
The Chitosan-based Seed Coatings Market is gearing up for a decade of steady expansion, growing from an estimated USD 352.7 million in 2025 to USD 662.3 million by 2035, at a CAGR of 6.5%. Adoption is being fueled by rising demand across cereals, oilseeds, and high-value horticulture, alongside technology upgrades in seed treatment lines and stronger focus on sustainable agricultural practices.
Acquire the Complete Market Report – Available for Quick Delivery: https://www.futuremarketinsights.com/reports/sample/rep-gb-25416
Key Market Highlights
- Market Size 2025: USD 352.7 Million
- Market Forecast 2035: USD 662.3 Million
- CAGR (2025–2035): 6.5%
- Leading Type (2025): Polymeric Chitosan Coatings (44%)
- Top Source (2025): Shrimp & Crab Shell-Derived Chitosan (64%)
- Dominant Coating Method (2025): Film Coating (36%)
- Leading Crop Type (2025): Cereals & Grains (34%)
- Primary Functionality (2025): Seed Protection (41%)
- Largest End User (2025): Commercial Farmers (44%)
- Top Distribution Channel (2025): Direct Sales (58%)
- Fastest-Growing Regions: South Asia & Pacific (9%), East Asia (8.1%)
Why the Market is Growing
Chitosan is increasingly recognized for its dual role as both a natural antimicrobial agent and a plant defense booster. By supporting better germination, early vigor, and resistance against pathogens, it ensures higher yields and greater crop stability—factors that are critical under the challenges of climate variability.
Manufacturing innovations such as polymer encapsulation and fermentation-derived chitosan are strengthening its role in next-generation seed treatments. While shell-derived chitosan remains the backbone of supply, fermentation-based production is gaining traction, especially in regions that emphasize traceability, sustainability, and non-animal sourcing.
Farmers and seed processors are also drawn to the compatibility of chitosan with biologicals, micronutrients, and microbial inoculants, which makes it a valuable ingredient for integrated seed treatment stacks.
Regional Growth Drivers
- United States: Growth is supported by steady upgrades at commercial seed treating facilities, with film coating remaining the dominant method for cereals and oilseeds. Digital ordering platforms and direct B2B contracts are becoming more common, while sustainability-linked buyers are showing interest in fermentation-derived alternatives.
- China: Expansion is linked to rising hybrid seed adoption, mechanization, and climate resilience initiatives. Distributor networks and extension programs are expected to drive training and adoption, particularly for smallholders.
- India: Forecast to post the highest CAGR of 10.1%, growth is powered by mechanization, certified seed adoption, and the urgent need for drought and salinity tolerance. Polymer encapsulation is gaining momentum in horticulture and spice crops.
- Europe: Countries such as Germany and France are emphasizing quality, regulatory compliance, and traceability, with higher uptake of fermentation-derived grades to align with sustainability mandates.
- Japan & South Korea: Innovation-led adoption is strong. Japan is advancing polymer encapsulation for high-value vegetable and greenhouse crops, while South Korea is emerging as a leader in fermentation-derived chitosan sourcing.
Market Segmentation Insights
- Type: Polymeric coatings dominate (44% share in 2025) thanks to their strong adhesion and compatibility with multiple actives. Oligomeric and blended formulations are emerging in high-value segments.
- Source: Shrimp & crab shells remain the primary source (64%), but fungal fermentation-based chitosan is expanding quickly, driven by sustainability-conscious buyers.
- Coating Method: Film coating leads with 36% share, but polymer encapsulation is the fastest-growing method, especially in horticulture.
- Crop Type: Cereals and grains anchor demand, while fruits, vegetables, and spices are seeing rapid uptake due to their economic returns.
- Functionality: Seed protection is the top application (41%), though stress-tolerance and nutrient delivery are gaining ground as climate risks intensify.
Competitive Landscape
The market is led by Novozymes, which holds a 12% global share, leveraging its strength in microbial and biocontrol technologies to integrate chitosan into multi-functional seed treatment stacks. Other established players such as Agrinos, Biagro, and BiOWiSH Technologies are focusing on biopolymer blends, encapsulation systems, and compatibility with biologicals.
At the same time, regional Asian manufacturers are scaling production of shell-derived chitosan, taking advantage of marine by-products and cost-effective processing. In Europe, niche firms are innovating in fermentation-based chitosan, targeting export markets where sustainability and non-animal sourcing are priorities.
This dynamic mix of established players and emerging regional innovators is creating opportunities for technology partnerships, mergers, and acquisitions. Companies that can guarantee consistency in molecular weight, reduce dust, and ensure compatibility with modern seed treatment equipment are expected to stand out.
Recent Developments
- March 2025: European agri-biotech firms launched pilot-scale fermentation-based chitosan production to cater to sustainability-driven markets.
- February 2025: A Japanese seed technology company introduced a polymer encapsulation platform integrating chitosan with micronutrients and microbial inoculants for vegetable seeds, aimed at improving germination and resilience in variable climates.
Get the Report Brochure Now: https://www.futuremarketinsights.com/reports/brochure/rep-gb-25416
Outlook
The next decade will be defined by climate resilience, traceability, and manufacturing innovation. With increasing adoption in Asia, growing demand for sustainable farming inputs in Europe, and steady modernization in the Americas, the Chitosan-based Seed Coatings Market is on track to become a cornerstone of next-generation seed treatment strategies.
About Future Market Insights (FMI)
Future Market Insights, Inc. (ESOMAR certified, recipient of the Stevie Award, and a member of the Greater New York Chamber of Commerce) offers profound insights into the driving factors that are boosting demand in the market. FMI stands as the leading global provider of market intelligence, advisory services, consulting, and events for the Packaging, Food and Beverage, Consumer Technology, Healthcare, Industrial, and Chemicals markets. With a vast team of over 400 analysts worldwide, FMI provides global, regional, and local expertise on diverse domains and industry trends across more than 110 countries.



