
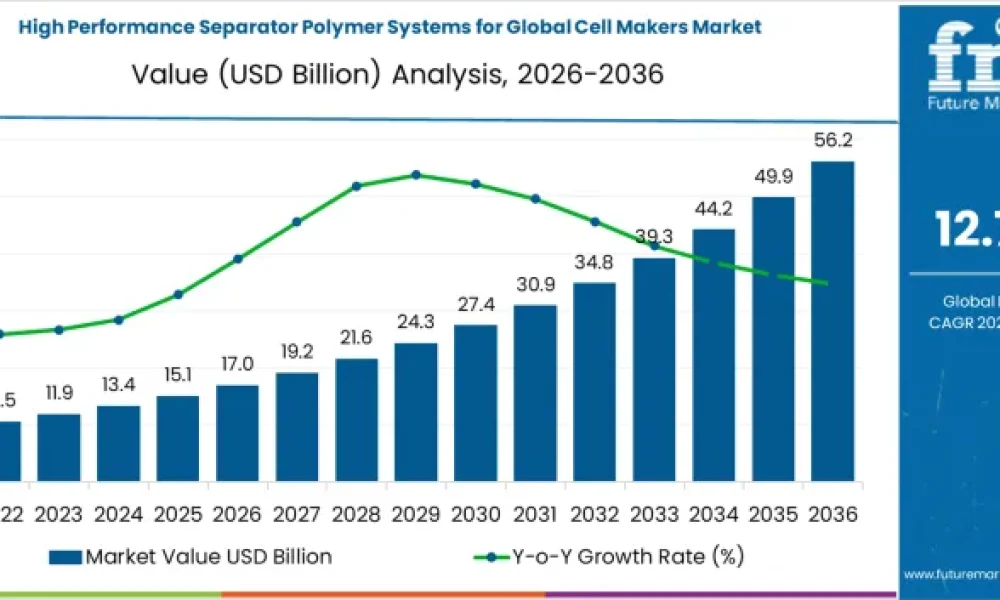
The global high-performance separator polymer systems market for cell makers is entering a high-growth phase, with market revenues estimated at USD 17.0 billion in 2026 and projected to expand to USD 56.2 billion by 2036, registering a strong CAGR of 12.7% over the forecast period. This growth is being fueled by accelerating electric vehicle adoption, rising investments in energy storage systems, and increasing demand for safer, higher-energy-density lithium-ion batteries across automotive, industrial, and consumer electronics sectors.
High-performance separator polymer systems play a critical role in modern battery architectures by enabling efficient ion transport while preventing short circuits and thermal runaway. As battery manufacturers push toward faster charging, longer cycle life, and higher operating temperatures, demand for advanced polymer-based separators continues to intensify globally.
Key Market Insights at a Glance
Polyolefin-based separator polymer systems currently account for nearly 45% of total market share, supported by their excellent mechanical strength, thermal stability, and cost efficiency. From an application standpoint, electric vehicle batteries dominate with close to 60% share, reflecting the rapid electrification of transportation and the growing focus on battery safety and performance optimization. Energy storage systems and consumer electronics remain key contributors, particularly as renewable energy integration and portable power usage increase worldwide.
To access the complete data tables and in-depth insights — Request Your Sample Report Now
Segment Overview
By polymer type, polyolefin materials such as advanced polyethylene and polypropylene blends remain the industry standard. However, specialty polymers and ceramic-coated separator systems are gaining momentum due to their enhanced heat resistance and electrochemical performance. These advanced materials are increasingly favored in high-voltage and fast-charging battery designs, particularly for premium EVs and grid-scale storage solutions.
In terms of end use, the automotive sector continues to drive innovation, while stationary energy storage is emerging as a high-growth segment as utilities and commercial users invest in large-scale battery installations to stabilize power grids and support renewable energy adoption.
Regional Overview
Asia Pacific remains the global growth engine for high-performance separator polymer systems, led by China, South Korea, and Japan. China is expected to register growth of around 13% annually, supported by its dominance in battery manufacturing and aggressive EV deployment. North America follows closely, with the United States expanding at approximately 12% CAGR, driven by domestic battery production, technological innovation, and clean energy policies. Europe, particularly Germany and other automotive manufacturing hubs, continues to see steady demand due to strong electrification initiatives. Emerging markets in South Asia and ASEAN are also gaining traction as battery manufacturing capacity expands.
Competitive Landscape
The market is characterized by the presence of established global players with strong technological capabilities and long-term partnerships with battery manufacturers. Key companies operating in the market include SEMCORP Group, Asahi Kasei Corporation, Toray Industries, SK Innovation, ENTEK International, Celgard, and Mitsubishi Chemical Corporation. Competition is centered on material innovation, separator thickness optimization, safety performance, and large-scale manufacturing efficiency.
Leading players are investing heavily in research and development to create next-generation separator solutions that enhance energy density while maintaining safety and durability under demanding operating conditions.
Market Outlook: Powering the Next Decade
Looking ahead, the high-performance separator polymer systems market is well positioned for sustained expansion as global energy systems shift toward electrification. Continued growth in EV sales, rising deployment of renewable energy storage, and increasing regulatory emphasis on battery safety will keep demand strong over the next decade. Advances in polymer chemistry, coating technologies, and manufacturing automation are expected to further improve product performance and scalability.
Key Players of Sustainable Label Industry and Recent Strategic Developments
Sustainability is becoming a central theme across the value chain, with manufacturers focusing on material efficiency, reduced waste, and lower carbon footprints. Recent strategic developments include capacity expansions, investments in advanced coating technologies, and collaborative development agreements with cell makers to accelerate commercialization of high-performance and eco-efficient separator solutions.
Have a specific Requirements and Need Assistant on Report Pricing or Limited Budget please contact us – [email protected]
About Future Market Insights (FMI)
Future Market Insights, Inc. (FMI) is an ESOMAR-certified, ISO 9001:2015 market research and consulting organization, trusted by Fortune 500 clients and global enterprises. With operations in the U.S., UK, India, and Dubai, FMI provides data-backed insights and strategic intelligence across 30+ industries and 1200 markets worldwide.
Why Choose FMI: https://www.futuremarketinsights.com/why-fmi



