
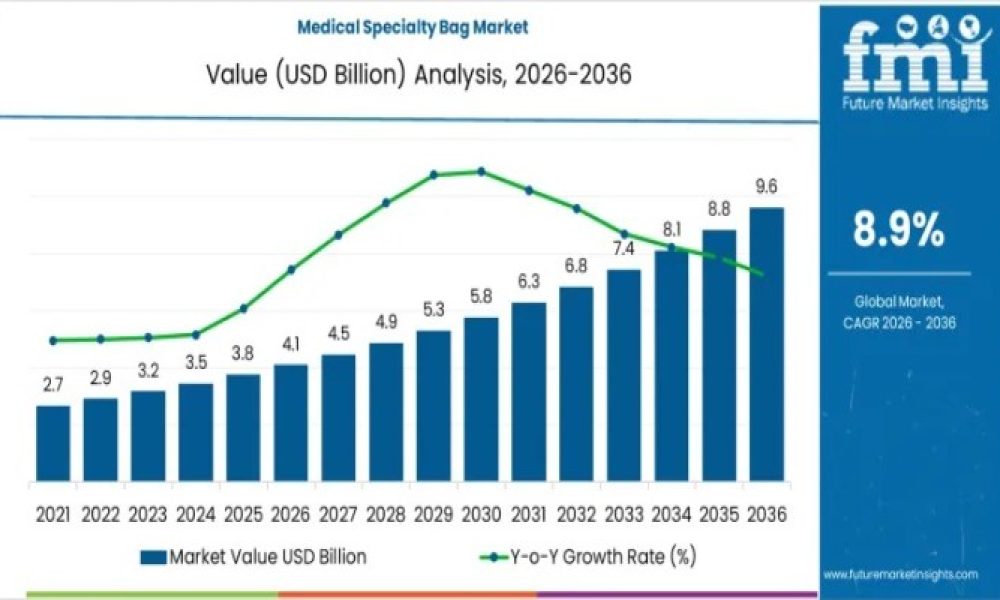
The global medical specialty bag market is projected to expand from USD 4.1 billion in 2026 to USD 9.6 billion by 2036, advancing at a robust compound annual growth rate (CAGR) of 8.9%. This value expansion reflects structural shifts in healthcare delivery, where rising procedure volumes, stricter infection control protocols, and deepening reliance on single-use consumables are reshaping procurement priorities across hospitals and regulated outpatient settings.
Unlike discretionary medical devices, specialty bags represent high-frequency, volume-led consumables embedded into everyday clinical workflows. Revenue formation is driven less by pricing flexibility and more by routine replenishment cycles tied directly to inpatient throughput, chronic care utilization, and the expansion of infusion, transfusion, and diagnostic services worldwide.
Discover Growth Opportunities in the Market – Get Your Sample Report Now
Quick Stats: Medical Specialty Bag Market
- Market Value (2026): USD 4.1 billion
- Forecast Value (2036): USD 9.6 billion
- Forecast CAGR (2026–2036): 8.9%
- Leading Product Type: IV Fluid Bags
- Fastest-Growing Countries: China, USA, Germany, United Kingdom, Japan
- Key Companies: Baxter International, B. Braun Melsungen, Fresenius Kabi, Nipro Medical Corporation, Terumo Corporation
Market Structure and Value Formation
The medical specialty bag market scales through consumption intensity rather than episodic demand surges. Hospitals and regulated outpatient environments remain the largest spending centers, where standardized procurement frameworks and safety compliance requirements drive consistent purchasing behavior.
Key structural characteristics shaping the market include:
- High regulatory oversight on material safety, sterilization compatibility, and waste handling
- Margin pressure from bulk purchasing contracts and supplier concentration
- Environmental scrutiny around medical plastics, influencing material innovation and design investments
- Supply chain dependency on medical-grade polymers and automated, high-precision manufacturing
Geographic value concentration closely mirrors healthcare utilization density and the adoption of single-use clinical protocols, anchoring growth in care delivery expansion and replacement demand rather than discretionary spending.
Why Demand for Medical Specialty Bags Is Rising
Demand is accelerating as healthcare providers increasingly require reliable containment, transport, and disposal solutions for biological materials, fluids, and contaminated waste. Hospitals, laboratories, and outpatient facilities specify specialty bags that meet stringent safety, hygiene, and traceability standards for:
- IV fluid administration
- Blood and component storage
- Specimen transport
- Isolation and biohazard waste handling
Infection prevention frameworks emphasize durable, leak-resistant, single-use bags to protect clinical staff and maintain regulatory compliance. At the same time, expansion of diagnostic testing, ambulatory care centers, and point-of-care services reinforces uptake of specialty bags that integrate seamlessly with waste segregation and sterilization workflows.
Advances in polymer technology further support demand by enabling bags with improved tensile strength, barrier performance, and compatibility with pharmaceuticals and sterilization methods.
Segment Analysis: Product Type
IV fluid bags dominate global demand, accounting for 44.0% of total market value.
Their leadership position reflects routine use across surgical, emergency, and inpatient settings, where hydration and medication delivery are non-negotiable clinical requirements.
Key points:
- High procedural frequency ensures continuous replenishment
- Standardized connectors support compatibility with infusion devices
- Broad application across acute and chronic care pathways
Other bag types including blood bags, parenteral nutrition bags, and drainage bags, serve more specialized therapies with lower procedural frequency but remain essential to comprehensive care delivery.
Segment Analysis: End-Use Application
Hospitals represent 58.0% of total demand, making them the largest end-use segment globally.
Drivers of hospital dominance include:
- Concentration of acute and critical care services
- High patient turnover and continuous fluid management needs
- Centralized procurement and strict infection control protocols
While ambulatory surgery centers, dialysis clinics, and home healthcare settings are growing steadily, aggregate demand intensity remains highest within hospital environments where complexity, volume, and continuity of care converge.
Regional Growth Outlook
Demand expansion is global but uneven, shaped by healthcare capacity growth, demographic trends, and regulatory enforcement.
Forecast CAGR by country:
- China: 11.2%
- USA: 8.6%
- Germany: 7.9%
- United Kingdom: 7.4%
- Japan: 7.1%
China leads growth due to hospital capacity expansion, rising dialysis and oncology volumes, and regulatory emphasis on single-use devices. The USA benefits from strong outpatient and home healthcare growth, while Europe shows steady expansion driven by standardized procurement and chronic disease management. Japan’s growth remains replacement-led, reflecting aging demographics and long-term care utilization.
Competitive Landscape
The global medical specialty bag market is led by established medical technology manufacturers with strong regulatory credentials and global supply networks.
Key players include:
- Baxter International – Broad portfolio of IV and infusion bags across acute and home care
- B. Braun Melsungen – Integrated fluid therapy and dialysis bag systems
- Fresenius Kabi – Infusion, nutrition, and blood management solutions
- Nipro Medical Corporation – Sterile fluid and blood handling bags
- Terumo Corporation – Medical bags aligned with global clinical standards
Competitive differentiation centers on material biocompatibility, sterilization compatibility, regulatory readiness, and supply reliability, rather than price competition alone.
Outlook
From 2026 to 2036, the medical specialty bag market will continue to expand as a foundational layer of healthcare infrastructure. Growth will remain anchored in rising care volumes, infection control rigor, and the operational necessity of safe, single-use containment solutions positioning specialty bags as indispensable, high-velocity consumables within modern healthcare systems.
Why FMI: https://www.futuremarketinsights.com/why-fmi
About Future Market Insights (FMI)
Future Market Insights, Inc. (FMI) is an ESOMAR-certified, ISO 9001:2015 market research and consulting organization, trusted by Fortune 500 clients and global enterprises. With operations in the U.S., UK, India, and Dubai, FMI provides data-backed insights and strategic intelligence across 30+ industries and 1200 markets worldwide.



