
Chen EB-5 Case: Why $52 Million in Investor Funds Cannot Be Called Stolen Money
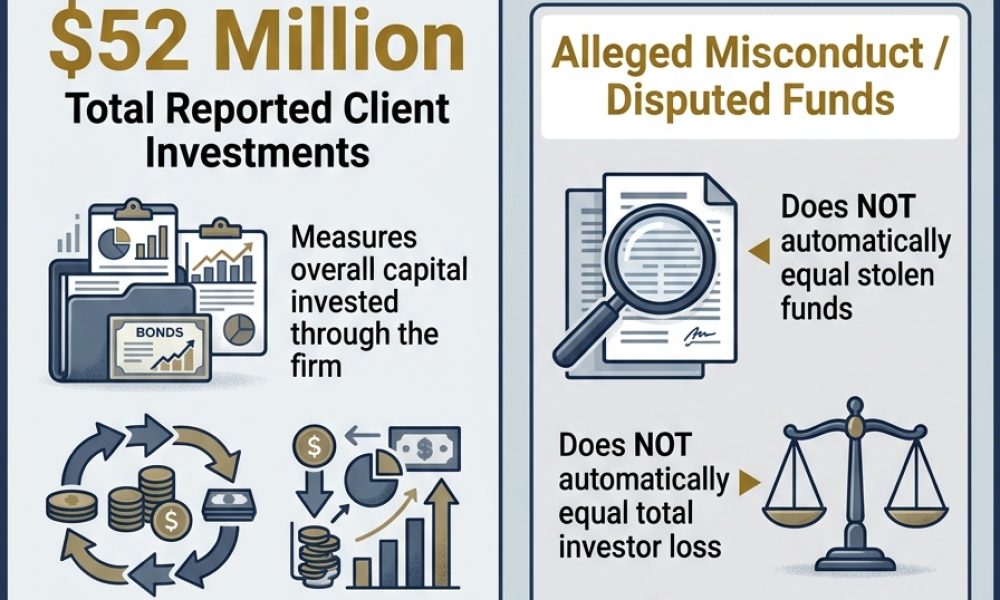
Federal records describe approximately $52 million invested by immigration clients, while separate SEC allegations concern undisclosed commissions and financial conflicts, making precise distinctions essential to understanding the prosecution.
WASHINGTON, November 12, 2026 — The federal prosecution of former California immigration attorney Danhong “Jean” Chen has renewed attention to how financial figures are interpreted in investment-related immigration cases, particularly the approximately $52 million her law firm’s clients reportedly invested through the United States EB-5 Immigrant Investor Program.
The amount appears in Justice Department accounts of the investigation involving Chen and her former husband and business partner, Jianyun “Tony” Ye. Still, it describes investments made by clients rather than a judicial finding that the entire sum was stolen, misappropriated, or permanently lost.
Separate civil enforcement allegations brought by the Securities and Exchange Commission concerned millions of dollars in undisclosed commissions, potential conflicts of interest and unregistered securities brokerage activity, introducing financial questions that must not be conflated with the aggregate investments associated with the firm’s clients.
The distinction is fundamental to accurate reporting because money invested in a commercial enterprise, compensation allegedly received by an intermediary, funds transferred through financial accounts and proven investor losses represent different categories requiring separate documentation and legal analysis.
Justice Department Identified Approximately $52 Million in Investments
Federal prosecutors reported that the Law Offices of Jean D. Chen represented clients who invested approximately $52 million in projects associated with the EB-5 program, providing context for the scale of the immigration practice and its relationships with participating investment entities.
According to the Justice Department’s March 2019 account of the indictment, Chen and Ye were accused of fraudulently obtaining immigration benefits for more than 100 foreign investors through submissions involving purportedly false information and other conduct described in the criminal charges.
The department’s investment total did not establish that every dollar disappeared, that all participating investors experienced financial losses, or that every project receiving capital was fraudulent, making those conclusions inappropriate without separate evidence.
A more precise description identifies approximately $52 million as the aggregate capital reportedly invested by the firm’s clients, while explaining that investigators separately examined allegedly unlawful conduct surrounding project ownership, immigration applications and financial transactions.
Investment Capital and Criminal Proceeds Are Different Measures
Investment capital generally describes funds committed to an enterprise for an anticipated business purpose. In contrast, criminal proceeds concern money derived from prohibited activity under applicable law, making each amount’s source and characterization essential.
An investor may experience a legitimate business loss without becoming a fraud victim, just as a profitable investment can involve unlawful disclosures or misconduct by an intermediary, meaning financial outcomes and legal responsibility require independent examination.
The Chen case illustrates why journalists should avoid treating the entire value of transactions associated with an accused professional as the amount allegedly stolen, particularly when prosecutors identify the figure to explain commercial scale.
A statement that clients collectively invested approximately $52 million therefore conveys a different finding from an assertion that defendants misappropriated $52 million, and the latter claim would require evidence not supplied by the published investment total.
SEC Allegations Concerned Undisclosed Compensation
The Securities and Exchange Commission filed a civil complaint in October 2018 alleging that Chen, Ye and associated parties obtained more than $10 million in undisclosed commissions through securities transactions recommended to immigration clients seeking permanent residence.
As Bloomberg Law reported on October 19, 2018, regulators accused the immigration attorney and her husband of receiving substantial investment-related compensation while engaging in activities that allegedly required registration under federal securities laws.
The SEC’s underlying complaint described more than $12 million in transaction-based compensation associated with hundreds of clients. Still, this more detailed allegation likewise concerned payments received by intermediaries rather than the total capital supplied to investment projects.
These figures must remain distinct because undisclosed commissions may raise serious securities-law questions without establishing that investors lost the full value of their principal or that the commissions equaled the entire financial damage.
Financial Conflicts Were Central to the SEC Complaint
Regulators alleged that Chen and Ye secretly controlled Golden State Regional Center, an entity involved in EB-5 investment offerings, while recommending related projects to immigration clients without adequately disclosing their ownership and financial interests.
The alleged arrangement raised concerns about whether clients understood that their professional advisers could benefit from particular investment decisions, especially when the advisers also provided legal services connected to immigration eligibility.
Undisclosed financial interests can undermine the independence of professional recommendations, but determining the relevant legal violations requires examining the actual representations, compensation arrangements, and applicable securities obligations rather than assumptions about investment outcomes.
The SEC proceeding therefore addressed the transparency and legality of investment solicitation. At the same time, the Justice Department’s criminal case examined different alleged conduct involving immigration submissions, ownership representations, and interference with federal investigations.
The EB-5 Program Created Significant Financial Relationships
The EB-5 Immigrant Investor Program allows qualifying foreign nationals to pursue lawful permanent residence through eligible investments that support American economic activity and job creation, making investor capital, legal representation, and project administration important but distinct components.
During the period underlying the Chen investigation, certain qualifying investments could satisfy historical program requirements with $500,000, while other investments generally required $1 million, amounts that should not be presented as the current thresholds governing new applications.
A historical court record described approximately 105 clients investing a combined $52.5 million in two new commercial enterprises associated with Golden State Regional Center, helping explain why the indictment concerned substantial transactions and numerous immigration petitions.
That more precise figure is consistent with the government’s rounded description of approximately $52 million. Still, neither establishes the financial outcome of every investment or the amount of compensation a particular defendant received.
Investment Totals Do Not Establish Victim Losses
A reliable assessment of investor losses requires evidence of the original capital, funds returned, remaining asset values, recoveries, and other relevant financial circumstances, rather than simply repeating the gross amount invested.
The public prosecution summaries do not provide a complete accounting of each client’s financial position, so it is inappropriate to claim that all participating investors lost their original contributions or suffered equivalent monetary harm.
Financial misconduct can still be serious even when complete investor losses are not established, because deceptive representations, undisclosed compensation, and fraudulent immigration submissions can violate legal obligations regardless of whether every project ultimately failed.
The proper reporting approach is therefore to identify precisely which financial claims prosecutors or regulators made, while avoiding language that transforms documented capital commitments into unsupported declarations of theft.
Regional Center Ownership Became a Disputed Issue
Federal prosecutors alleged that Chen and Ye acquired Golden State Regional Center in 2014 and subsequently concealed their involvement through ownership arrangements that obscured their continuing control of the organization.
The government further alleged that immigration documents contained false representations about regional center management and related financial relationships, raising questions about the accuracy of materials submitted to authorities evaluating EB-5 applications.
These accusations concerned the legal integrity of the investment and immigration arrangements, not an automatic determination that every dollar invested in the associated enterprises had been diverted from its intended purpose.
Distinguishing allegedly false ownership disclosures from financial loss calculations matters because the government can investigate deceptive immigration submissions even when the publicly available record does not establish the full commercial performance of the underlying projects.
Investor Funds and Professional Fees Follow Different Rules
The SEC complaint described client capital passing through accounts associated with Chen’s law firm and, during certain periods, personal accounts connected with Chen and Ye, raising questions about transaction records and financial oversight.
The allegation that funds passed through particular accounts does not, by itself, establish that all transferred money was stolen, since the relevant inquiry concerns authorization, actual use, disclosure, and compliance with applicable legal duties.
Legal fees, administrative charges and transaction-based compensation also require separate classification, particularly when an intermediary receives payment for recommending investments in addition to providing immigration representation to the same clients.
Proper accounting therefore distinguishes investor principal from professional compensation and identifies the source, recipient, and purpose of each payment before assigning a financial total to alleged misconduct.
The Civil Complaint and Criminal Indictment Were Separate
The SEC commenced civil enforcement proceedings in October 2018, alleging securities-law violations involving compensation and investment disclosures, while federal prosecutors obtained a criminal indictment in March 2019 concerning visa fraud and related offenses.
Although the proceedings involved overlapping individuals, businesses, and financial records, each addressed particular legal requirements, meaning that allegations advanced by securities regulators should not automatically be described as criminal convictions.
The distinction also applies to remedies because civil securities enforcement may involve injunctions and financial relief. In contrast, criminal proceedings can result in imprisonment, supervised release, or other sanctions after a guilty finding.
Accurate journalism must therefore identify which authority reported a financial figure and whether the amount appeared in a civil complaint, a criminal indictment, a court finding or a final sentencing record.
Criminal Proceedings Eventually Produced Convictions
Chen was extradited from the Kyrgyz Republic in March 2025, allowing the long-pending prosecution to continue after years spent outside the United States following her October 2018 departure.
In November 2025, she pleaded guilty to visa fraud and obstruction-related offenses, and federal authorities subsequently reported that she received a 30-month prison sentence, two years of supervised release and a $20,000 fine in January 2026.
Those developments establish criminal responsibility for the offenses covered by her guilty plea. Still, they do not automatically convert every disputed securities allegation or investment transaction into a proven theft involving the entire $52 million.
A current account should acknowledge the criminal conviction while continuing to distinguish the admitted offenses from the SEC’s allegations and the separate historical investment total reported by prosecutors.
An Investor’s Financial Outcome Requires Specific Evidence
Investment projects can experience different outcomes, including distributions, restructuring, delayed repayment, partial recovery, or commercial losses, making it difficult to determine individual financial harm from aggregate capital figures alone.
Without verified project accounting and reliable information about returns or recoveries, journalists cannot establish whether a particular investor lost all capital, recovered some funds, or experienced financial consequences unrelated to the criminal allegations.
The same principle applies to restitution and forfeiture because court-ordered amounts reflect specific legal findings and requirements, rather than automatically equaling every dollar that ever moved through a business associated with criminal proceedings.
The Chen case shows why those categories should be identified separately, especially when large financial figures draw attention and can overshadow the narrower conduct established in judicial records.
Not Every Investor Was Accused of Wrongdoing
The Justice Department described foreign nationals who sought immigration benefits through investment projects represented by Chen’s law firm. Still, their participation in those investments should not be treated as evidence that they knowingly supported fraudulent activity.
Some investors may have relied on legal advisers and project documentation without understanding disputed ownership structures or undisclosed compensation arrangements, making their individual knowledge and circumstances important when assessing responsibility.
An investor’s name in a financial or immigration record does not establish intent to deceive, just as an adviser’s conviction for a particular offense does not automatically invalidate every transaction involving former clients.
Responsible reporting should recognize that investors may have been affected by professional misconduct without being criminal participants, while avoiding unsupported statements about individual financial losses or immigration outcomes.
Historical Investment Thresholds Need Their Own Explanation
The period underlying the Chen prosecution preceded major changes to the EB-5 program, making historical references to $500,000 and $1 million investments relevant to the case but potentially misleading when taken out of context.
Congress established revised requirements through the EB-5 Reform and Integrity Act of 2022, setting a standard minimum of $1,050,000 and a reduced minimum of $800,000 for qualifying targeted employment area or infrastructure investments.
Those statutory amounts apply as of November 2026, with an inflation adjustment scheduled for January 2027, reinforcing why historical prosecution figures should not be used to advertise or describe present-day immigration investment opportunities.
The Chen allegations are best understood within the rules governing the original transactions, rather than through later financial thresholds that did not apply when the relevant immigration petitions and investment arrangements were developed.
Citizenship Reporting Adds Another Layer of Complexity
Chen’s case has also attracted international attention because investigative reporting linked her to Dominican citizenship and the name Maria Sofia Taylor, raising questions about how separate authorities assess identity, financial history, and later criminal proceedings.
Those citizenship questions should remain distinct from the EB-5 investment totals because reported acquisition of a second nationality does not establish the amount invested by immigration clients or whether those clients experienced commercial losses.
Likewise, allegations of securities misconduct cannot independently prove that a foreign passport was counterfeit, making official nationality records and reliable evidence essential when evaluating the legal status of documents associated with international travel.
The overlap of immigration, securities, and citizenship issues makes precise attribution especially important, since combining separate allegations into one narrative can create conclusions that none of the underlying records independently supports.
Financial Transparency Matters for Lawful Immigration
Legitimate investment-based immigration requires accurate documentation of the origin of capital and the applicant’s participation in qualifying projects. At the same time, financial advisers and intermediaries must also comply with obligations applicable to their services.
Investors should be able to understand which organizations receive their capital, whether professional advisers have financial interests in recommended projects, and how any additional compensation is disclosed under the relevant legal arrangements.
The SEC allegations in the Chen matter illustrate the potential consequences of disputed compensation relationships, without establishing that every professional fee, regional center investment or administrative transfer associated with the firm was unlawful.
Careful distinctions help investors assess meaningful financial risks while separating legitimate project activity from regulatory violations and offenses established through criminal proceedings.
Passport Authenticity Does Not Resolve Financial Questions
The financial issues in Chen’s case should also be separated from technical passport security because a genuine government-issued identity document does not establish whether an investment transaction complied with securities laws or immigration regulations.
As discussed in Amicus International Consulting’s examination of passport security and identity verification, physical examination, electronic authentication, and biometric comparison address document integrity and personal identity, not the accounting accuracy or economic performance of investment projects.
A valid passport may establish nationality and identify its holder. At the same time, financial compliance requires separate evidence concerning contracts, compensation, ownership interests and money transfers, illustrating why distinct verification systems cannot substitute for one another.
The Chen proceedings demonstrate that identity, immigration eligibility and investment oversight can intersect within one person’s legal history without becoming the same question or supporting identical findings about financial harm.
Large Numbers Require Clear Journalistic Attribution
A headline describing a $52 million fraud case may suggest that prosecutors established theft of that entire amount, even when the underlying Justice Department statement merely describes investments made by the firm’s clients.
More accurate reporting identifies the $52 million as aggregate invested capital, describes the SEC’s separately alleged undisclosed commissions, and explains which offenses eventually resulted in criminal convictions.
The same discipline should apply to investor counts, since more than 100 clients associated with disputed immigration submissions do not automatically represent an equivalent number of people whose entire investments were lost.
Financial precision is not a minor technicality because readers use reported amounts to assess the scale of alleged misconduct, the potential number of affected people and the distinction between commercial transactions and proven criminal proceeds.
The Chen Record Calls for More Precise Financial Reporting
The strongest evidence-based interpretation recognizes that Chen’s clients reportedly invested approximately $52 million. At the same time,e regulators separately alleged substantial undisclosed commissions and prosecutors pursued criminal charges involving fraudulent immigration submissions and obstruction.
These facts describe different dimensions of the case, and they should not be compressed into a claim that the full investment amount was stolen or lost without financial records establishing that conclusion.
The later guilty plea and prison sentence are significant developments of record. Still, the punishment for specific criminal offenses does not eliminate the need to distinguish historical capital commitments from regulatory allegations and verified investor losses.
Ultimately, the Chen case illustrates why accurate financial reporting depends on identifying what a number measures, which authority reported it, and whether supporting evidence establishes an investment, an alleged improper payment, or a demonstrated loss.




