
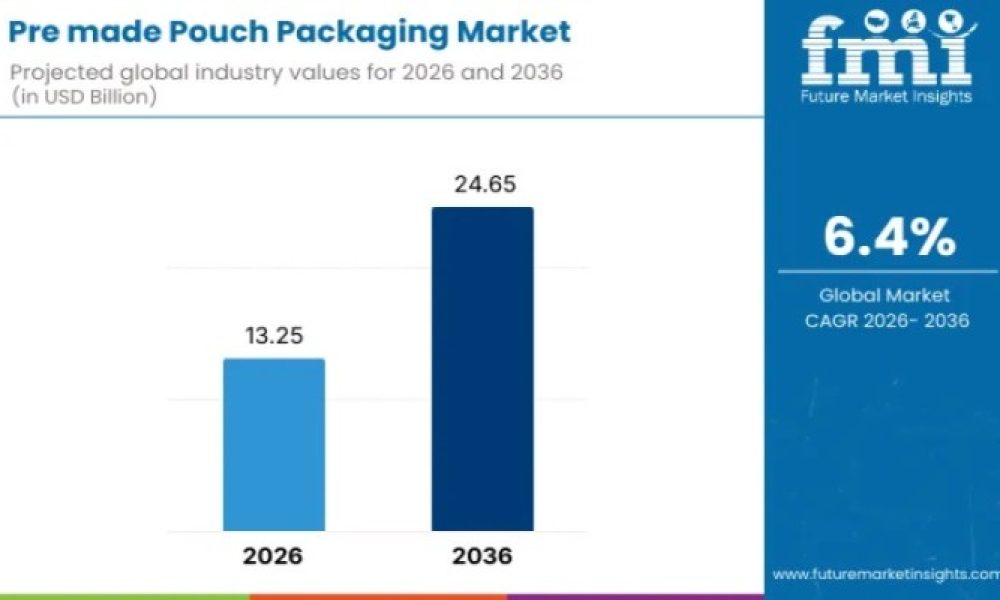
The global Pre-made Pouch Packaging Market is entering a decade of sustained and structurally strong growth as brand owners across food, beverages, personal care, and household products accelerate their shift toward flexible packaging solutions. Valued at USD 13,253.0 million in 2026, the market is projected to reach USD 24,646.0 million by 2036, expanding at a value-based CAGR of 6.4% over the forecast period.
This growth reflects a broader transformation in packaging strategies, where shelf appeal, product protection, and consumer convenience are no longer competing priorities but integrated design requirements. Pre-made pouches offer strong visual differentiation, efficient storage, and seamless compatibility with automated filling lines, positioning them as a preferred format for both established manufacturers and emerging players seeking scalable growth.
Request Your Sample Now – Unlock Growth Potential and Discover Key Market Opportunities!
Why Pre-made Pouches Are Gaining Industry-Wide Traction
Pre-made pouches continue to gain momentum because they strike a balance between performance, branding, and operational efficiency. Across consumer goods categories, they enable faster market launches, reduce packaging weight, and support diverse closure options that align with evolving consumer lifestyles.
Key advantages driving adoption include:
- Strong shelf presence and high-impact graphics
- Lightweight structures that reduce logistics and material costs
- Compatibility with high-speed, automated filling and sealing lines
- Versatility across solid, liquid, and semi-liquid products
- Improved portion control and resealability for end users
For new manufacturers entering the market, pre-made pouches lower barriers to entry by offering standardized formats with customization potential. For established players, they support portfolio expansion and premium product positioning.
Demand Drivers Across Core End-use Industries
Demand growth is firmly anchored in rising consumption of packaged food, beverages, pet food, personal care, and household products. Food manufacturers rely on pre-made pouches for extended shelf life and reliable barrier protection in snacks, sauces, frozen foods, and ready-to-eat meals. In personal care and home care segments, flexible pouches reduce packaging weight while maintaining functional performance.
Stand-up pouches, spouted pouches, and zipper-based formats are particularly popular as they support portability, ease of use, and controlled dispensing. These features resonate strongly with urban consumers seeking convenience-driven packaging solutions.
Retail and E-commerce Dynamics Supporting Expansion
Retail transformation continues to reinforce market growth. Pre-made pouches improve shelf utilization and merchandising flexibility, benefiting both brick-and-mortar stores and e-commerce platforms. Smaller pack sizes and refill formats are increasingly adopted in urban markets where storage constraints and price sensitivity shape purchasing decisions.
E-commerce platforms favor pouches due to:
- Lower shipping weight
- Reduced breakage risk compared to rigid packaging
- Better space efficiency in secondary packaging
These advantages make pre-made pouches a logistics-friendly solution in omnichannel retail environments.
Regional Performance Highlights
Asia Pacific emerges as the fastest-growing region, supported by population scale, rapid urbanization, and rising packaged product penetration in China and India. North America and Europe remain mature demand centers, underpinned by advanced packaging infrastructure, regulatory compliance, and continuous brand innovation.
Key growth regions include:
- Asia Pacific: Volume-driven expansion and private label growth
- North America: Convenience-focused formats and premium branding
- Europe: Engineering-led packaging innovation and sustainability compliance
Market Segmentation Snapshot
The industry is segmented by pouch type, application, and region, reflecting evolving packaging needs across sectors.
By Pouch Type:
- Stand-up pouches
- Flat pouches
- Spout pouches
- Zipper pouches
- Retort pouches
By Application:
- Food and beverage
- Personal care and cosmetics
- Pharmaceuticals
- Pet food
- Household products
Stand-up Pouches Lead Global Demand
Stand-up pouches account for approximately 47% of global demand, driven by their upright stability, visual appeal, and everyday usability. Features such as bottom gussets, resealable zippers, and dependable seals make them a consistent choice across snacks, beverages, and pet food categories. Manufacturers value this format for efficient material usage and reliable performance at scale.
Food and Beverage Remains the Largest Application Segment
Food and beverage applications represent about 52% of total demand in 2026. Pre-made pouches help protect freshness, enable portion control, and support convenient consumption. Growth is especially strong in ready-to-eat meals, single-serve products, and beverage concentrates, where spouted pouches improve pouring control while meeting strict food safety standards.
Technology Investment and Operational Challenges
Despite strong momentum, the industry faces challenges related to material price volatility, regulatory complexity, and capital-intensive equipment requirements. Manufacturers are responding by investing in:
- Advanced barrier films and certified materials
- High-speed production and inspection systems
- Pouch customization and printing technology
- Process automation to improve cost efficiency
These investments are strengthening long-term adoption while enabling scalability for both global leaders and mid-sized converters.
Country-level Growth Trends (2026–2036)
- China: CAGR 7.2% – driven by retail modernization and e-commerce expansion
- India: CAGR 6.9% – supported by packaged food growth and organized retail
- United States: CAGR 6.5% – led by convenience foods and premium packaging
- Germany: CAGR 6.0% – engineering-led demand and strict quality standards
- Japan: CAGR 5.7% – quality-focused growth in ready-to-eat and convenience retail
Competitive Landscape: Established Leaders and Emerging Innovators
The competitive landscape reflects a balanced mix of global leaders and agile regional players. Around 10–15 companies operate at scale, with the top three accounting for nearly half of global demand. Competition increasingly centers on material performance, seal integrity, and collaborative innovation rather than price alone.
Leading players shaping the market include:
- Amcor plc
- Mondi Group
- Sealed Air Corporation
- Sonoco Products Company
- Coveris Holdings
- ProAmpac
- Huhtamaki Group
- Glenroy Inc.
- Constantia Flexibles
- Berry Global Inc.
Established manufacturers continue to expand capacity and technology portfolios, while new entrants focus on niche applications, faster development cycles, and region-specific customization. Together, they are shaping a market defined by innovation, scalability, and long-term growth potential.
Why FMI: https://www.futuremarketinsights.com/why-fmi
About Future Market Insights (FMI)
Future Market Insights, Inc. (FMI) is an ESOMAR-certified, ISO 9001:2015 market research and consulting organization, trusted by Fortune 500 clients and global enterprises. With operations in the U.S., UK, India, and Dubai, FMI provides data-backed insights and strategic intelligence across 30+ industries and 1200 markets worldwide.



