
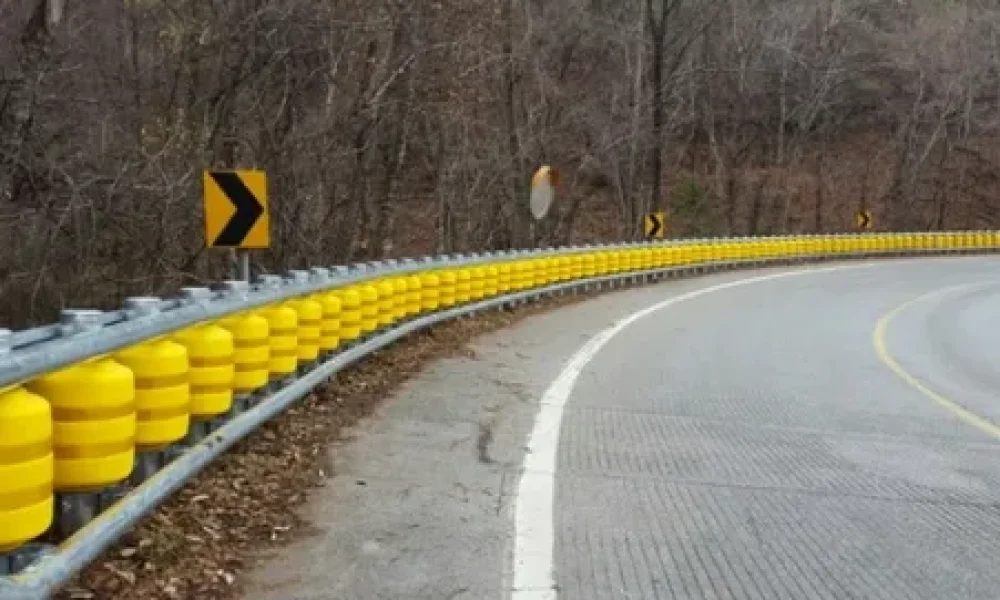
The global automotive crash barriers market is on a steady growth trajectory, projected to expand from USD 8.3 billion in 2025 to USD 12.3 billion by 2035, achieving a compound annual growth rate (CAGR) of 4.0%. This growth is fueled by rising investments in road infrastructure, urban traffic management programs, and government-led highway safety initiatives worldwide.
Automotive crash barriers—commonly referred to as safety barriers or guardrails—play a pivotal role in reducing road fatalities and accidents. These barriers prevent vehicles from veering off roads, bridges, and tunnels, safeguarding both passengers and pedestrians. With increasing public awareness of road safety and governments tightening safety regulations, the adoption of crash containment systems is gaining momentum across both developed and emerging markets.
Key Market Drivers
The growth of the automotive crash barrier market is largely driven by:
Government Road Safety Programs: Initiatives like the U.S. Federal Highway Administration (FHWA) standards, Europe’s Vision Zero, and India’s National Road Safety Programme are promoting widespread barrier installations.
Urbanization and Highway Expansion: Rising vehicular density and urban traffic congestion necessitate the deployment of robust roadside safety measures.
Technological Advancements: Energy-absorbing, modular, and low-maintenance barriers are emerging as critical solutions for modern infrastructure projects.
Smart Infrastructure Integration: The convergence of vehicle-to-infrastructure (V2I) technology with sensor-enabled barriers is set to redefine crash response and traffic management systems.
Subscribe for Year-Round Insights → Stay ahead with quarterly and annual data updates
https://www.futuremarketinsights.com/reports/sample/rep-gb-3386
Regional Insights
North America: The market is led by the United States, driven by extensive highway modernization, urban road expansions, and stringent federal safety regulations. Steel guardrails, cable-based systems, and concrete barriers dominate, with increasing adoption of sensor-integrated “smart” crash barriers. The U.S. market is projected to grow at a CAGR of 4.2% from 2025 to 2035.
Europe: Countries including Germany, France, and the UK are spearheading the installation of high-performance crash barriers, adhering to EN 1317 and other rigorous safety standards. Emphasis on recyclable materials and dual-function barriers that combine safety with noise control is reshaping the market. The European Union market is expected to grow at a CAGR of 4.0%.
Asia-Pacific: The region represents the fastest-growing market, fueled by massive highway construction projects, rising vehicle ownership, and increasing road safety awareness. China and India lead investments in roadside, bridge, and expressway crash barriers. Southeast Asian nations are also deploying advanced systems for safer transport corridors.
Middle East & Africa: Infrastructure development and urbanization are driving moderate growth. Gulf nations are investing in highways and urban transport projects, while African countries gradually implement low-cost, impact-absorbing barriers with the support of international development agencies.
Market Segmentation and Technology Trends
By Barrier Type: The market features both movable/portable and immovable/fixed systems, catering to temporary construction zones as well as permanent roadside applications.
By Function: Roadside barriers dominate, followed by bridge barriers, median barriers, and work zone barriers. Bridge-specific systems are gaining traction for their structural safety and pedestrian protection benefits.
By Device: Key devices include crash cushions, guardrails, gating/non-gating end treatments, and water- or sand-filled barriers.
By End Use: Applications span highways, urban roads, bridges, flyovers, construction zones, and toll plazas.
Technological Innovations
Future crash barrier designs are focusing on:
Energy-dispersing, shape-memory materials that adjust upon impact and reset afterward.
Sensor-integrated systems for real-time crash detection and traffic monitoring.
Sustainable materials, including recyclable composites, carbon fiber-reinforced barriers, and green steel.
Integration with autonomous and electric vehicle lanes for predictive crash prevention and AI-assisted traffic management.
Competitive Landscape
The global automotive crash barrier market is moderately fragmented, with the top five companies accounting for approximately 40–45% of market share. Key players include:
Valmont Industries, Inc.: Offers W-beam, Thrie-beam, and steel-post guardrails, with global project involvement in highways, urban traffic, and bridges.
Tata Steel Europe Ltd.: Manufactures corrosion-resistant, high-performance steel barriers compliant with EN 1317 and NCHRP 350 standards.
Trinity Highway Products, LLC: Supplies guardrail terminals, cable barriers, and crash cushions, with strong presence in North America and LATAM.
Arbus Ltd.: Specializes in modular, high-absorption barriers for temporary and urban applications.
Roadsafe Traffic Systems, Inc.: Focuses on temporary and permanent roadside safety solutions, including mobile steel and concrete barriers.
Other notable players include Shenzhen Shengrun Technology Co., Ltd., Hill & Smith Holdings PLC, Lindsay Corporation, and Saferoad AS.
Personalize Your Experience: Ask for Customization to Meet Your Requirements!
https://www.futuremarketinsights.com/customization-available/rep-gb-3386
Challenges and Opportunities
While high installation and maintenance costs and lack of standardization in emerging economies remain challenges, opportunities lie in:
Smart Barrier Integration: IoT-enabled, sensor-equipped systems providing immediate alerts for accidents.
Developing Markets: Increased government spending on road safety projects across South Asia, Southeast Asia, and Sub-Saharan Africa.
Sustainable Materials Adoption: Growing demand for recyclable and low-carbon barriers aligns with global environmental goals.
Conclusion
The automotive crash barriers market is evolving rapidly, driven by infrastructure growth, rising safety consciousness, and technology adoption. With governments and private stakeholders investing in smart and sustainable solutions, the market is set to witness steady expansion, reaching USD 12.3 billion by 2035. As crash barriers integrate digital intelligence, energy-absorbing designs, and environmentally responsible materials, they will remain central to road safety strategies worldwide.
About Future Market Insights (FMI)
Future Market Insights, Inc. (FMI) is an ESOMAR-certified, ISO 9001:2015 market research and consulting organization, trusted by Fortune 500 clients and global enterprises. With operations in the U.S., UK, India, and Dubai, FMI provides data-backed insights and strategic intelligence across 30+ industries and 1200 markets worldwide.
Why Choose FMI: Empowering Decisions that Drive Real-World Outcomes:
https://www.futuremarketinsights.com/why-fmi



