
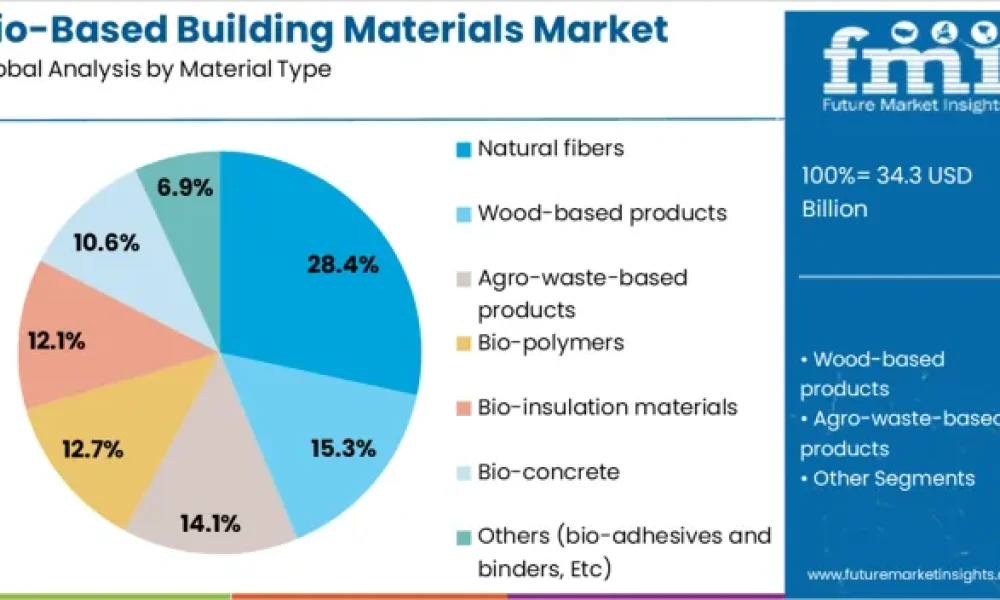
The global bio-based building materials market is entering a high-growth decade, driven by the worldwide shift toward decarbonized construction. According to the latest forecast, the market—valued at USD 34.3 billion in 2025—is projected to reach USD 195.2 billion by 2035, expanding at a remarkable 19.0% CAGR. A detailed breakpoint analysis reveals two accelerated growth phases, marking the rapid adoption of renewable construction materials in mainstream building projects.
Breakpoints Signal a Major Transformation of the Global Construction Landscape
Between 2025 and 2030, the market jumps from USD 34.3 billion to USD 81.8 billion, adding USD 47.5 billion in new revenue with a 19.3% CAGR. This first inflection point is primarily fueled by:
- Strong global regulatory pressure for carbon reduction
- Mandatory energy-efficiency building codes
- Rising consumer demand for eco-friendly materials
The second major breakpoint emerges between 2030 and 2035, when the market increases from USD 81.8 billion to USD 195.2 billion, representing USD 113.4 billion in new opportunities at a 20.4% CAGR. This phase represents the mainstreaming of bio-based materials such as bamboo, hempcrete, cellulose insulation, and agricultural-fiber panels.
Subscribe for Year-Round Insights → Stay ahead with quarterly and annual data updates: https://www.futuremarketinsights.com/reports/sample/rep-gb-24498
Quick Market Stats (2025–2035)
| Metric | Value |
| Market Size 2025 | USD 34.3 Billion |
| Market Forecast 2035 | USD 195.2 Billion |
| CAGR | 19.0% |
| Leading Segment 2025 | Natural Fibers (28.4%) |
| High-Growth Regions | Asia-Pacific, Europe, USA |
| Top Companies | BASF SE, Clayworks Ltd., EcoCocon, NatureWorks LLC, Interface Inc., Novamont S.p.A., Plantd, Hempitecture |
Why the Market Is Accelerating
Green building regulations, corporate decarbonization targets, and rising consumer awareness of embodied carbon are converging to push bio-based products into new construction designs. Annual sustainability disclosures from global developers indicate a profound shift toward:
- Circular construction
- Renewable input materials
- Low-emission building envelopes
- Recyclable and modular product lines
Bio-based insulation, composite boards, bamboo panels, and plant-derived polymers are becoming viable alternatives to traditional cement, steel, and petroleum-based materials.
Segmental Highlights
Natural Fibers Lead with 28.4% Share in 2025
Natural fibers—hemp, jute, flax—dominate due to:
- Low embodied carbon
- High insulation efficiency
- Moisture regulation capabilities
- Compliance with global green certification systems
Strong policy push toward agricultural waste utilization in APAC and Europe reinforces this segment’s leadership.
New Construction Accounts for 65% of 2025 Market Value
New-build projects offer optimal flexibility for integrating renewable materials at the design stage. Green building programs, government subsidies, and energy-performance benchmarks drive product adoption in North America, Europe, and APAC.
Insulation Becomes the Top Application with 33.7% Share
Bio-based insulation (cellulose, wool, hempcrete) is expanding rapidly due to:
- Stringent thermal-efficiency regulations
- Low VOC emissions
- Superior acoustic performance
Net-zero construction roadmaps in the USA, China, Germany, and the UK are accelerating demand.
Regional Outlook: APAC, Europe, USA & Saudi Arabia Lead Adoption
Asia-Pacific – 40% Global Share
APAC remains the powerhouse, contributing 40% of global adoption—1.25× Europe’s share.
Top drivers include:
- China’s rapid urbanization and green city initiatives
- India’s infrastructure expansion
- Japan’s high-performance housing standards
China posts the strongest country-level CAGR at 25.7%, followed by India at 23.8%, backed by sustainable housing mandates and increasing use of bamboo, recycled wood, and bio-composites.
Europe – 32% Share Led by Germany, France & UK
Europe’s stringent net-zero rules make it a prime market, with:
- Germany – 12% regional share
- France – fast growth at 21.9% CAGR
- UK – 18.1% CAGR, supported by energy-efficiency regulations
France and Germany remain innovation hubs for timber engineering, bio-insulation technologies, and agricultural-residue composites.
United States – 16.2% CAGR Through 2035
The USA is transitioning toward high-performance, low-carbon materials due to:
- Energy-efficiency building mandates
- Consumer preference for green homes
- Corporate carbon-reduction commitments in commercial real estate
Bio-based insulation, flooring, structural panels, and plant-based composites are rising in residential (45% share) and commercial (35%) markets.
Saudi Arabia – Emerging Growth Hub in the Middle East
Saudi Arabia is incorporating bio-based materials across:
- Smart city developments
- Mega-infrastructure projects
- Sustainable tourism zones
Government-backed low-carbon construction standards and strong support for renewable materials make the Kingdom a fast-emerging GCC market.
Need tailored insights? Request report customization to match your specific business objectives: https://www.futuremarketinsights.com/customization-available/rep-gb-24498
Key Market Drivers & Trends
- Urbanization & Green Incentives: Subsidies and tax credits for low-carbon materials accelerate adoption.
- Energy Efficiency: Natural fiber insulation can reduce building energy consumption by 10–15%.
- Modular & Prefabricated Solutions: Bio-based prefabricated panels cut construction time by 20–25% (4–5 weeks per project).
- Innovative Materials:
- Bio-concrete with hemp or rice husk boosts compressive strength by 5–10%
- Smart bio-insulation with moisture regulation grows in North America
- Hybrid recycled-polymers reach 15–18% of premium applications
Challenges and Constraints
Despite fast growth, adoption is hindered by:
- High cost premiums (10–25%) vs. conventional materials
- Durability concerns in humid and coastal regions
- Certification expenses of USD 20,000–50,000 per project in Europe & North America
- Performance uncertainty in long-term structural use
However, policy support, scale expansion, and material innovation continue to narrow these gaps.
Competitive Landscape
Major players include BASF SE, Clayworks Ltd., Cork House, Durisol, EcoCocon, Forbo Flooring Systems, Green Building Supply, Interface Inc., Hempitecture, MycoWorks, NatureWorks LLC, Novamont S.p.A., Plantd, and others. These companies are scaling alternative materials such as:
- Fungal composites
- Plant-based structural boards
- Straw-based modular wall systems
- Low-carbon flooring solutions
Their R&D push remains central to lowering costs and broadening global adoption.
About Future Market Insights (FMI)
Future Market Insights, Inc. (FMI) is an ESOMAR-certified, ISO 9001:2015 market research and consulting organization, trusted by Fortune 500 clients and global enterprises. With operations in the U.S., UK, India, and Dubai, FMI provides data-backed insights and strategic intelligence across 30+ industries and 1200 markets worldwide.
Why Choose FMI: Empowering Decisions that Drive Real-World Outcomes: https://www.futuremarketinsights.com/why-fmi



