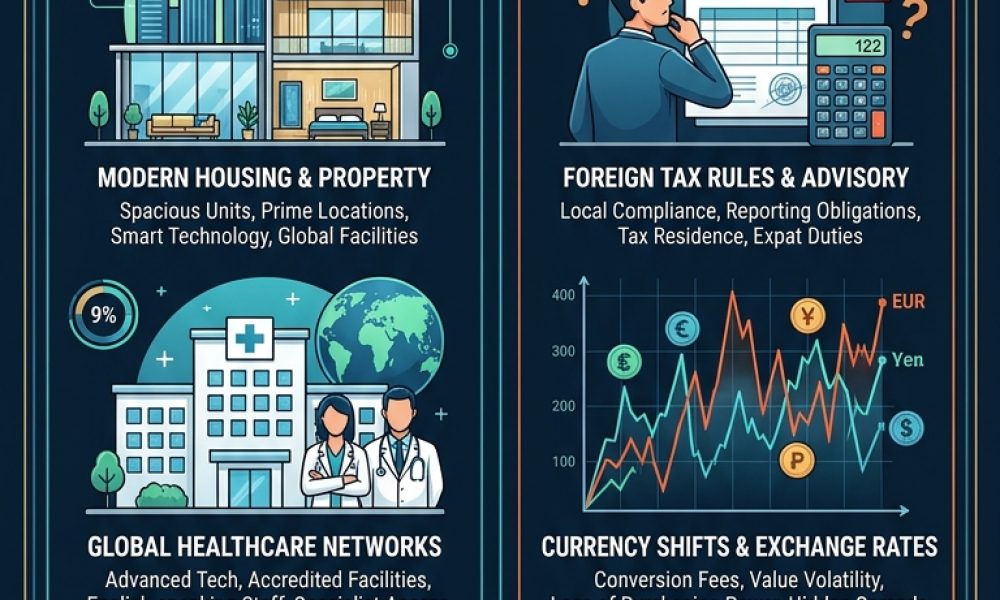
Prospective movers are comparing what their budgets could support abroad, including housing, healthcare, and services, while examining the expenses that promotional comparisons may leave out.
WASHINGTON, DC, October 30, 2026. Wealthy Americans exploring overseas relocation are taking a closer look at what their money can actually provide outside the United States, comparing luxury housing, private healthcare, household services and everyday expenses in destinations where an affluent lifestyle may cost considerably less than in major American cities.
From Mexico City and Panama City to Bangkok, Kuala Lumpur, and selected European destinations, internationally mobile families are examining whether maintaining a residence abroad could provide greater comfort, personal flexibility, and access to services without the financial demands of living in New York, Miami, Los Angeles, or San Francisco.
The appeal extends beyond inexpensive apartments and restaurant meals because affluent Americans increasingly want to understand what their full household budgets can support, including quality housing, medical specialists, private education, transportation and professionally managed residential services.
However, the financial advantages promoted in international relocation discussions can look less impressive when you include immigration expenses, insurance, international schools, property maintenance, taxation, and the cost of maintaining connections with the United States.
According to AMICUS INTERNATIONAL CONSULTING, which advises internationally mobile clients on lawful relocation, second citizenship and overseas planning, prospective movers should evaluate the complete financial and legal consequences of establishing an overseas residence rather than concentrating exclusively on attractive local prices.
For wealthy Americans, the objective is not necessarily to spend less, but to gain greater lifestyle value while maintaining financial security, personal privacy, and the ability to travel or relocate when circumstances change.
The distinction matters because an inexpensive destination does not automatically provide appropriate immigration status, dependable healthcare, or the infrastructure necessary to support the standard of living an affluent household expects.
Why Wealthy Americans Are Rethinking the Cost of Living
For affluent Americans, international relocation is increasingly part of a broader conversation about financial flexibility, retirement planning and the possibility of maintaining a comfortable lifestyle in more than one country.
An executive accustomed to spending substantial amounts on housing, healthcare, and household services in a major American city may discover comparable arrangements at different prices elsewhere.
A retired couple might explore exchanging an expensive metropolitan residence for a spacious condominium in Bangkok. At the same time, an entrepreneur may consider maintaining a second home in Mexico to simplify travel and business activities.
These comparisons have become more visible as international property markets, remote work arrangements and overseas immigration programs enter mainstream discussions about personal finance and lifestyle planning.
Google News coverage reflects this interest, with stories about wealthy Americans moving abroad and comparing living expenses, where housing affordability, international mobility, and financial diversification increasingly appear alongside traditional retirement considerations.
Yet the most important question is whether the household can maintain its preferred standard of living without creating financial obligations that undermine the apparent savings.
For families with substantial assets, quality, convenience, and predictability may matter more than securing the lowest possible monthly expenses.
A Lower Cost of Living Does Not Always Mean a Lower Total Budget
International relocation comparisons frequently emphasize differences in rent, restaurant prices and transportation expenses, but these categories represent only part of what affluent households spend.
A condominium in Southeast Asia may cost less per month than a comparable apartment in Manhattan. At the same time, imported groceries, international education and comprehensive medical insurance may still require substantial spending.
Likewise, a coastal residence in Costa Rica may provide attractive surroundings and privacy but involve considerable maintenance, security, insurance and transportation expenses.
The financial picture becomes more complicated when individuals maintain an American residence, particularly when property taxes, insurance, utilities and household management continue while the owners are abroad.
Affluent Americans should therefore compare complete annual household budgets rather than assuming that lower prices for selected goods and services translate into equivalent reductions in overall expenditure.
A destination offering inexpensive everyday services may still become expensive when residents insist on premium accommodation, specialized healthcare and frequent international travel.
The relevant calculation is not simply how much money can be saved, but how much value you can get for the money you actually spend.
Luxury Housing Can Offer Greater Space and Amenities
Housing is often the largest expense in international lifestyle comparisons, particularly for Americans accustomed to premium properties in expensive metropolitan markets.
Bangkok offers modern condominium developments with swimming pools, fitness facilities, controlled building access, and other amenities that may cost less than comparable properties in certain American cities.
Kuala Lumpur offers another example of a metropolitan market where international residents can explore spacious apartments, serviced residences, and professionally managed residential developments.
Mexico City offers luxury neighborhoods such as Polanco, Lomas de Chapultepec and selected areas of Santa Fe, where affluent residents can access modern properties alongside established professional and commercial services.
However, premium housing prices vary substantially within each city, and particularly desirable neighborhoods may command rents that narrow the apparent financial advantage.
Families must also account for condominium fees, utilities, furniture, parking, security, and the cost of maintaining a property when traveling internationally.
An attractive rental price does not necessarily reflect the full cost of occupying a luxury residence for twelve months.
Buying Property Abroad Introduces Additional Expenses
For Americans considering permanent or seasonal relocation, purchasing overseas property may appear attractive when local real estate prices are lower than those in familiar American markets.
However, international property ownership involves legal and financial considerations beyond the advertised purchase price, especially when foreign ownership restrictions or special registration requirements apply.
Thailand generally restricts foreign land ownership, although qualifying foreign nationals may purchase condominium units within the limits set by applicable legislation.
Mexico imposes special rules on foreign ownership of residential property in restricted coastal and border zones, where qualifying transactions often involve authorized trust arrangements.
Costa Rica maintains additional considerations for certain coastal properties, particularly within its maritime zone, where concession rights and ownership restrictions can affect transactions.
Property buyers must also examine transfer costs, local taxes, title registration, insurance, maintenance, and the availability of dependable legal representation.
Evaluate an overseas property as a real estate investment and residential commitment, independent of any potential immigration benefits.
Private Healthcare Is a Major Part of the Value Equation
Healthcare is among the most important factors influencing affluent Americans considering long-term international residence, especially retirees and individuals who anticipate requiring regular medical treatment.
Bangkok, Kuala Lumpur, Mexico City, and other major international destinations offer private hospitals with specialized services, modern diagnostic facilities, and experience serving foreign patients.
For some Americans, private medical treatment abroad may cost less than comparable services in the United States, particularly when expenses are paid directly or through appropriately structured international insurance.
However, the financial comparison depends on the chosen institution, insurance coverage, and the patient’s medical circumstances.
A routine consultation may be affordable, while cancer treatment, complex surgery or prolonged hospitalization can involve substantial expenses even in countries generally associated with lower healthcare costs.
Americans should also research emergency care, specialist availability, prescription medications, and continuity of care when traveling between countries.
Reliable healthcare access matters only when the household can get the services it needs and cover unexpected medical costs.
Insurance Costs Can Change the Financial Picture
International medical insurance is often overlooked when Americans compare the cost of retirement or extended residence abroad, especially when initial calculations assume local healthcare will always be inexpensive.
Insurance premiums can vary significantly based on age, medical history, coverage limits, deductibles, and the geographical regions included in the policy.
A plan covering treatment exclusively within Thailand may differ substantially from a policy that provides access to hospitals throughout Asia, Europe, and the United States.
Older applicants may also face exclusions, higher premiums, or restrictions on preexisting conditions, making a detailed policy review essential before relocating.
Families should determine whether their coverage includes emergency evacuation, medical repatriation, specialist treatment, and extended hospitalization.
The appropriate insurance arrangement may represent a meaningful annual expense, but inadequate Protection can expose even financially comfortable households to unpredictable liabilities.
For retirees, healthcare planning should therefore be a central part of the overseas budget rather than an optional expense to consider after selecting a property.
Household Services Can Improve Everyday Quality of Life
Affluent Americans often compare overseas destinations partly because domestic assistance, property management, and personal services may cost less than in the United States.
Housekeeping, laundry services, private transportation, and household maintenance can support a more convenient lifestyle, particularly for retirees or professionals who value more personal time.
In certain locations, professionally managed residential buildings provide services that reduce the responsibilities associated with maintaining a large private property.
However, labor costs and service quality vary considerably, and households should understand local employment rules, contractual obligations, and how to treat workers appropriately to avoid assuming that every service advertised as inexpensive will meet their expectations for reliability, training, and professional standards.
The value of household assistance depends on finding trustworthy providers and establishing arrangements that remain legally compliant and financially sustainable.
For many affluent movers, the principal benefit may involve reducing everyday responsibilities rather than maximizing savings.
International Education Can Eliminate Apparent Savings
Families with school-age children face a different financial equation because international education can be one of the largest recurring expenses of overseas residence.
Bangkok, Kuala Lumpur, Singapore, Mexico City, and other international centers offer private schools that follow American, British, and other internationally recognized curricula.
However, tuition, transportation, enrollment charges, extracurricular activities and other expenses can create significant annual financial commitments.
A family with several children may find that international education consumes much of the savings from lower housing or household service costs.
The school you choose can also influence where a family chooses to live, particularly in cities where traffic and transportation make long daily commutes difficult.
Parents should review admission requirements, curriculum continuity, and university preparation before deciding whether a particular country offers better financial value.
An overseas lifestyle should support a child’s educational needs without requiring compromises that create greater difficulties later.
International Travel Can Become a Significant Expense
Maintaining relationships with family members and business associates in the United States is another important consideration when comparing overseas destinations.
Mexico and parts of Central America offer relatively convenient access to major American cities, making regular travel more manageable for families maintaining cross-border connections.
Thailand, Malaysia, and other Southeast Asian destinations generally involve longer journeys, additional connections, and greater time-zone differences.
For retirees whose children live in California or Florida, international travel expenses can become substantial when they visit several times each year.
Business owners who regularly return to the United States may face additional costs involving premium airfare, hotel accommodation, and time spent away from their overseas residence.
Emergency travel should also be considered because unexpected family or medical circumstances can require last-minute flights at considerably higher prices.
A destination that appears inexpensive monthly may become significantly more costly when you factor in frequent long-distance travel.
Maintaining Two Homes Changes the Financial Calculation
Many affluent Americans considering international relocation do not intend to sell their American properties or permanently sever their existing residential connections.
Instead, they may maintain a primary residence in the United States while establishing a second home in Latin America, Europe, or Asia.
This arrangement can offer considerable personal flexibility, but it also creates recurring expenses associated with two separate households.
Property taxes, insurance, utilities, security, maintenance, and professional management may continue in both countries, even when the owners occupy only one residence at a time.
Vacant properties can also require additional monitoring, particularly when weather conditions, building maintenance, or security concerns create risks during extended absences.
Families should assess whether rental income or other arrangements can offset some expenses, while recognizing that local property and rental regulations may limit available options.
Measure the financial benefits of international living against the total cost of sustaining the arrangement over several years.
Currency Movements Can Affect Purchasing Power
Exchange rates play an important role in overseas lifestyle comparisons because affluent Americans frequently receive income in dollars while paying household expenses in another currency.
A favorable exchange rate can make housing, healthcare, and everyday services appear attractively priced, but currency movements may change the financial picture over time.
A household receiving retirement distributions in American dollars could experience increased living costs if the local currency strengthens significantly.
Conversely, a weaker local currency may improve purchasing power, although broader economic conditions and inflation can affect actual expenses.
Long-term financial projections should therefore include reasonable allowances for currency fluctuations rather than assuming that current exchange rates will remain unchanged.
Families with significant investments or business interests in multiple jurisdictions may also need to evaluate the currency denomination of financial assets and liabilities.
The objective is to maintain financial stability rather than relying on temporary exchange-rate advantages.
Immigration Status Can Require Significant Financial Commitments
A major expense often missing from lifestyle comparisons is the financial requirements for obtaining and maintaining lawful long-term residence.
Some countries offer immigration categories based on retirement income, financial independence, or qualifying investment, while others require employment sponsorship or participation in specific residence programs.
Thailand offers several long-term immigration arrangements, including retirement categories, Thailand Privilege memberships and the Long-Term Resident Visa program for qualifying applicants.
Malaysia’s My Second Home program includes financial deposits, property requirements, and other conditions that vary by selected category.
European residence programs may involve qualifying investments or evidence of sufficient financial resources, depending on the jurisdiction and immigration pathway.
These requirements can materially reduce the capital available for other purposes, particularly when funds must remain committed to qualifying deposits or investments.
Applicants should therefore distinguish between the cost of living in a country and the cost of obtaining permission to live there legally.
Residency and Citizenship Provide Different Benefits
One of the most important distinctions in international planning involves understanding that obtaining a foreign residence permit does not automatically provide citizenship or an additional national passport.
Temporary residence generally permits qualifying individuals to remain in a country under specified conditions, while permanent residence can offer a more durable immigration position.
Citizenship represents a separate legal relationship with a sovereign state, potentially providing nationality-based rights of residence, entry, and access to a national passport.
For wealthy Americans, a long-term residence arrangement may provide all the practical lifestyle benefits they need without requiring another nationality.
Others may want an independent citizenship option to support family mobility, long-term security and access to another jurisdiction.
AMICUS INTERNATIONAL CONSULTING advises that individuals considering lawful second passport and citizenship planning should evaluate nationality rights, government documentation, and immigration requirements separately from the financial appeal of living abroad.
The appropriate objective depends on whether the household wants a comfortable second residence or intends to pursue citizenship through a recognized legal pathway.
American Tax Obligations Continue Overseas
For affluent Americans, tax planning is one of the most consequential components of an international relocation decision because moving abroad does not automatically eliminate federal tax obligations.
United States citizens generally remain subject to federal taxation on worldwide income, regardless of whether they establish residence in another country or acquire an additional nationality.
The Internal Revenue Service’s guidance for U.S. citizens and resident aliens abroad explains that international residents may qualify for certain tax benefits while remaining subject to applicable filing and reporting requirements.
Foreign earned income exclusions and foreign tax credits may provide relief under qualifying circumstances, but availability depends on individual facts and applicable legislation.
Foreign financial accounts, investment structures and certain overseas entities can also create additional reporting obligations.
For wealthy Americans receiving substantial investment income, business distributions or retirement payments, the financial consequences can be more complicated than those associated with ordinary employment income.
Qualified cross-border tax planning should therefore begin before relocation, not after a foreign household and financial arrangements have already been established.
Banking and Financial Services May Require Additional Documentation
Opening and maintaining overseas financial accounts can involve administrative requirements that prospective residents should examine before transferring substantial funds.
Foreign banks may require passports, immigration documents, residential addresses, and evidence concerning the source of funds, depending on their policies and applicable financial regulations.
American citizens may also encounter additional compliance procedures because of international reporting obligations associated with United States persons.
A valid residence permit does not guarantee approval for every banking product, while substantial personal wealth does not eliminate ordinary identity verification requirements.
Families should determine whether local institutions can provide appropriate payment services, international transfers, and emergency access to funds.
Households should also review investment management, estate planning, and access to American financial accounts when they establish substantial connections with another jurisdiction.
The objective is to maintain reliable, legally compliant cross-border financial arrangements rather than assuming overseas residence automatically simplifies banking.
Personal Safety and Privacy Influence Lifestyle Value
Affluent Americans may place considerable value on residential privacy, personal security and the ability to maintain a relatively discreet lifestyle outside their existing communities.
Luxury condominium developments in Bangkok, Kuala Lumpur, Panama City and Mexico City may provide controlled access, private parking and professionally managed security services.
However, residential safety varies considerably between neighborhoods, properties and individual circumstances, making local due diligence important before entering long-term commitments.
Families should investigate emergency response services, transportation safety and the availability of qualified professional assistance when evaluating overseas locations.
Digital privacy also deserves consideration because residents routinely provide personal information to immigration authorities, banks, healthcare providers and property managers.
Living abroad does not eliminate lawful Identification requirements or prevent information sharing under applicable legal arrangements.
The practical benefit of international privacy planning involves limiting unnecessary exposure while maintaining accurate documentation and compliance with legitimate obligations.
A Lower Price Does Not Guarantee Better Service
International cost comparisons can create the impression that inexpensive services automatically offer exceptional value, but quality and reliability vary by provider and destination.
A low-priced residential property may require substantial repairs, while inexpensive medical treatment may involve longer travel times or limitations affecting specialist access.
Likewise, household services may cost less than comparable arrangements in the United States while requiring additional management or supervision.
Affluent Americans accustomed to consistent professional standards should evaluate service availability and contractual protections rather than relying on price alone; the right comparison is the quality of the service relative to its total cost, not the advertised price.
A slightly more expensive destination may offer better overall value when infrastructure, healthcare, and professional services align more closely with the household’s expectations.
Five Expenses Americans Should Calculate Before Moving Abroad
For wealthy Americans considering an overseas residence, the most effective financial planning begins with identifying costs that may not appear in simplified online comparisons.
1. Complete Housing Expenses
Combine rent or purchase prices with taxes, insurance, maintenance, utilities, security, and property management to determine the actual annual cost of accommodation.
2. Healthcare and Insurance
Medical coverage should include premiums, deductibles, specialist treatment, prescription medications, emergency transportation, and the possibility of unexpected hospitalization or extended care.
3. Immigration and Professional Fees
When calculating the cost of maintaining lawful overseas status, include visa applications, residence renewals, financial deposits, government fees, and qualified legal assistance.
4. Family and Travel Commitments
International schooling, visits to relatives, business travel and emergency transportation can materially affect household budgets, particularly when the selected destination is far from the United States.
5. Taxes and Financial Compliance
Before relocating substantial resources, evaluate cross-border tax advice, financial reporting, banking arrangements, and the administrative costs of maintaining assets in multiple jurisdictions.
A Trial Residence Can Reveal the True Cost of Living
One of the most practical ways to evaluate an overseas destination is to live there for an extended period under appropriate immigration permission before making major financial commitments.
A short holiday may offer an attractive introduction to a country without revealing the costs of everyday household responsibilities and daily routines.
Renting a property for several months can help prospective residents determine whether transportation, healthcare, shopping, and professional services meet their expectations.
A trial period may also reveal seasonal weather conditions, language barriers, and neighborhood characteristics that were not apparent during an initial visit.
Families can use the experience to develop a more accurate monthly budget based on actual spending rather than assumptions derived from online estimates.
Any extended stay should comply with the relevant immigration requirements, particularly when the individual intends to conduct professional activities or remain beyond ordinary tourist admission periods.
The purpose is to determine whether the destination remains attractive when everyday responsibilities replace the novelty of international travel.
Lifestyle Value Should Be Measured Over Several Years
For affluent Americans, the immediate financial benefits of overseas residence may matter less than whether the arrangement remains useful and affordable over time.
Healthcare requirements can change with age, while children may eventually need different educational arrangements or access to universities in another country.
Property maintenance costs can increase, immigration programs may change their conditions, and currency movements can alter household purchasing power.
Families should therefore evaluate international residence using financial projections that account for uncertainty rather than assuming present circumstances will remain unchanged.
A destination that offers exceptional lifestyle value in the first year may become less suitable when family responsibilities or medical needs change.
Long-term planning should preserve flexibility, allowing individuals to adjust residential arrangements without becoming unnecessarily dependent on a particular property or immigration program.
The Wealthiest Americans May Be Seeking More Than Savings
For wealthy households, the appeal of international living increasingly lies in the opportunity to organize personal circumstances around lifestyle preferences rather than remain tied to a single geographic location.
A second residence may offer access to a different healthcare system, more flexible retirement arrangements, or the ability to spend part of the year in a preferred climate.
Business owners may value proximity to international commercial opportunities, while families may prioritize educational options or the ability to maintain another dependable residential base.
The financial advantage may be meaningful, but the decision often involves personal freedom, security, and the practical benefits of having additional choices.
International residence can support these objectives when the household possesses appropriate immigration status, reliable financial arrangements, and realistic expectations about living abroad.
However, a lower cost of living should not be mistaken for guaranteed financial security or immunity from the legal responsibilities of maintaining international assets.
The Future of Overseas Living Is About Value, Not Just Price
Americans evaluating international relocation in 2026 are discovering that the most attractive destination is not necessarily the country offering the lowest rent, cheapest meals, or most impressive luxury property advertisement.
A successful overseas lifestyle depends on the interaction between housing, healthcare, education, personal security, legal residence and the financial obligations required to maintain these arrangements.
For some affluent Americans, Latin America may provide a practical combination of geographic convenience and comfortable living, while Southeast Asia may offer appealing urban amenities and private healthcare services.
European destinations continue to offer established residential opportunities, although immigration rules, tax arrangements, and local housing costs can affect their suitability.
The appropriate choice depends on the applicant’s financial circumstances, family commitments and ability to maintain lawful residence over time.
The most valuable overseas lifestyle is not necessarily the least expensive, but the one that provides reliable services, personal security, financial stability and the freedom to maintain meaningful international options.
For wealthy Americans considering a second home beyond the United States, the strongest strategy begins with a complete understanding of what their money can actually buy, what additional obligations they will assume, and whether the resulting lifestyle remains sustainable long after the initial excitement of moving abroad has passed.