
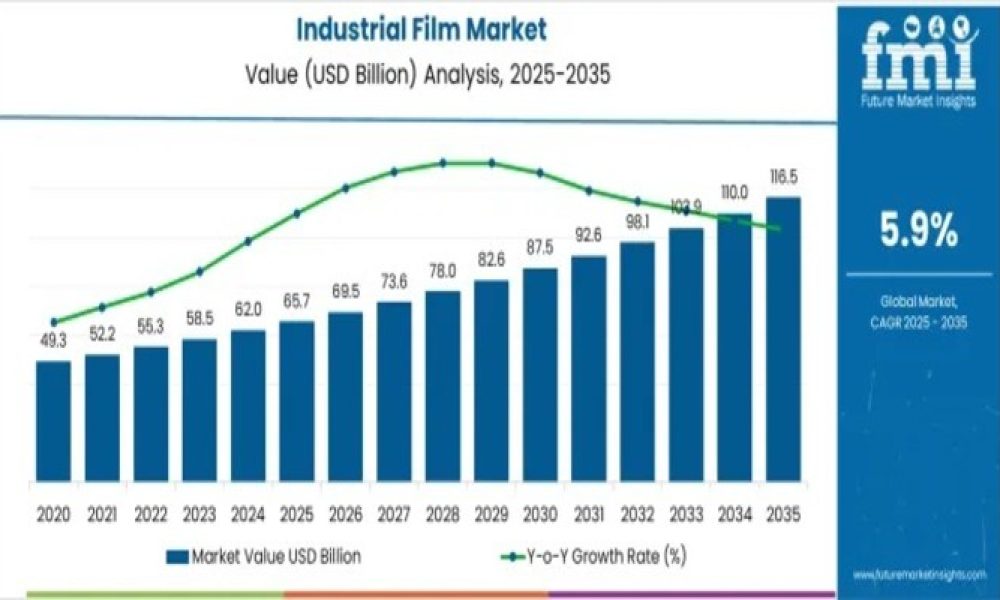
The global industrial film market is entering a decade of steady, innovation-driven expansion as manufacturers, logistics providers, and construction firms increasingly rely on advanced film solutions to protect, insulate, and package goods across complex supply chains. Valued at USD 65.7 billion in 2025, the market is projected to nearly double to USD 116.5 billion by 2035, advancing at a compound annual growth rate (CAGR) of 5.9% between 2025 and 2035.
This growth reflects the rising demand for durable, lightweight, flexible, and cost-effective materials across packaging, transportation, construction, agriculture, and medical applications. Continuous progress in polymer science, extrusion technologies, and coating processes is expanding the functional capabilities of industrial films, while sustainability mandates are accelerating the shift toward recyclable and circular material solutions.
Discover Growth Opportunities in the Market – Get Your Sample Report Now
Industrial Film Market at a Glance
- Market Size (2025): USD 65.7 billion
- Forecast Value (2035): USD 116.5 billion
- Forecast CAGR (2025–2035): 5.9%
- Leading Material Segment (2025): Low-Density Polyethylene (LDPE) – 27.4% share
- Dominant End-Use Segment: Packaging – 31.8% share
- Key Growth Regions: North America, Asia-Pacific, Europe
Market Drivers Shaping the Outlook
The industrial film market is being reshaped by a convergence of operational efficiency needs, regulatory pressures, and evolving customer expectations. Industries are increasingly prioritizing materials that offer high barrier protection, mechanical strength, and adaptability, without compromising cost efficiency.
Key growth drivers include:
- Rising demand for protective packaging to prevent moisture, contamination, and damage during storage and transit
- Rapid expansion of e-commerce and logistics, driving demand for stretch, shrink, and pallet-wrapping films
- Increased use of films in construction and infrastructure, including moisture barriers, insulation, and surface protection
- Growing preference for recyclable, biodegradable, and PCR-content films amid tightening environmental regulations
- Integration of automation and digital printing to improve productivity, traceability, and customization
Segment Insights: LDPE and Packaging Lead the Market
By Type, Low-Density Polyethylene (LDPE) continues to dominate the market, accounting for 27.4% of total demand in 2025. Its flexibility, moisture resistance, ease of processing, and cost-effectiveness make it a preferred choice across packaging, agriculture, and construction applications. Ongoing advances in film extrusion are enhancing LDPE’s transparency, strength, and recyclability, while the development of bio-based LDPE variants is strengthening its long-term competitiveness.
By End Use, the packaging segment leads with a 31.8% market share, driven by the need to preserve product integrity, extend shelf life, and enhance visual appeal. Growth is reinforced by:
- Multi-layer film innovations for improved barrier performance
- Increased adoption of sustainable and recyclable packaging films
- Automation and digital quality control systems improving operational efficiency
High-Growth Investment Segments
Several segments are emerging as strong investment opportunities over the forecast period:
- Linear Low-Density Polyethylene (LLDPE):
- Forecast CAGR (2025–2035): 5.8%
- Driven by superior puncture resistance, tear strength, flexibility, and sealability
- Widely used in packaging, agriculture, and construction applications
- Transportation End Use:
- Forecast CAGR (2025–2035): 5.6%
- Demand fueled by pallet wrapping, load stabilization, and transit protection
- Sustainability and cost-efficiency priorities accelerating adoption of eco-friendly films
Regional Growth Highlights
- United Kingdom:
- CAGR (2025–2035): 7.1%
- Strong manufacturing base in automotive, aerospace, and construction
- Strategic gateway to European markets
- South Korea:
- CAGR: 6.8%
- Advanced manufacturing and R&D-driven innovation
- High demand from electronics and industrial applications
- Japan:
- CAGR: 6.3%
- Focus on high-performance, precision-engineered films
- Strong adoption in automotive, electronics, and healthcare
- China:
- CAGR: 6.2%
- Rapid industrialization, urbanization, and government support for sustainable materials
- United States:
- CAGR: 6.1%
- Robust industrial base, infrastructure investments, and e-commerce growth
Challenges and Market Constraints
Despite its positive outlook, the industrial film market faces several challenges:
- Intense competition and price pressure in mature markets
- Volatility in raw material prices, impacting margins
- Compliance costs linked to environmental and quality regulations
- Competition from alternative packaging materials
- Slower adoption of advanced technologies in select regions
Competitive Landscape and Strategic Developments
The market is highly competitive, with global and regional players investing heavily in R&D, sustainability, and capacity expansion. Leading companies are strengthening their positions through mergers, acquisitions, and partnerships to broaden product portfolios and geographic reach.
Recent developments include:
- April 2025: Raven Engineered Films acquired by Industrial Opportunity Partners to accelerate polymer film innovation
- May 2024: Mitsubishi Chemical Holdings acquired Nakai Industrial Co. Ltd. to expand film coating capabilities
- February 2024: INDEVCO Plastics launched recyclable films with up to 50% post-consumer recycled resin
Key Companies Operating in the Market
Berry Global Inc. • Dow • DuPont de Nemours Inc. • TOYOBO Co. Ltd • Klöckner Pentaplast • Mitsui Chemicals, Inc. • Jindal Poly Films • Bemis Company, Inc. • Avery Dennison • DIC Corporation • Polifilm GmbH • WINPAK LTD. • Transcendia Vecom • MURAPLAST d.o.o. • Ishakha Polyfab Pvt Ltd., among others.
Outlook:
With sustained investments in material innovation, sustainability, and production scalability, the industrial film market is well-positioned for consistent revenue growth and global expansion through 2035, reinforcing its role as a foundational material across modern industrial ecosystems.
Why FMI: https://www.futuremarketinsights.com/why-fmi
About Future Market Insights (FMI)
Future Market Insights, Inc. (FMI) is an ESOMAR-certified, ISO 9001:2015 market research and consulting organization, trusted by Fortune 500 clients and global enterprises. With operations in the U.S., UK, India, and Dubai, FMI provides data-backed insights and strategic intelligence across 30+ industries and 1200 markets worldwide.



