Honorary consuls may receive specific exemptions supporting official functions. Still, residence-registration relief excludes those conducting private professional or commercial activities for profit, while customs and tax benefits depend on the item, income, premises, and applicable national rules.
WASHINGTON, DC, September 22, 2026
Honorary consular appointments provide narrowly defined fiscal and administrative benefits. Still, the rules contain important exceptions that make blanket statements about residence permits, duty-free imports, or complete exclusion from tax relief unreliable without examining the relevant treaty provisions.
The Vienna Convention on Consular Relations expressly limits registration relief for officers engaged in private professional or commercial activity, while separately addressing official imports, remuneration received from the sending state and qualifying premises owned or leased by that state.
Private careers and businesses do not receive a general tax exemption through the appointment, although saying that every honorary consul must pay every tax in full also overlooks specific treaty relief and ordinary exemptions available under applicable domestic law.
The Convention Separates Different Types of Relief
Chapter III of the Vienna Convention on Consular Relations establishes several distinct provisions affecting honorary consuls and their posts, rather than creating one general exemption that applies whenever an expense or activity has an official connection.
Article 60 addresses qualifying consular premises, Article 62 concerns specified imports for official use, Article 65 covers foreign-national registration and residence permits, and Article 66 concerns remuneration received from the sending state for performing consular functions.
Each provision has its own scope, so you must identify the specific benefit being claimed before determining whether the officer, transaction, or property meets the relevant conditions under the receiving country’s applicable framework.
The distinction matters operationally because an item eligible for customs relief does not necessarily create a sales-tax refund entitlement, just as an exemption concerning official remuneration does not automatically extend to the officer’s separate professional earnings.
Residence-Registration Relief Has an Express Business Exception
Article 65 provides an exemption concerning registration of foreign nationals and residence permits, but expressly excludes honorary consular officers who conduct professional or commercial activities for personal profit within the receiving state, making the exception central to understanding the rule.
That wording directly affects the proposition that all honorary consuls are exempt, because the professional or business activity maintained alongside an honorary appointment can place the individual outside the exemption described in that particular treaty provision.
For example, a hypothetical honorary consul operating a profitable local consultancy cannot assume Article 65 removes residence-permit requirements simply because the person also performs recognized consular functions. However, another lawful basis for residence may independently be available.
The provision therefore requires an assessment of the person’s actual activities and status, rather than an assumption that unpaid consular service necessarily means the individual has no profit-making professional or commercial role elsewhere in the host country.
Appointment Does Not Automatically Resolve Immigration Status
An honorary consular appointment should not be described as a universal immigration permission, because registration relief, authorization to reside, entry requirements, and permission to undertake private employment concern related but distinct questions within national legal systems.
A person who already holds host-country citizenship or permanent residence may have an independent basis for living there. At the same time, an individual with another status must examine the rules applicable to their circumstances and proposed activities.
Article 71 also affects the personal privileges of consular officers who are nationals or permanent residents of the receiving state, making nationality and residence relevant to the wider analysis rather than incidental details that can be ignored.
The practical conclusion is that the appointment and immigration status should be assessed together, with the relevant authorities confirming any exemption rather than treating the honorary title as sufficient evidence that ordinary requirements no longer apply.
Customs Relief Covers Specified Official Articles
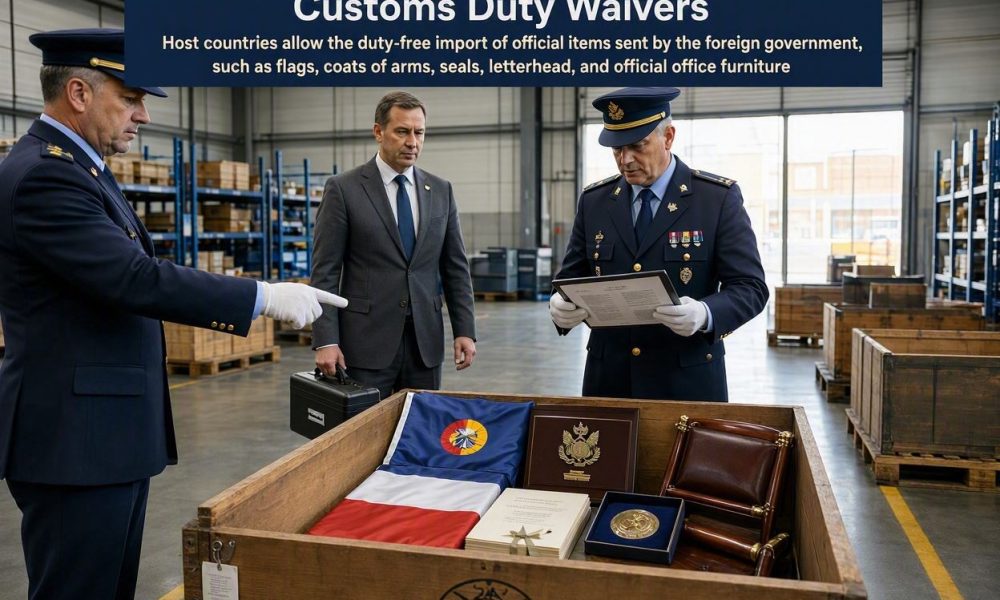
Article 62 provides relief for specified items intended for the official use of a post headed by an honorary consul, including flags, coats of arms, signboards, seals, stamps, books, official printed materials, office furniture and office equipment.
The provision also requires the sending state to supply those items or to do so at its instance, making both the official purpose and the circumstances of supply relevant to the claim for exemption under the treaty.
This wording is broader than a requirement that every eligible item be physically dispatched from a government warehouse. Still, it does not permit an officeholder to characterize unrelated personal purchases as official imports through unilateral designation alone.
A hypothetical shipment of authorized consular stationery and office equipment could fall within the provision, while the receiving state’s lawful import procedures still determine how the shipment is declared and how eligibility for relief is established.
Duty Relief Does Not Eliminate Every Import Expense
Article 62 excludes charges for storage, cartage, and similar services from its exemption, meaning that an eligible official shipment can still generate expenses even when customs duties and covered taxes are relieved under the treaty.
The receiving state administers the provision through applicable laws and regulations, so documentation and clearance procedures remain relevant rather than disappearing because the goods have been ordered for use in an honorary consular office.
Shipping charges, handling arrangements, and other commercial services should therefore be distinguished from customs duties, allowing the supervising mission and officeholder to understand which costs the exemption covers and which require separate payment or arrangements.
Accurate budgeting begins with these categories rather than describing an official shipment as entirely free of charges, particularly where delays or additional services could generate expenses unrelated to whether the goods satisfy the treaty’s exemption requirements.
Personal Purchases and Business Inventory Receive No General Relief
The Article 62 exemption does not provide a general entitlement to import personal luxury goods, private vehicles or stock for the honorary consul’s commercial business without duties and taxes, because those categories are outside its stated official-use purpose.
However, describing such goods as invariably “fully taxed” would also be imprecise, since ordinary tariff rules, trade agreements or other lawful relief may affect the amount payable independently of the individual’s honorary consular appointment.
The accurate distinction is that honorary status itself supplies no general exemption for those private imports, leaving their treatment to the customs and tax rules ordinarily applicable to the goods, importer and particular transaction involved.
In a hypothetical shipment combining official flags with merchandise intended for resale by the officeholder’s company, the goods would require separate classification rather than a blanket claim that the entire shipment serves the consular post.
Official Remuneration Has Its Own Tax Provision
Article 66 exempts remuneration and emoluments received from the sending state in respect of exercising consular functions, creating an express exception to the broad claim that honorary consuls receive no exemption from national taxation whatsoever.
The provision does not require every honorary appointment to be salaried. Still, it becomes relevant where the sending state provides qualifying compensation, making the nature and source of the payment important in assessing its treatment.
An honorarium connected with official consular responsibilities should therefore be distinguished from fees earned through private consulting or another business, rather than grouped solely because all payments reach the same individual during the appointment period.
The officer’s domestic reporting obligations and the treatment of particular payments may still require examination, because an exemption from a tax charge does not necessarily answer every administrative question about documenting or reporting the relevant income.
Private Income Remains Subject to Ordinary Tax Rules
An honorary appointment does not create a general exemption for profits from the officeholder’s law practice, hotel, trading company or other private occupation, leaving that income subject to the tax rules applicable to the person and business.
The actual liability depends on the relevant jurisdiction’s rules and the facts, including applicable deductions, credits or other lawful relief, so the phrase “full income tax” should not be used to imply that ordinary tax treatment disappears.
An individual and a company may also have separate obligations, making it important to identify who earned the income and who owes the tax rather than assume the honorary consul’s status determines the treatment of every associated entity.
This distinction keeps the official remuneration provision within its intended scope while avoiding the opposite error of suggesting that honorary officeholders lose access to ordinary tax provisions available independently of their consular role or appointment.
Qualifying Premises Can Receive Limited Tax Relief
Article 60 addresses consular premises of an honorary post where the sending state is the owner or lessee, providing an exemption from specified governmental dues and taxes while excluding payments for particular services rendered to the premises.
The article also preserves taxes payable under local law by the person who contracted with the sending state. This qualification prevents the provision from being summarized as automatic elimination of every tax connected with the property.
A private business does not obtain a general property-tax exemption merely because its owner serves as an honorary consul or keeps official documents on site, since the premises and the relevant ownership or lease arrangements must satisfy the applicable requirements.
For a shared property, the analysis should identify the qualifying consular premises and the actual legal arrangements, rather than assume that use of one room makes the entire residence or commercial building eligible for relief.
Canadian Guidance Illustrates the Narrow National Application
Global Affairs Canada states that honorary consuls do not receive GST/HST rebates on either personal expenses or the post’s official expenses, demonstrating why an official purpose alone does not establish eligibility for every type of domestic tax relief.
The same guidance excludes customs and excise exemptions for alcohol and tobacco, including alcohol purchased for official events, making it particularly important to distinguish ceremonial use from an entitlement to purchase goods free of the otherwise applicable charges.
Canada recognizes the limited official-import categories described in Article 62. It expects the diplomatic mission to be the importer of record, while also acknowledging possible additional provincial courtesies that require separate inquiry with the relevant protocol office.
These examples describe Canada’s published approach rather than a universal schedule for every host country, so a claim about another jurisdiction should cite its applicable rules rather than transferring Canadian procedures or restrictions without verification.
Diplomatic Comparisons Need Similar Precision
Career diplomats generally operate under a different treaty framework, but describing them as universally free from taxes would also be misleading, because diplomatic fiscal privileges contain exceptions and depend on the person’s status and the particular obligation involved.
For honorary consuls, the more useful comparison identifies the specific benefit sought and the relevant provision, avoiding a broad contrast in which one category supposedly pays nothing. At the same time, another supposedly receives no relief under any circumstances.
The ICIJ and ProPublica Shadow Diplomats investigation documented controversies involving honorary consuls and oversight weaknesses, illustrating the importance of checking claimed privileges without establishing that every officeholder misuses exemptions or faces identical national restrictions.
Public explanations should therefore distinguish a valid treaty entitlement, a discretionary local courtesy, and an unsupported claim of personal benefit, allowing readers to understand both the existence of official relief and the conditions limiting its use.
The Exemption Must Match the Activity or Transaction
For Background, Amicus International Consulting’s honorary-consul overview discusses the role, while confirming that any tax, customs, or residence exemption requires the relevant treaty provisions and guidance from the authorities responsible for administering them.
The company’s information about tax Identification numbers concerns a separate administrative subject, and holding such a number neither grants a consular exemption nor independently determines tax residence, the treatment of official remuneration or a business’s tax liability.
A sound assessment identifies the person’s status, whether private profit-making activity is involved, the source of any payment and the ownership or intended use of relevant goods and premises before applying a particular exemption to the facts.
Honorary consuls consequently receive defined relief supporting official functions, with a substantial exception to residence-registration Protection and specific provisions for imports, remuneration and premises. At the same time, their private careers and businesses remain governed by the ordinarily applicable legal framework.