
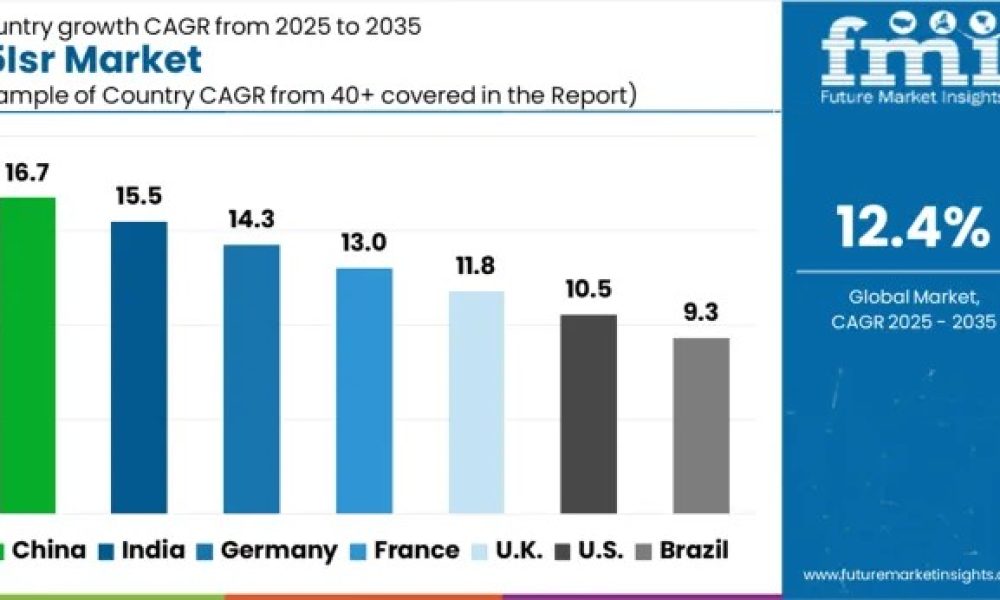
The global C5ISR (Command, Control, Communications, Computers, Combat Systems, Intelligence, Surveillance, and Reconnaissance) market is entering a decisive growth phase, projected to expand from USD 11.9 billion in 2025 to USD 38.3 billion by 2035, registering a robust compound annual growth rate (CAGR) of 12.4% over the forecast period. This rapid expansion underscores the increasing strategic importance of integrated, network-centric systems that enable real-time situational awareness, faster decision-making, and coordinated multi-domain operations.
During the early adoption phase between 2020 and 2024, growth was driven primarily by pilot deployments and targeted integration across select defense and intelligence applications. At this stage, production volumes were limited, and stakeholders focused on validating system performance, operational reliability, and mission effectiveness. These initial deployments laid the foundation for broader acceptance by demonstrating tangible improvements in intelligence gathering, communication resilience, and command efficiency.
Transition to Scaling and Consolidation
By 2025, as the market reaches USD 11.9 billion, the C5ISR industry transitions into a scaling phase. Adoption expands beyond experimental programs to wider operational use across land, air, naval, space, and cyber domains. This phase is characterized by increasing production capacity, improved integration frameworks, and the gradual standardization of deployment practices. Confidence among procurement authorities and defense organizations strengthens as early implementations mature into proven operational assets.
Between 2025 and 2030, the market is expected to grow rapidly, expanding to approximately USD 19–24 billion. Adoption accelerates across multiple regions, supported by streamlined procurement processes, enhanced interoperability, and greater alignment between hardware, software, and services. Investments during this period focus on integrating advanced sensors, secure communication networks, and data fusion platforms that support joint and coalition operations.
A second critical breakpoint emerges between 2030 and 2032, as the market approaches USD 27–30 billion. At this stage, C5ISR systems achieve widespread adoption, and growth begins to shift from rapid expansion toward consolidation. Supply chains stabilize, deployment processes become predictable, and leading suppliers strengthen their positions through long-term contracts and standardized system architectures. By 2035, with the market reaching USD 38.3 billion, C5ISR solutions are firmly established as mainstream defense capabilities, supported by mature production, reliable deployment, and recurring modernization cycles.
Get access to comprehensive data tables and detailed market insights — request your sample report today!
Drivers Fueling Market Momentum
Sustained growth in the C5ISR market is driven by the rising demand for integrated command and intelligence systems capable of operating in complex and contested environments. Defense organizations worldwide are prioritizing platforms that enable seamless data sharing, real-time threat detection, and coordinated mission execution across multiple domains.
The integration of artificial intelligence (AI), machine learning, cyber defense, and network-centric technologies is significantly enhancing operational efficiency. AI-enabled analytics improve intelligence processing and predictive capabilities, while edge computing reduces latency by enabling data processing closer to the source. These advancements are critical for time-sensitive operations where rapid response and accurate decision-making determine mission outcomes.
In addition to defense, interest in C5ISR technologies is expanding into homeland security, border protection, and maritime surveillance, broadening the addressable market. Growing geopolitical tensions, modernization of military infrastructure, and sustained increases in defense budgets further reinforce long-term demand.
Hardware Leads, New Installations Dominate
By solution type, hardware accounts for 58.4% of market revenue in 2025, making it the leading segment. Physical infrastructure—including high-performance servers, sensors, radars, and secure communication devices—forms the backbone of C5ISR operations. Continuous upgrades in radar systems, imaging technologies, and resilient communication terminals are essential for maintaining real-time intelligence and operational reliability in mission-critical environments.
By installation type, new installations represent 64.8% of market share in 2025, reflecting large-scale defense modernization programs and new infrastructure development. Governments are prioritizing the deployment of next-generation C5ISR systems in new command centers, aircraft, naval vessels, and space platforms rather than retrofitting older systems. New installations allow seamless integration of advanced technologies from the outset, reducing long-term maintenance complexity and improving lifecycle efficiency.
Defense Remains the Primary End User
The defense segment accounts for 87.6% of total market revenue in 2025, reinforcing its role as the dominant end-use category. C5ISR systems are central to modern military operations, supporting battlefield awareness, mission coordination, cyber defense, and intelligence gathering. Investments are being driven by the need to counter evolving threats such as electronic warfare, unmanned systems, and asymmetric tactics. The growing emphasis on joint and coalition operations further increases demand for interoperable, standardized solutions.
Drive Your Business Growth Strategy: Checkout the Report for Key Insights
Regional Growth Highlights Strategic Priorities
Regionally, North America, Asia-Pacific, and Europe remain the core growth markets. Asia-Pacific is emerging as a high-growth region, with China recording a CAGR of 16.7% and India at 15.5%, driven by large-scale defense modernization, domestic production capabilities, and expanding surveillance programs. In Europe, Germany posts 14.3% growth, reflecting sustained investment in defense and reconnaissance systems, while France records 13.0% and the United Kingdom 11.8%. The United States, a mature but technologically advanced market, is projected to grow at 10.5%, supported by continuous upgrades across defense, surveillance, and communication sectors.
Competitive Landscape Defined by Integration Expertise
The C5ISR market is highly competitive, led by global defense and aerospace companies including Lockheed Martin, Northrop Grumman, General Dynamics, Raytheon (RTX), BAE Systems, L3Harris, Elbit Systems, and Thales. Competition centers on technology leadership, system integration, cybersecurity resilience, and operational reliability. Leading players are investing heavily in R&D to enhance sensor performance, communication bandwidth, AI-driven analytics, and multi-domain interoperability.
Outlook
As defense forces worldwide continue to modernize and prioritize information superiority, C5ISR systems are becoming indispensable to operational success. The market’s transition from early adoption to large-scale deployment, followed by consolidation, reflects a maturing industry with strong long-term fundamentals. With sustained investment, rapid technological advancement, and expanding global demand, the C5ISR market is positioned as a cornerstone of future defense capabilities, offering significant opportunities for stakeholders seeking deeper insights into this fast-evolving sector.
Why Choose FMI: Empowering Decisions that Drive Real-World Outcomes: https://www.futuremarketinsights.com/why-fmi
About Future Market Insights (FMI)
Future Market Insights, Inc. (FMI) is an ESOMAR-certified, ISO 9001:2015 market research and consulting organization, trusted by Fortune 500 clients and global enterprises. With operations in the U.S., UK, India, and Dubai, FMI provides data-backed insights and strategic intelligence across 30+ industries and 1200 markets worldwide.



