
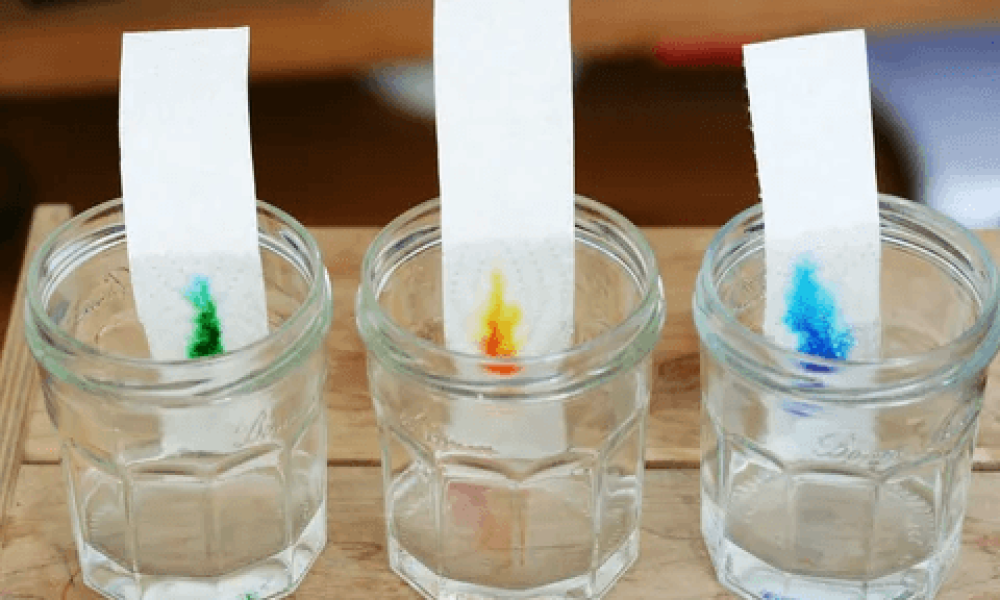
The global chromatography resin market is set for steady expansion, with its valuation projected to grow from USD 1.4 billion in 2024 to USD 2.3 billion by 2034, exhibiting a CAGR of 5.4% over the forecast period. This growth is driven by increasing demand in biopharmaceutical research, drug discovery, and the expanding applications of chromatography in food safety and environmental testing.
𝐑𝐞𝐪𝐮𝐞𝐬𝐭 𝐚 𝐒𝐚𝐦𝐩𝐥𝐞 𝐑𝐞𝐩𝐨𝐫𝐭 𝐍𝐨𝐰 𝐭𝐨 𝐠𝐞𝐭 𝐏𝐫𝐞𝐦𝐢𝐮𝐦 𝐈𝐧𝐬𝐢𝐠𝐡𝐭𝐬: https://www.futuremarketinsights.com/report-sample#5245502d47422d31333439
𝐊𝐞𝐲 𝐌𝐚𝐫𝐤𝐞𝐭 𝐃𝐫𝐢𝐯𝐞𝐫𝐬
- Rising Demand in Biopharmaceuticals
- Chromatography resins are widely used in the purification of monoclonal antibodies, recombinant proteins, and vaccines, contributing to market growth.
- Advancements in Drug Development
- Growing investments in pharmaceutical R&D and the increasing adoption of chromatography techniques for drug purification are fueling demand.
- Expansion of Food & Beverage Testing
- With stricter quality control regulations, chromatography resin usage in food safety and contamination analysis is rising.
- Growing Need for Environmental Monitoring
- Chromatography resins play a crucial role in water and air quality testing, further driving their adoption.
𝐆𝐫𝐚𝐛 𝐘𝐨𝐮𝐫 𝐂𝐨𝐦𝐩𝐥𝐞𝐭𝐞 𝐑𝐞𝐩𝐨𝐫𝐭 𝐈𝐧𝐬𝐭𝐚𝐧𝐭𝐥𝐲 – https://www.futuremarketinsights.com/reports/chromatography-resin-market
𝐊𝐞𝐲 𝐓𝐚𝐤𝐞𝐚𝐰𝐚𝐲𝐬
- Market Valuation: Expected to hit USD 2.3 billion by 2034, growing at a 5.4% CAGR.
- Strong Demand in Pharmaceuticals: Increasing reliance on chromatography for drug purification and vaccine production.
- Expanding Applications: Growing use in food safety testing and environmental monitoring.
- Technological Advancements: Development of next-generation chromatography resins to enhance efficiency and selectivity.
With the rising need for high-purity drug formulations, stringent regulatory guidelines, and advancements in chromatography technology, the chromatography resin market is poised for sustained growth over the next decade.
𝐇𝐨𝐰 𝐝𝐨𝐞𝐬 𝐭𝐡𝐞 𝐬𝐲𝐧𝐭𝐡𝐞𝐭𝐢𝐜 𝐬𝐞𝐠𝐦𝐞𝐧𝐭 𝐝𝐨𝐦𝐢𝐧𝐚𝐭𝐞 𝐭𝐡𝐞 𝐜𝐡𝐫𝐨𝐦𝐚𝐭𝐨𝐠𝐫𝐚𝐩𝐡𝐲 𝐫𝐞𝐬𝐢𝐧 𝐦𝐚𝐫𝐤𝐞𝐭?
The synthetic segment dominates the chromatography resin market due to several factors:
- Adaptability and Broad Applications: Synthetic resins are known for their versatility across a wide range of industries, including pharmaceuticals, chemicals, and food. They can be tailored with specific pore sizes, surface chemistries, and particle sizes to meet diverse application requirements.
- Superior Performance: Synthetic resins outperform natural resins under unfavorable conditions, such as severe pH and pressure. Polystyrene divinylbenzene is a frequently employed synthetic resin due to its superior performance attributes compared to natural polymers.
- Increasing Use in Ion Exchange Chromatography: The demand for synthetic resins is primarily fueled by their utilization in ion exchange chromatography. Synthetic resin is increasingly being used instead of natural resin to increase production figures.
- Customizability: Synthetic chromatography resins offer greater control over material properties, enabling manufacturers to tailor resins to meet diverse application requirements. The customizability ensures consistent performance and reproducibility, driving their adoption in various chromatography processes.
- Dominant Market Share: The synthetic segment is expected to hold a 73.3% market share in 2024. In 2022, the synthetic resin segment held a majority market value of USD 1.7 billion.
This dominance is further supported by the rising R&D activities in the pharmaceutical and biotechnology industries, which require highly pure, reproducible, and scalable solutions that synthetic chromatography resins provide.
𝐋𝐢𝐟𝐞 𝐒𝐜𝐢𝐞𝐧𝐜𝐞 & 𝐁𝐢𝐨𝐭𝐞𝐜𝐡𝐧𝐨𝐥𝐨𝐠𝐲 𝐈𝐧𝐝𝐮𝐬𝐭𝐫𝐲 𝐀𝐧𝐚𝐥𝐲𝐬𝐢𝐬: 𝐌𝐚𝐫𝐤𝐞𝐭 𝐏𝐫𝐨𝐣𝐞𝐜𝐭𝐢𝐨𝐧𝐬, 𝐈𝐧𝐧𝐨𝐯𝐚𝐭𝐢𝐨𝐧𝐬, 𝐚𝐧𝐝 𝐆𝐥𝐨𝐛𝐚𝐥 𝐓𝐫𝐚𝐝𝐞 𝐈𝐧𝐬𝐢𝐠𝐡𝐭𝐬 𝐀𝐜𝐫𝐨𝐬𝐬 𝟐𝟎+ 𝐂𝐨𝐮𝐧𝐭𝐫𝐢𝐞𝐬 – https://www.futuremarketinsights.com/industry-analysis/life-science-and-biotechnology
𝐖𝐡𝐚𝐭 𝐢𝐧𝐝𝐮𝐬𝐭𝐫𝐢𝐞𝐬 𝐚𝐫𝐞 𝐝𝐫𝐢𝐯𝐢𝐧𝐠 𝐭𝐡𝐞 𝐝𝐞𝐦𝐚𝐧𝐝 𝐟𝐨𝐫 𝐬𝐲𝐧𝐭𝐡𝐞𝐭𝐢𝐜 𝐜𝐡𝐫𝐨𝐦𝐚𝐭𝐨𝐠𝐫𝐚𝐩𝐡𝐲 𝐫𝐞𝐬𝐢𝐧𝐬?
- Pharmaceutical and Biotechnology: This sector is a major consumer of chromatography resins, with an 83.1% revenue share in 2023. Synthetic resins are essential in drug discovery, development, and the purification of biopharmaceuticals, particularly biologics, monoclonal antibodies, and gene treatments. The rising R&D activities, the increasing focus on personalized medicine, and the growing demand for biopharmaceuticals and biosimilars in this industry significantly contribute to the demand for synthetic chromatography resins.
- Food and Beverage: The food and beverage industry utilizes chromatography resins for quality control, ensuring product safety and adherence to regulatory standards. They are used in quality control, ensuring product safety and adherence to regulatory standards. The increasing demand for safe, hygienic, and non-toxic food products is expanding the market for chromatography resins in this sector.
- Environmental Testing: Chromatography resins are used in environmental testing for pollutant analysis, contributing to environmental monitoring and compliance.
- Other Industries: Synthetic chromatography resins are also used in other industries including academic research, petrochemicals, forensic science, sugar production, water treatment, and softening of industrial water.
𝐊𝐞𝐲 𝐂𝐨𝐦𝐩𝐚𝐧𝐢𝐞𝐬 𝐏𝐫𝐨𝐟𝐢𝐥𝐞𝐝
Agilent Technologies; Bio-Rad Laboratories; GE Healthcare; Waters Corporation; Expedeon Ltd; Thermo Fisher Scientific Inc.; Pall Corporation; Merck KGaA; Perkin Elmer Inc.; Kaneka Corporation; Shimadzu Corporation; Knauer GmbH; Tosoh Bioscience; Avantor Performance Materials Inc.; Mitsubishi Chemical Corporation; W.R. Grace & Co.; JSR Micro Inc.; Life Technology Corporation
𝐒𝐞𝐠𝐦𝐞𝐧𝐭𝐚𝐭𝐢𝐨𝐧 𝐀𝐧𝐚𝐥𝐲𝐬𝐢𝐬 𝐨𝐟 𝐭𝐡𝐞 𝐂𝐡𝐫𝐨𝐦𝐚𝐭𝐨𝐠𝐫𝐚𝐩𝐡𝐲 𝐑𝐞𝐬𝐢𝐧 𝐌𝐚𝐫𝐤𝐞𝐭
By Product Type:
- Native
- Synthetic
By Technology Type:
- Affinity Chromatography
- Anion Exchange Chromatography
- Cation Exchange Chromatography
- Size Exclusion
- Hydrophobic Interaction
By End User Type:
- Biopharmaceutical Companies
- Clinical Research Organizations
- Academic Institutes
By Region:
- North America
- Latin America
- Western Europe
- Eastern Europe
- South Asia and Pacific
- East Asia
- The Middle East and Africa




