
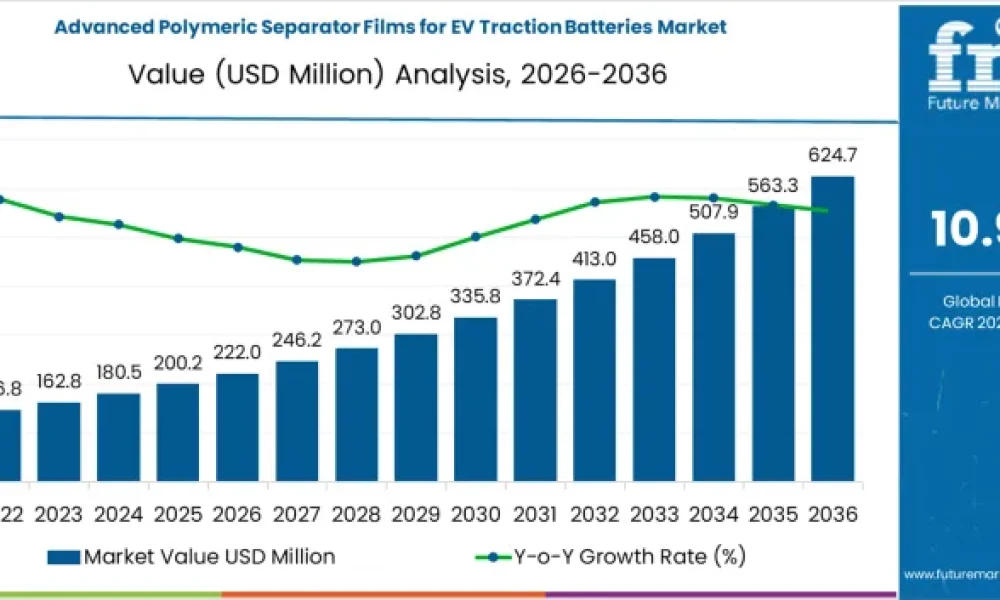
The global Advanced Polymeric Separator Films for EV Traction Batteries market is entering a pivotal growth phase as electric vehicle (EV) adoption accelerates worldwide, driving demand for high-performance battery components that enhance safety, reliability, and energy efficiency. In 2026, the market is projected to achieve a valuation of $222 million, with robust growth anticipated to propel it to approximately $624.7 million by 2036, expanding at a compound annual growth rate (CAGR) of 10.9% over the next decade. This strong trajectory underscores the crucial role polymeric separator films play in next-generation traction battery systems.
As the EV industry scales production and performance benchmarks rise, advanced polymeric separator films are increasingly recognized as essential components that support thermal stability, ionic conductivity, and mechanical integrity within lithium-ion cells. Separator films are engineered with innovative materials and multi-layer structures that dramatically reduce risk factors such as thermal runaway and short circuits—delivering both safety and performance improvements that align with global automotive standards and stringent regulatory requirements.
Key Market Insights at a Glance
The advanced polymeric separator films market is distinguished by dynamic growth drivers and evolving competitive forces. Polyolefin polymer films remain the dominant material segment due to their favorable balance of mechanical strength, thermal resistance, and manufacturing reliability, accounting for roughly half of total demand. Secondary segments such as ceramic-enhanced polymer composites, nano-engineered polymer blends, and multi-layer structures are gaining traction as EV manufacturers seek incremental performance advantages.
Notably, the EV traction battery separators application segment represents the largest share of demand, reflecting the priority placed on high-volume, high-safety battery builds. Demand in adjacent applications—including automotive energy storage systems, stationary energy storage, and portable electronics—further amplifies total addressable market potential.
Market dynamics hinge not only on rapid EV proliferation but also on evolving industry standards and rigorous cell safety protocols. Manufacturers are increasingly emphasizing consistency in film uniformity, dimensional stability, and porosity control, enabling separators to withstand high current densities and extended cycle life demands.
Segment Overview
Material segmentation reveals that polyolefin polymer films dominate due to mature manufacturing processes and predictable performance profiles. Meanwhile, advanced composite and multi-layer technologies hold promise for boosting thermal and mechanical performance in high-demand applications. In terms of application, traction battery separators lead by volume share—accounting for nearly half of global usage—supported by rapid EV deployment and heightened focus on battery safety and lifecycle performance benchmarks.
Across regions, adoption rates vary in accordance with EV manufacturing hubs and localized energy transition policies. India is poised to register the highest CAGR among key markets (over 12%), followed by China (≈11.5%) and Brazil (≈10.2%). The United States and the United Kingdom are forecast to exhibit solid growth between 9.5% and 10%, driven by manufacturing investments, incentive programs, and consumer uptake of electric mobility solutions.
To access the complete data tables and in-depth insights — Request Your Sample Report Now
Regional Overview
Asia Pacific remains a central growth engine for advanced separator films, supported by expansive EV manufacturing clusters in China, India, Japan, and South Korea. North America and Europe also demonstrate steady growth as battery producers and EV OEMs integrate high-performance separators into next-generation traction battery architectures. Across all regions, a combination of regulatory support, investment in local battery ecosystems, and strategic supply chain development is catalyzing sustained market expansion.
Competitive Landscape
The advanced polymeric separator films market features a competitive arena with established global players emphasizing innovation, quality, and scalable production. Leading companies include Asahi Kasei Corporation, Toray Industries, Celgard (Polypore International), SK Innovation, Sumitomo Chemical, Mitsubishi Chemical Group, and Freudenberg Performance Materials. These organizations differentiate themselves through material science leadership, precision coating and extrusion technologies, and strategic partnerships with EV and battery manufacturers.
Suppliers that deliver consistent, defect-free films and integrated support for high-speed cell assembly are best positioned to capture long-term value. Companies with validated technology platforms and quality management systems are gaining preference among major battery makers focused on regulatory compliance and operational excellence.
Market Outlook: Powering the Next Decade
Looking ahead, the advanced polymeric separator films market is expected to play an integral role in powering EV technology through 2036. Growth will be shaped by rising vehicle electrification rates, evolving safety standards, and continued innovation in polymer materials and manufacturing processes. As producers refine separator technologies, market value capture is anticipated to become increasingly tied to performance reliability, sustainability considerations, and cross-industry applications beyond automotive traction batteries.
Key Players of Sustainable Separator Film Industry
Industry leaders such as Asahi Kasei, Toray Industries, Celgard, SK Innovation, Sumitomo Chemical, Mitsubishi Chemical, and Freudenberg Performance Materials are driving market traction through strategic R&D, product differentiation, and long-term supply commitments. Their technology portfolios focus on balancing performance, safety, and compatibility with high-volume production demands.
Recent Strategic Developments
Recent initiatives in the separator films space include expanded production capacities, collaborative development projects with battery OEMs, and investments in advanced coating and processing technologies. These efforts support enhanced properties such as pore control, thermal shutdown capabilities, and electrolyte interaction optimization—key factors shaping future traction battery performance.
Have a specific Requirements and Need Assistant on Report Pricing or Limited Budget please contact us – [email protected]
About Future Market Insights (FMI)
Future Market Insights, Inc. (FMI) is an ESOMAR-certified, ISO 9001:2015 market research and consulting organization, trusted by Fortune 500 clients and global enterprises. With operations in the U.S., UK, India, and Dubai, FMI provides data-backed insights and strategic intelligence across 30+ industries and 1200 markets worldwide.
Why Choose FMI: https://www.futuremarketinsights.com/why-fmi



