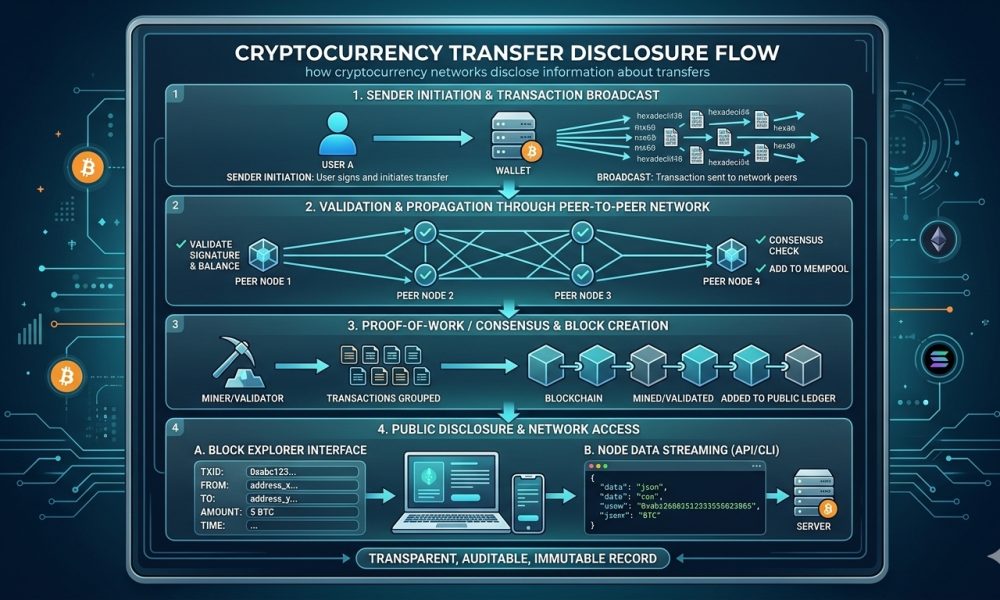
Investigations into digital assets examine transaction evidence and related financial activity while confronting differences in how cryptocurrency networks disclose transfer information.
Washington, DC, October 4, 2026 — Privacy-focused cryptocurrency has become a key focus of financial crime investigations because different blockchain systems reveal different amounts of transaction information, forcing investigators to combine technical analysis with exchange records, financial intelligence, device evidence, and conventional investigative methods.
The issue is not that privacy-oriented digital assets are inherently unlawful, because legitimate users may value confidentiality, but that reduced public visibility can complicate efforts to reconstruct financial relationships when authorities investigate fraud, money laundering, sanctions violations, or other suspected criminal conduct.
Not Every Cryptocurrency Reveals the Same Information
Public blockchains can differ substantially in how they record transaction amounts, wallet addresses, and transfer relationships, meaning investigators cannot assume that techniques effective on one network will work equally well on another.
Some systems make transaction histories broadly visible on a public ledger, while privacy-focused technologies can conceal or obscure selected details through cryptographic methods designed to reduce outside visibility.
This difference changes the evidentiary environment because investigators may have fewer immediately observable clues when attempting to determine who transferred value, how much moved, or which transactions may be related.
The broader regulatory response continues to evolve, with the Financial Action Task Force’s virtual asset framework requiring jurisdictions and covered service providers to address money-laundering and terrorist-financing risks associated with digital assets.
Privacy Technology Is Not the Same as Criminal Activity
Using a privacy-focused digital asset does not establish criminal intent because individuals and businesses may have legitimate reasons to want greater financial confidentiality.
Commercial sensitivity, personal security, and concern about publicly exposing account balances can motivate lawful users to prefer technologies that reveal less information on an open blockchain.
Investigators therefore need evidence linking a particular transaction or user to suspected unlawful conduct, rather than treating technological privacy as proof of wrongdoing.
This distinction remains important because financial privacy and criminal concealment may involve some of the same technologies while representing very different legal circumstances.
Investigators Look Beyond the Blockchain
When public blockchain information is limited, investigators can examine other evidence surrounding the transaction, including cryptocurrency exchange records, bank transfers, device data, communications, and account-opening information.
A transaction that appears difficult to interpret on-chain may still connect to an identifiable person through records created when digital assets were purchased, sold, or transferred through a regulated service provider.
Investigators may also compare transaction timing with email messages, business records, or conventional financial activity to determine whether several independent sources point toward the same relationship.
The investigation therefore extends beyond blockchain analysis alone, combining digital evidence with familiar financial-forensic techniques.
Exchanges Can Become Critical Evidence Sources
Centralized cryptocurrency exchanges often maintain customer-identification, transaction, and account records under the laws governing their operations.
Those records can help investigators connect blockchain activity with individuals or organizations when the underlying network itself provides limited public information.
The importance of these intermediaries is one reason international anti-money-laundering standards place obligations on virtual asset service providers involving customer due diligence, record-keeping and suspicious-transaction reporting.
The investigative significance depends on jurisdiction, applicable legal process, and the records the provider actually maintains, rather than on the assumption that every cryptocurrency transaction passes through a regulated exchange.
The Entry and Exit Points Can Be Easier to Investigate
Digital assets frequently interact with conventional financial systems when users purchase cryptocurrency with government-issued currency or later convert digital assets back into traditional money.
Those entry and exit points can create banking, payment-processing, or exchange records that remain visible even when the cryptocurrency network itself provides strong transaction privacy.
Investigators can therefore focus on the surrounding financial activity rather than attempting to reconstruct every transfer entirely from blockchain data.
This approach reflects a broader forensic principle: gather evidence across the full transaction lifecycle rather than from one technological layer alone.
Privacy Coins Can Complicate Blockchain Analytics
Traditional blockchain analytics often rely on public transaction histories, wallet relationships, and repeated patterns that allow investigators to develop hypotheses about how funds moved between addresses.
Privacy-focused systems can deliberately reduce the visibility of those relationships, making some conventional analytical assumptions less reliable or unusable.
That limitation does not necessarily make investigation impossible, but it can increase dependence upon external evidence and reduce confidence in conclusions derived solely from public-ledger observation.
Law enforcement agencies have consequently invested in broader technical and financial expertise as digital assets become increasingly common within both legitimate commerce and criminal investigations.
Transaction Evidence Can Still Exist Outside the Network
A cryptocurrency transfer can generate evidence on a phone, laptop, exchange account, or communication platform even when the blockchain itself reveals limited transaction detail.
Wallet applications can create records, transaction confirmations can be shared through messages, and users can discuss payments through email or encrypted communication services.
Investigators who lawfully obtain those records may therefore reconstruct transactions using evidence produced by the people and systems surrounding the cryptocurrency rather than relying exclusively upon the underlying ledger.
This illustrates why strong network privacy does not automatically eliminate all investigative evidence associated with a digital transaction.
Devices Can Provide Important Context
Digital forensic examinations can reveal wallet applications, transaction records, account identifiers, and other evidence stored on electronic devices when investigators obtain lawful authority to examine them.
The significance of those records depends on whether investigators can establish who controlled the device and whether the recovered information matches other evidence in the case.
A wallet appearing on a computer does not automatically prove ownership of every related transaction, just as possession of financial software does not independently establish unlawful activity.
Reliable investigations therefore combine device evidence with financial records, communications, and other corroborating information.
Communication Records Can Explain Transaction Purpose
The reason behind a cryptocurrency transfer often becomes clearer when investigators examine communications describing what the payment was intended to accomplish.
Messages discussing invoices, investments, purchases, or alleged criminal proceeds can turn an otherwise ambiguous transfer into evidence with much greater contextual meaning.
Investigators can compare transaction timing with those communications to determine whether the two appear connected.
This evidentiary approach resembles conventional financial investigations, where bank transfers become more informative when combined with contracts, emails, or witness testimony explaining why money moved.
Financial Institutions Can Provide Parallel Evidence
Traditional bank records can remain relevant even when the main transaction eventually occurs through cryptocurrency.
A person purchasing digital assets may transfer money to an exchange, use a payment processor, or receive fiat proceeds after selling cryptocurrency, creating conventional records around the digital activity.
Those records can help investigators identify transaction amounts, dates, and parties while also providing information required under financial compliance rules.
The distinction between digital and traditional finance therefore becomes less absolute during an investigation because the two systems frequently intersect.
Suspicious Activity Reporting Can Generate Leads
Financial institutions and regulated service providers can file reports when activity meets applicable suspicious-transaction thresholds or patterns, giving authorities potential investigative leads.
Such reports do not establish that a crime occurred because institutions often file them based upon risk indicators rather than proven criminal conduct.
Investigators must independently evaluate the underlying activity and obtain appropriate evidence before reaching a conclusion.
The reporting system nevertheless provides another source of information that can complement blockchain analysis when privacy-enhancing technology limits public transaction visibility.
International Standards Continue to Focus on Virtual Asset Risks
The Financial Action Task Force continues to update its work on virtual assets and virtual asset service providers as governments confront regulatory and investigative challenges associated with rapidly evolving digital-finance technologies.
Its current framework emphasizes licensing or registration of covered service providers, customer due diligence, record-keeping, and the secure transmission of originator and beneficiary information when the standards apply.
These measures focus largely upon regulated intermediaries rather than attempting to eliminate every privacy feature built into decentralized cryptocurrency protocols.
The international approach therefore seeks to create identifiable compliance points around digital-asset activity while recognizing that the underlying technology can operate across national borders.
The Travel Rule Creates Additional Information Outside the Blockchain
Under applicable virtual-asset rules, covered service providers can be required to obtain and transmit information concerning originators and beneficiaries when processing qualifying transfers.
That information exists separately from the details publicly visible on the blockchain.
Consequently, a transaction occurring through privacy-focused cryptocurrency may still generate identifying compliance records when regulated intermediaries participate in the transfer.
The effectiveness of this approach depends on consistent implementation across jurisdictions and service providers, which remains an ongoing challenge in the global virtual-asset sector.
Self-Custodied Wallets Create Different Investigative Conditions
Transactions involving self-custodied wallets can present a different evidentiary environment because no centralized intermediary necessarily controls the wallet or maintains conventional customer records for every transfer.
Investigators may therefore need to rely more heavily on device evidence, communications, financial entry points, and other contextual information to establish who controlled a particular wallet.
Self-custody does not automatically indicate suspicious activity because many legitimate cryptocurrency users hold their own assets.
It does, however, illustrate why digital-asset investigations often require several distinct evidence sources rather than relying on exchange records alone.
Privacy Features Can Be One Factor in a Larger Pattern
Investigators may consider privacy-enhancing technology alongside other behavior when evaluating a suspected financial crime, but the technology itself should not carry the entire evidentiary burden.
Repeated transfers following alleged fraud, unexplained asset conversions, false account information, or communications discussing concealment may collectively create a much more meaningful pattern.
The privacy feature can then become one element within a larger evidentiary picture rather than the central proof of criminal intent.
This approach reduces the risk of confusing legitimate technological preferences with evidence of unlawful conduct.
Money Laundering Investigations Examine Purpose and Knowledge
Money laundering generally involves more than simply moving funds through a complex or private financial system because prosecutors usually must establish relevant knowledge and criminal purpose under the applicable law.
Investigators therefore examine whether the assets represented proceeds of crime and whether transactions were designed or used in ways connected with concealing or facilitating that criminal activity. Cryptocurrency can be relevant evidence, but it does not eliminate the need to prove the underlying legal elements.
This distinction keeps financial crime investigations focused on conduct rather than treating an entire technology category as inherently suspicious.
Digital Assets Can Cross Borders Quickly
Cryptocurrency networks allow value to move internationally without relying upon the same correspondent banking structure used in conventional wire transfers.
That feature can complicate jurisdictional analysis because wallet activity may involve users, exchanges and infrastructure located in several countries.
Investigators may need international cooperation to obtain exchange records, device evidence, or information held by foreign service providers.
Cross-border evidence collection therefore becomes a major component of many significant digital-asset investigations.
Legal Process Still Governs Evidence Collection
Investigators generally need appropriate legal authority to obtain private exchange records, bank information, communications or device contents, depending upon the jurisdiction and type of evidence involved.
Blockchain transparency does not eliminate constitutional, statutory, or procedural protections that apply to nonpublic information held by institutions or individuals.
Evidence obtained improperly can create legal challenges that affect admissibility or the broader prosecution.
Financial crime investigations involving cryptocurrency therefore remain subject to ordinary requirements concerning warrants, subpoenas, court orders and international legal assistance where applicable.
Regulators Focus on Service Providers as Compliance Gateways
Government regulation often concentrates on exchanges, custodians and other service providers because those entities can become identifiable points where customer due diligence and transaction-monitoring requirements can operate.
The approach recognizes that decentralized technology itself may not have a central administrator capable of performing conventional financial compliance functions.
Regulated businesses interacting with those networks can still maintain records and detect suspicious activity under applicable law.
This creates a compliance layer surrounding cryptocurrency activity even when the underlying protocol was designed without traditional financial intermediaries.
Criminal Networks Use More Than One Financial Method
Recent European law-enforcement assessments continue to describe cryptocurrency as one of several technologies used by organized criminal networks alongside traditional banking, cash, legal businesses and other laundering techniques.
Europol has emphasized that criminal groups adapt rapidly to available financial technologies rather than depending exclusively upon one payment mechanism.
This broader context matters because investigators risk missing significant evidence if they focus entirely on cryptocurrency while ignoring conventional companies, property, cash transfers, or banking relationships within the same network.
Financial investigations therefore work best when they follow value across whatever instruments and institutions the participants actually used.
Privacy Technology Can Create Investigative Delay Without Ending the Inquiry
Reduced blockchain visibility can slow and complicate an investigation because investigators may need additional legal process and corroborating evidence before confidently reconstructing financial activity.
That difficulty can slow an inquiry without necessarily preventing authorities from identifying participants through other records.
Exchange data, seized devices, banking evidence and cooperating witnesses can all become more important when the network itself reveals comparatively little.
The practical effect is therefore often a shift in investigative method rather than the disappearance of evidence altogether.
Conversion Activity Can Connect Separate Evidence Sources
When someone converts cryptocurrency into traditional currency, investigators may be able to compare blockchain activity with exchange withdrawal records and bank deposits occurring at corresponding times.
Those relationships can provide stronger evidence when amounts and timing remain consistent across several independent sources.
The same reasoning can apply when fiat funds enter an exchange shortly before a cryptocurrency purchase associated with an investigation.
Correlation does not automatically prove common control, but several consistent records can create a stronger evidentiary foundation.
Business Records Can Explain Digital Payments
Companies increasingly accept or hold digital assets legitimately, which means investigators must distinguish ordinary commercial cryptocurrency activity from transactions allegedly connected with fraud or concealment.
Invoices, accounting records, and corporate agreements can show whether a cryptocurrency transfer represented payment for genuine goods or services.
False invoices or unexplained transactions can raise different questions when other evidence suggests the business relationship existed only to disguise financial movement.
Investigative analysis therefore remains closely tied to traditional accounting and documentary evidence, even when payment occurs through a decentralized network.
Regulatory Gaps Remain Uneven Internationally
Virtual-asset regulation continues to vary considerably between jurisdictions, creating differences in licensing, supervision, customer-identification requirements and enforcement capacity.
FATF’s July 2026 assessment reported continued progress alongside remaining gaps in global implementation of its standards for virtual assets and service providers.
Those differences can matter in investigations because records that are routinely available from one jurisdiction’s regulated exchange may be unavailable or less complete elsewhere.
International financial crime inquiries therefore frequently confront regulatory fragmentation in addition to technological complexity.
Privacy Should Not Be Equated With Illegality
Privacy-oriented cryptocurrencies raise legitimate policy questions about financial confidentiality, individual rights, compliance, and law-enforcement access. Still, those questions should not collapse into a presumption that privacy itself demonstrates criminal conduct.
Cash, encrypted communications and private banking arrangements can all serve lawful purposes while also appearing in criminal investigations under certain circumstances.
Cryptocurrency privacy presents a technologically different version of the same broader tension between confidentiality and accountability.
Responsible analysis should therefore focus upon evidence linking particular transactions to suspected offenses rather than stigmatizing every user of a privacy-enhancing technology.
Investigators Need Multiple Independent Sources
The strongest financial crime cases generally emerge when blockchain evidence, financial records, communications, device forensics and witness testimony support the same explanation of how money moved.
Privacy-focused cryptocurrency can reduce the information available from one of those sources without necessarily affecting the others.
Investigators may therefore compensate for reduced public-ledger visibility by placing greater emphasis upon regulated intermediaries and conventional forensic evidence.
This layered approach resembles other complex financial investigations, where no single transaction record provides the complete story.
Cryptocurrency Investigations Remain Evidence Investigations
The growing role of digital assets does not eliminate the fundamental requirement that financial crime cases be built on admissible evidence showing what occurred, who controlled the relevant assets, and how the activity connects to an alleged offense.
Privacy-enhancing technology can make some of those questions harder to answer, but difficulty should not be confused with impossibility or guilt.
Authorities must still separate technological assumptions from evidence and distinguish lawful privacy behavior from transactions supported by facts indicating criminal purpose.
For investigators, regulators and legitimate users alike, the central lesson is that privacy-focused cryptocurrency changes what can be observed directly on a network. At the same time, the broader financial and evidentiary environment can still provide substantial information about how digital assets were acquired, transferred, and ultimately used.