
The Latin America rigid industrial packaging market is gaining strong momentum as regional industries prioritize durability, safety, and regulatory compliance in bulk and transit packaging. Rigid industrial packaging plays a critical role in protecting chemicals, automotive components, food and beverage products, and pharmaceutical goods during storage and transportation. With increasing cross border trade and industrial output, manufacturers are adopting robust packaging solutions that reduce leakage, contamination, and product damage across complex supply chains.
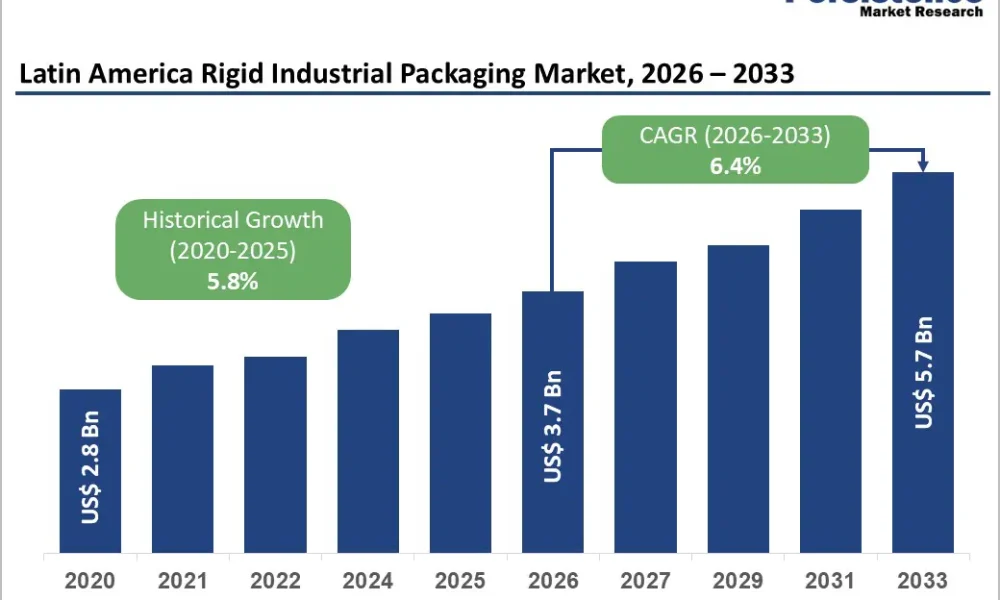
According to Persistence Market Research, the Latin America rigid industrial packaging market size is likely to be valued at US$3.7 billion in 2026 and is expected to reach US$5.7 billion by 2033, growing at a CAGR of 6.4% during the forecast period from 2026 to 2033. This growth is driven by rapid industrialization, expansion in chemicals, automotive, food and beverage, and pharmaceuticals, along with rising emphasis on product safety and compliance with stringent transportation regulations. The chemicals segment emerges as a leading end user due to its need for high strength containers, while Brazil stands out as a leading geographical region supported by its large industrial base and export oriented manufacturing ecosystem.
Get Your FREE Sample Report Instantly – Click Now : https://www.persistencemarketresearch.com/samples/36026
Key Highlights from the Report
➤ Strong demand for rigid industrial packaging driven by expanding chemical and pharmaceutical manufacturing
➤ Rising adoption of standardized packaging formats to meet transportation and safety regulations
➤ Growth supported by industrialization and infrastructure development across Latin America
➤ Increasing focus on product integrity during long distance and cross border logistics
➤ Chemicals identified as a leading end user segment due to hazardous material handling needs
➤ Brazil leading regional growth due to diversified industrial production and export activity
Market Segmentation Analysis
The Latin America rigid industrial packaging market can be segmented based on product type into drums, containers, intermediate bulk containers, and other rigid formats designed for heavy duty use. Drums and rigid containers hold a significant share as they are widely used for transporting liquids, powders, and semi solids in industrial environments. Their reusability, stackability, and resistance to external stress make them a preferred choice for manufacturers seeking cost effective and compliant packaging solutions.
Based on end user industry, the market is segmented into chemicals, automotive, food and beverage, pharmaceuticals, and other industrial sectors. The chemicals segment dominates due to strict safety requirements for hazardous and non hazardous materials. Food and beverage and pharmaceuticals are also witnessing increased adoption as companies focus on contamination prevention and regulatory adherence. Automotive manufacturers rely on rigid industrial packaging to protect high value components during regional and international shipments.
Get Personalized Data – Request Customization Today :
https://www.persistencemarketresearch.com/request-customization/36026
Regional Insights
Brazil represents a major share of the Latin America rigid industrial packaging market, supported by its strong chemical, automotive, and food processing industries. The country’s focus on export driven manufacturing and improving logistics infrastructure fuels consistent demand for rigid packaging solutions. Compliance with transportation regulations and quality standards further accelerates adoption among domestic and multinational manufacturers operating in Brazil.
Other Latin American countries are experiencing steady growth as industrial activities expand and regional trade strengthens. Increasing investments in pharmaceuticals and processed food production are encouraging the use of rigid industrial packaging for safe handling and distribution. As supply chains become more integrated across the region, demand for standardized and durable packaging formats continues to rise.
Market Drivers
Rapid industrialization across Latin America is a primary driver of the rigid industrial packaging market. Expanding manufacturing activities in chemicals, automotive, food and beverage, and pharmaceuticals require packaging solutions that can withstand harsh handling and long transit times. Rigid industrial packaging offers durability and reliability, making it essential for large scale industrial operations.
Another key driver is the rising emphasis on product safety and regulatory compliance. Stringent transportation regulations governing hazardous and sensitive materials push companies to adopt high quality rigid packaging. Businesses are increasingly investing in compliant packaging systems to minimize risk, avoid penalties, and protect brand reputation across domestic and export markets.
Market Restraints
Despite strong growth prospects, the market faces challenges related to high initial costs associated with rigid industrial packaging. Compared to flexible alternatives, rigid solutions often require higher upfront investment, which can limit adoption among small and medium sized enterprises. Cost sensitivity remains a restraint in price competitive industrial sectors.
Logistical complexities and storage requirements also pose restraints. Rigid packaging typically occupies more space and requires efficient reverse logistics for reuse or recycling. In regions with underdeveloped infrastructure, managing these logistics can increase operational costs and reduce overall efficiency for end users.
Market Opportunities
The growing focus on safe transportation of chemicals and pharmaceuticals presents significant opportunities for the Latin America rigid industrial packaging market. As regulatory scrutiny increases, manufacturers offering compliant and durable packaging solutions can gain a competitive advantage. Demand for packaging that ensures zero leakage and contamination is expected to remain strong.
Expansion of export oriented industries creates further opportunities for market players. As Latin American manufacturers integrate into global supply chains, the need for standardized rigid industrial packaging that meets international norms increases. Companies investing in innovative designs and region specific solutions are well positioned to capitalize on long term market growth.
Ready to Dive Deep? Buy Full Report Today : https://www.persistencemarketresearch.com/checkout/36026
Company Insights
Key players operating in the Latin America rigid industrial packaging market include
- Greif Inc.
- ALPLA Group
- ORBIS Corporation
- Mauser Group
- Berry Global Inc.
- Schütz GmbH & Co. KGaA
- DS Smith Plc
- Time Technoplast Ltd.
- Schoeller Allibert Group
- Brambles Limited
- Plastipak Packaging Inc.
- Rehrig Pacific Company
- Unipac Embalagens Ltda.
- RPC Group (Berry Global)
- Industrial Container Services (ICS)
- Hoover Container Solutions
- Myers Industries Inc.
- Bulk Handling Australia Group
Recent Developments
March 2024 A leading packaging manufacturer expanded its rigid container production capacity in Brazil to support growing chemical exports
July 2024 A major player introduced enhanced safety compliant industrial drums targeting pharmaceutical applications
Future Opportunities and Growth Prospects
The future of the Latin America rigid industrial packaging market remains promising as industrial growth, regulatory enforcement, and export activities continue to rise. With the market expected to grow from US$3.7 billion in 2026 to US$5.7 billion by 2033 at a CAGR of 6.4%, opportunities lie in serving high growth industries and supporting safe, compliant, and efficient logistics. Companies that align product innovation with regional industrial needs are likely to secure sustainable growth in the years ahead.




