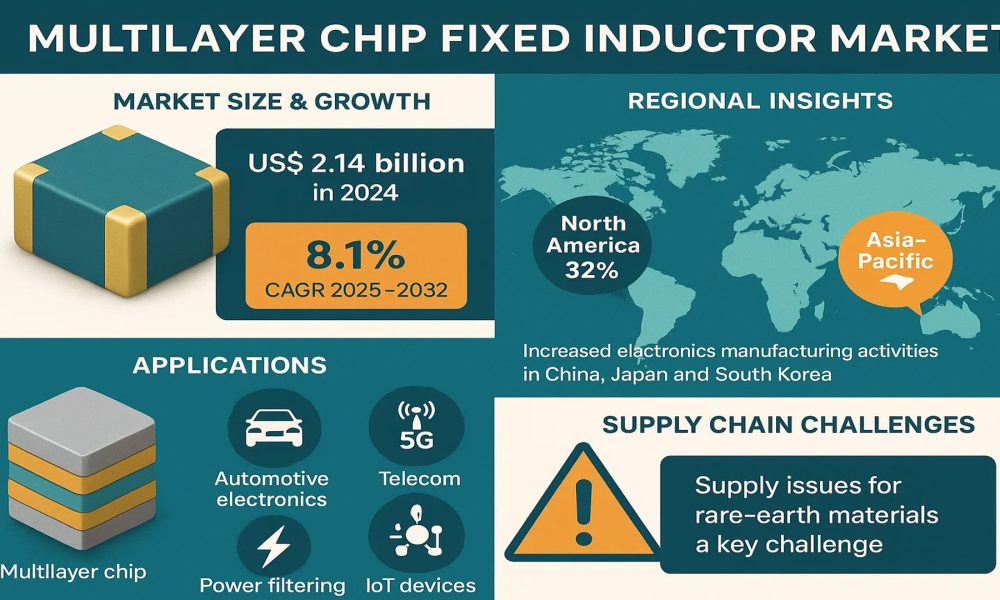
Multilayer Chip Fixed Inductor Market size was valued at US$ 2.14 billion in 2024 and is projected to reach US$ 3.67 billion by 2032, at a CAGR of 8.1% during the forecast period 2025-2032. While North America currently dominates with 32% market share, Asia-Pacific is emerging as the fastest-growing region due to increasing electronics manufacturing activities in China, Japan and South Korea.
Multilayer chip fixed inductors are passive electronic components that store energy in magnetic fields when electric current flows through them. These surface-mount devices are constructed by alternately printing ferrite slurry (soft ferrite ceramics) and conductor slurry layers, then sintering them to form a closed magnetic circuit. The manufacturing process, similar to MLCC (multilayer ceramic capacitors), enables ultra-small form factors ideal for modern circuit miniaturization in power filtering applications.
Market growth is primarily driven by increasing demand from automotive electronics, where these components are essential for advanced driver assistance systems (ADAS) and electric vehicle power systems. Furthermore, the proliferation of 5G infrastructure and IoT devices is creating new opportunities – telecom applications now account for 28% of total multilayer inductor demand. However, supply chain disruptions for rare-earth materials remain a key challenge for manufacturers. Leading players like TDK Corporation, Murata Electronics and Taiyo Yuden are investing in advanced ferrite materials to address this constraint while improving component performance.
Download Your Free Copy of the Sample Report-Multilayer Chip Fixed Inductor Market
MARKET DYNAMICS
MARKET DRIVERS
Proliferation of High-Frequency Electronic Devices Fueling Demand for Multilayer Chip Inductors
The global shift toward miniaturized, high-frequency electronic components is driving substantial growth in the multilayer chip fixed inductor market. These components are critical for power management in 5G infrastructure, advanced driver-assistance systems (ADAS), and IoT devices, where space optimization and electromagnetic interference suppression are paramount. The unique construction of multilayer inductors—combining high inductance values with compact form factors—makes them indispensable in modern circuit design. With 5G infrastructure investments projected to surpass $600 billion annually by 2026, demand for high-frequency compatible inductors is accelerating at an unprecedented rate. Furthermore, automotive electrification trends are amplifying this demand, as electric vehicles require 30-40% more inductors per vehicle compared to conventional models.
Automotive Electronics Revolution Creating New Application Verticals
The automotive sector’s transformation into a technology-driven industry is generating robust demand for multilayer chip inductors. Modern vehicles incorporate over 3,000 electronic control units requiring precision power management components. Key applications include infotainment systems, LiDAR sensors, and battery management systems for EVs. The automotive inductor market is growing at nearly 12% CAGR globally, with multilayer variants gaining preference due to their vibration resistance and temperature stability. Recent advancements in autonomous vehicle development have further intensified requirements for EMI suppression components, with multilayer chip inductors proving superior to traditional wire-wound alternatives in harsh automotive environments.
➤ Leading manufacturers are developing automotive-grade inductors with operational temperature ranges exceeding 150°C to meet stringent automotive qualification standards.
Consumer Electronics Miniaturization Trend Accelerating Adoption
The relentless drive toward thinner, lighter consumer electronics is fundamentally reshaping component requirements. Smartphone manufacturers are transitioning to multilayer chip inductors for power delivery networks, with flagship devices now incorporating over 20 such components per unit. Wearable technology represents another high-growth segment, where space constraints make the 0201 and 01005 package sizes of multilayer inductors indispensable. The global wearable market is projected to exceed 1 billion annual shipments by 2027, creating sustained demand for ultra-miniature passive components. Furthermore, the proliferation of GaN-based fast chargers—which require high-frequency inductors for power conversion—is expanding the addressable market for these components beyond traditional applications.
Recent Development – Multilayer Chip Fixed Inductor Market
- Miniaturization & High-Frequency Demand: Manufacturers are increasingly developing ultra-compact multilayer chip inductors to support 5G smartphones, IoT devices, and wearable electronics, where board space is limited.
- Automotive Applications Growing: Recent developments include AEC-Q200 qualified multilayer inductors designed for electric vehicles (EVs), ADAS, and infotainment systems, meeting automotive reliability standards.
- Material Advancements: Companies are investing in advanced ferrite and ceramic materials to achieve higher inductance stability and low DC resistance, enhancing performance in high-frequency circuits.
- Expansion in Production Capacity: Key players such as Murata, TDK, and Taiyo Yuden have announced expansions in production facilities in Asia to meet the surging demand from consumer electronics and automotive sectors.
- Integration with Power Management ICs: New product launches focus on inductors optimized for power management and RF modules, addressing the rising complexity of mobile and communication systems.
MARKET OPPORTUNITIES
Emerging 6G and Satellite Communication Infrastructure Presents Untapped Potential
The early-stage development of 6G networks and LEO satellite constellations is creating new opportunities for high-frequency multilayer inductors. These next-generation communication systems will operate in the sub-THz spectrum, requiring passive components with exceptional signal integrity at unprecedented frequencies. Leading manufacturers are already developing ultra-high-frequency inductor prototypes with resonance frequencies above 30GHz. The satellite communication sector alone is projected to require millions of specialized inductors annually as megaconstellations achieve full deployment. This emerging application vertical could potentially add $500 million to the global multilayer inductor market by 2030, representing a high-margin growth avenue for technologically advanced suppliers.
Advanced Packaging Technologies Enabling System-Level Integration
Breakthroughs in heterogeneous integration and system-in-package (SiP) designs are opening new frontiers for embedded inductor applications. The semiconductor industry’s shift toward 3D IC packaging creates demand for ultra-thin inductor arrays that can be integrated directly into package substrates. This trend is particularly evident in AI accelerator chips, where power delivery network optimization at the package level can improve performance by 15-20%. Leading OSAT providers are actively collaborating with passive component manufacturers to develop embedded inductor solutions compatible with advanced packaging flows. These developments promise to transform multilayer inductors from discrete components to integrated functional blocks within next-generation semiconductor packages.
Click to Access Your Free Sample Report-Multilayer Chip Fixed Inductor Market
List of Key Multilayer Chip Fixed Inductor Manufacturers
- TDK Corporation (Japan)
- Murata Electronics (Japan)
- Taiyo Yuden (Japan)
- KYOCERA AVX (U.S.)
- Samsung Electro-Mechanics (South Korea)
- Vishay Dale (U.S.)
- Bourns Inc. (U.S.)
- Abracon LLC (U.S.)
- KEMET (U.S.)
- Chilisin Electronics (Taiwan)
- Panasonic Electronic Components (Japan)
- Walsin Technology Corporation (Taiwan)
- Wiurth Elektronik (Germany)
- Shenzhen Sunlord Electronics Co., Ltd. (China)
- Guangdong Fenghua Advanced Technology Holding CO.,LTD (China)
Market competition is intensifying as companies develop novel materials like low-loss ferrites and high-permeability ceramics. Recent acquisitions in the semiconductor packaging sector indicate vertical integration trends, with major players securing supply chains for critical raw materials. The ongoing miniaturization trend in electronics continues to drive innovation in 0201 and smaller-sized inductors, particularly for wearable devices and IoT applications.
Segment Analysis:
By Type
Ceramics Segment Leads the Market Due to Superior High-Frequency Performance and Miniaturization Advantages
The market is segmented based on type into:
- Ceramics
- Subtypes: Low-Temperature Co-fired Ceramic (LTCC), High-Temperature Co-fired Ceramic (HTCC), and others
- Ferrite
- Subtypes: Nickel-Zinc (NiZn), Manganese-Zinc (MnZn), and others
- Others
By Application
Electronics Segment Dominates Due to Widespread Use in Consumer Electronics and Telecommunication Devices
The market is segmented based on application into:
- Automobile
- Subtypes: Electric vehicles, ADAS systems, infotainment systems
- Electronics
- Subtypes: Smartphones, laptops, wearables
- Signal Communication
- Subtypes: 5G infrastructure, IoT devices
- Photovoltaic
- Others
Other Topic-Single Ziner Diode Market
CONTACT US:
City vista, 203A, Fountain Road, Ashoka Nagar, Kharadi, Pune, Maharashtra 411014
[+91 8087992013]




