
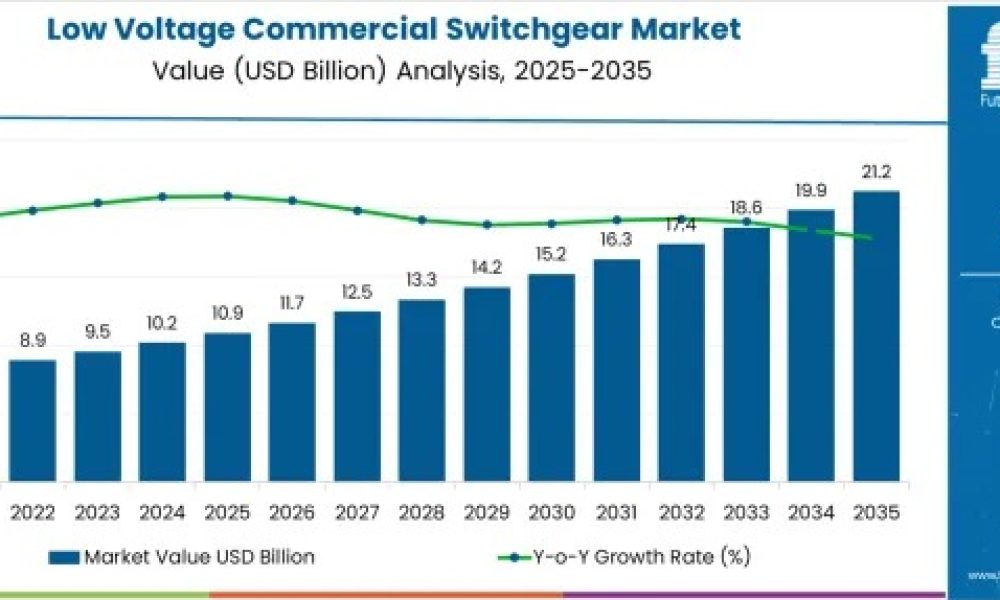
A new wave of investments in commercial infrastructure, digital energy systems, and modernization of aging electrical networks is positioning the Low Voltage Commercial Switchgear Market for significant long-term expansion. According to the latest industry assessment, the market is expected to reach USD 10.9 billion in 2025 and nearly double to USD 21.2 billion by 2035, registering a healthy 6.9% CAGR during the forecast period.
Subscribe for Year-Round Insights → Stay ahead with quarterly and annual data updates
https://www.futuremarketinsights.com/reports/sample/rep-gb-22789
Growing commercial energy requirements are being shaped by rapid urbanization, expanding data center footprints, and the rising integration of renewable energy into building systems. These shifts are reinforcing the demand for reliable, intelligent, and space-efficient switchgear that enhances power safety, optimizes energy distribution, and supports building automation.
Strong Market Momentum Backed by Infrastructure Growth
With large commercial complexes, IT campuses, retail centers, and hospitality establishments upgrading electrical distribution systems, low voltage switchgear is emerging as a core enabler of operational continuity. Facility managers are increasingly seeking compact, modular, and digital-ready equipment capable of predictive maintenance—reducing both downtime and lifecycle costs.
Industry leaders such as Schneider Electric, Eaton, ABB, Siemens, and Mitsubishi Electric are expanding portfolios to include real-time diagnostics, remote monitoring, and integrated control systems. This evolution is reshaping expectations for commercial power distribution, where the focus is shifting from traditional hardware to intelligent, connected infrastructure.
Demand Led by AC Systems and Air-Insulated Configurations
The AC current segment is projected to command 76.4% of total market revenue in 2025, driven by its cost efficiency, existing global compatibility, and ease of integration across commercial projects. AC-based switchgear has emerged as the default choice for developers seeking scalable, flexible distribution solutions for variable energy loads.
Within insulation types, air-insulated switchgear will dominate with a 41.4% revenue share in 2025, supported by its environmental safety, simplicity, affordability, and suitability for space-constrained buildings. Recent advances in arc management and compartmentalization technology have further strengthened demand.
Regulatory Push Accelerates Adoption
Regulatory bodies worldwide are tightening energy-efficiency and electrical safety standards, prompting commercial building owners to replace outdated systems with digital-ready, compliant configurations. These regulations have particularly accelerated market penetration in the United States, United Kingdom, Germany, China, and India—countries demonstrating strong transformation in commercial real estate and infrastructure.
China leads with a 9.3% CAGR, followed by India at 8.6%, reflecting accelerated construction and modernization of commercial facilities. Germany, the UK, and the U.S. are also recording robust growth driven by safety mandates, renovation cycles, and adoption of building energy management systems.
Regional Growth Highlights
United States: The CAGR increased from 4.8% (2020–2024) to 5.9% (2025–2035) as commercial operators invested in digital-ready switchgear to improve fault detection and energy efficiency. Retrofit installations account for more than 60% of market revenue.
United Kingdom: Growth climbed to 6.6%, supported by major commercial modernization programs and rapid integration of monitoring-enabled equipment.
Germany: An expected 7.9% CAGR reflects stringent compliance norms and a growing focus on integrating switchgear with distributed energy systems.
India: Demand is surging with an 8.6% CAGR, driven by retail expansion, IT corridor growth, and modernization of electrical infrastructure in emerging cities.
China: With a 9.3% CAGR, China continues to lead global adoption, driven by urban development, strict regulatory standards, and expanded local manufacturing.
Competitive Landscape
The market continues to be shaped by global and regional players offering modular assemblies, fault-management systems, and compact configurations. Companies such as General Electric, Hitachi, BHEL, CG Power, Toshiba, Hyosung Heavy Industries, HD Hyundai Electric, Fuji Electric, E+I Engineering, Lucy Group, Skema, and Ormazabal are strengthening product development and local supply chains to meet rising commercial demand.
As the industry shifts toward intelligent, digital, and space-efficient designs, vendors with strong capabilities in automation, predictive analytics, and environmental compliance are expected to gain a decisive competitive edge.
Get data that aligns with your strategic priorities — ask for report customization today:
https://www.futuremarketinsights.com/customization-available/rep-gb-22789
Have a specific Requirements and Need Assistant on Report Pricing or Limited Budget please contact us – [email protected]
About Future Market Insights (FMI)
Future Market Insights, Inc. (FMI) is an ESOMAR-certified, ISO 9001:2015 market research and consulting organization, trusted by Fortune 500 clients and global enterprises. With operations in the U.S., UK, India, and Dubai, FMI provides data-backed insights and strategic intelligence across 30+ industries and 1200 markets worldwide.
Contact Us:
Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531



