
Overview
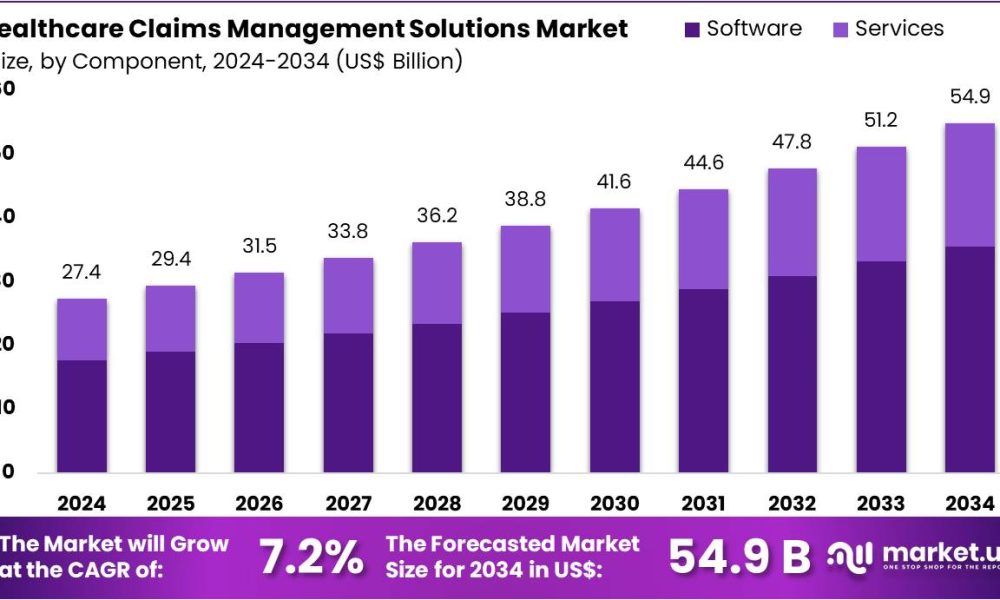
In 2024, the Global Healthcare Claims Management Solutions Market was valued at approximately USD 27.4 billion. This market is projected to grow at a compound annual growth rate (CAGR) of 7.2%, reaching around USD 54.9 billion by 2034. North America currently leads the market with a share of more than 38.2%, accounting for USD 10.4 billion in value. This dominance is supported by advanced healthcare infrastructure and high adoption of digital health technologies.
Healthcare Claims Management Solutions are software systems used to manage the medical claims lifecycle. These platforms allow healthcare providers to electronically generate, submit, and track insurance claims. Automation reduces manual errors and speeds up the approval process. As a result, providers and insurers benefit from faster reimbursements and more efficient revenue cycle management. These solutions also help maintain compliance and transparency in increasingly complex healthcare systems.
The adoption of digital technologies is transforming how claims are managed. According to the World Health Organization (WHO), all surveyed countries had integrated digital health into national strategies by 2021. In India, the Ayushman Bharat Digital Mission illustrates this shift. As of September 2024, it had issued 670 million digital health IDs and linked 420 million health records. This expansion highlights the importance of structured claims systems in national health frameworks.
Artificial Intelligence (AI) and automation are playing a crucial role in optimizing HCMS operations. Omega Healthcare Management, for example, automated nearly 100 million transactions since 2020. This implementation reduced documentation time by 40% and improved turnaround by 50%, while achieving 99.5% accuracy. These systems also saved over 15,000 employee hours each month, showcasing their efficiency and cost-saving potential. As similar technologies become more accessible, global adoption is expected to accelerate.
Cost control is a major driver behind the growth of the Healthcare Claims Management Solutions market. According to WHO estimates, billing errors and fraud accounted for about 7% of global healthcare spending in 2014, totaling USD 487 billion. Even a 10% reduction in such losses through digital claims systems could yield significant savings. This economic benefit is pushing both public and private healthcare organizations to invest in secure, automated platforms that reduce errors and prevent financial leakage.
The transition to value-based care is further increasing the need for intelligent claims solutions. Data from the U.S. Centers for Medicare & Medicaid Services (CMS) shows that participation in value-based reimbursement models rose by 25% between 2023 and 2024. These models prioritize outcomes over service volume, requiring claims systems capable of managing complex rules and payment structures. This trend is expected to sustain demand for flexible and advanced healthcare claims technologies in the coming years.

Key Takeaways
- By 2034, the global healthcare claims management solutions market is expected to double, reaching nearly US$ 54.9 billion from US$ 27.4 billion in 2024.
- This growth is projected at a stable CAGR of 7.2% from 2025 to 2034, driven by continued digital advancements in healthcare operations worldwide.
- In 2024, medical billing held the largest share within the product segment, contributing over 53.7% to the total healthcare claims management market value.
- Software components dominated the market in 2024 with a 64.8% share, reflecting rising demand for automation and digital data management solutions.
- Integrated solutions led the solution type category in 2024, securing 67.3% of the market due to their efficiency and compatibility across healthcare platforms.
- Healthcare providers emerged as the primary end-users in 2024, holding 65.2% market share by increasingly implementing digital claims infrastructure across facilities.
- North America remained the leading region in 2024, accounting for a 38.2% market share and generating US$ 10.4 billion in market revenue.
Get Sample: https://market.us/report/healthcare-claims-management-solutions-market/request-sample/
Regional Analysis
In 2024, North America held a dominant position in the healthcare claims management solutions market. The region captured more than a 38.2% share, with a market value of US$ 10.4 billion. This strong performance was supported by advanced healthcare systems and early adoption of digital tools. Widespread use of electronic health records (EHRs) has enabled a smooth transition to digital claims. Both public and private sectors have focused on administrative automation, making processes faster and more efficient for healthcare providers and insurers.
The United States contributed significantly to this regional growth. Federal policies such as the Affordable Care Act (ACA) and the Health Insurance Portability and Accountability Act (HIPAA) promoted secure and faster claims processing. Additionally, initiatives by the Centers for Medicare & Medicaid Services (CMS) supported digital platforms that reduce paperwork. These regulations helped healthcare facilities improve reimbursement cycles and minimize errors. As a result, there has been a marked increase in investments in advanced claims management technologies across U.S. healthcare institutions.
Technological innovation remains a key factor in the region’s continued growth. North American healthcare payers and providers are adopting AI and analytics tools to streamline claim workflows. These technologies enhance accuracy, detect fraud, and speed up approvals. Mobile-compatible platforms and real-time claims tracking systems are also on the rise. The increasing digitalization has made claims processing faster, more transparent, and more reliable, reinforcing North America’s leadership in the global market.
Segmentation Analysis
In 2024, the Medical Billing section held a dominant market position in the product segment of the Healthcare Claims Management Solutions Market, capturing over 53.7% share. This growth was driven by the increasing need for accurate billing and coding. Hospitals and clinics relied on billing systems to reduce claim rejections and speed up reimbursement timelines. Integration with electronic health records (EHRs) further improved efficiency. These tools reduced administrative delays and supported timely payments, enhancing provider revenue cycles across various levels of care.
The Professional Claims segment ranked second, supported by the expansion of outpatient services and physician-led care models. Providers increasingly adopted digital solutions to submit claims accurately. These systems minimized administrative errors and shortened payment cycles. Small and mid-sized practices particularly benefited from these tools due to their cost-effectiveness and regulatory compliance features. As insurance and healthcare policies became more complex, the adoption of professional claims software grew steadily, reinforcing its importance in claims management.
The Software component led the market with a 64.8% share in 2024, fueled by the demand for automation and regulatory compliance. Healthcare facilities preferred software platforms to streamline operations and minimize manual errors. Cloud-based systems also gained popularity due to their remote accessibility and integration capabilities. These platforms often included analytics tools for performance monitoring, offering added value to users. Hybrid service models combining software and support services are expected to gain more traction in future years.
In the solution type segment, Integrated Solutions held the largest share at over 67.3% in 2024. Their appeal lies in centralizing multiple processes such as billing, coding, and claims tracking in one platform. These tools enhanced financial transparency and reduced reimbursement delays. End-users favored integrated models for their efficiency and scalability. Meanwhile, standalone solutions remained relevant in smaller clinics for specific tasks. Despite holding a smaller share, their simplicity and cost-efficiency maintained their market presence in limited-function healthcare environments.
By Product
- Medical Billing
- Professional
- Institutional
- Claims Processing
By Component
- Software
- Services
By Solution Type
- Integrated Solutions
- Standalone Solutions
By End-use
- Healthcare Providers
- Healthcare Payers
Key Players Analysis
The healthcare claims management solutions market is evolving through digital innovation and strategic expansion by major players. The industry is moderately consolidated, with top vendors focusing on automation and service diversification. These efforts aim to enhance interoperability and reduce claims processing time. Companies are also responding to regulatory pressures and administrative cost challenges. As a result, digital tools are being adopted widely. This shift supports value-based reimbursement models and more efficient revenue cycle management in hospitals, clinics, and payer-provider organizations worldwide.
McKesson Corporation leads with its comprehensive revenue cycle management solutions. Its platforms integrate billing, reimbursement, and claims automation, improving data accuracy and regulatory compliance. McKesson’s tools help healthcare providers reduce claim denials and streamline complex workflows. Its systems are trusted by large health systems across North America. Similarly, The SSI Group Inc. offers real-time claims analytics and clearinghouse services. Its platforms integrate with electronic health records, enabling faster reimbursements and higher financial efficiency for both small and large providers.
Kareo supports independent practices through cloud-based platforms combining claims tracking, denial management, and billing. Its simple, scalable interface enhances usability for smaller clinics. Optum Inc., part of UnitedHealth Group, applies AI and predictive analytics to optimize claims accuracy. This reduces turnaround times significantly. Other key players include Athenahealth, Cerner Corporation, Allscripts, and Conduent Inc. These firms invest in machine learning, cloud computing, and API integration to meet regulatory needs and enhance claims precision.
Buy Directly: https://market.us/purchase-report/?report_id=150302
Get in Touch with Us:
Market.us (Powered By Prudour Pvt. Ltd.)
Address: 420 Lexington Avenue, Suite 300, New York City, NY 10170, United States.
Contact No: +1 718 874 1545 (International), +91 78878 22626 (Asia).
Email: [email protected]
View More
Brain Disease Device and Software Market
Animal Digital Health Market



