
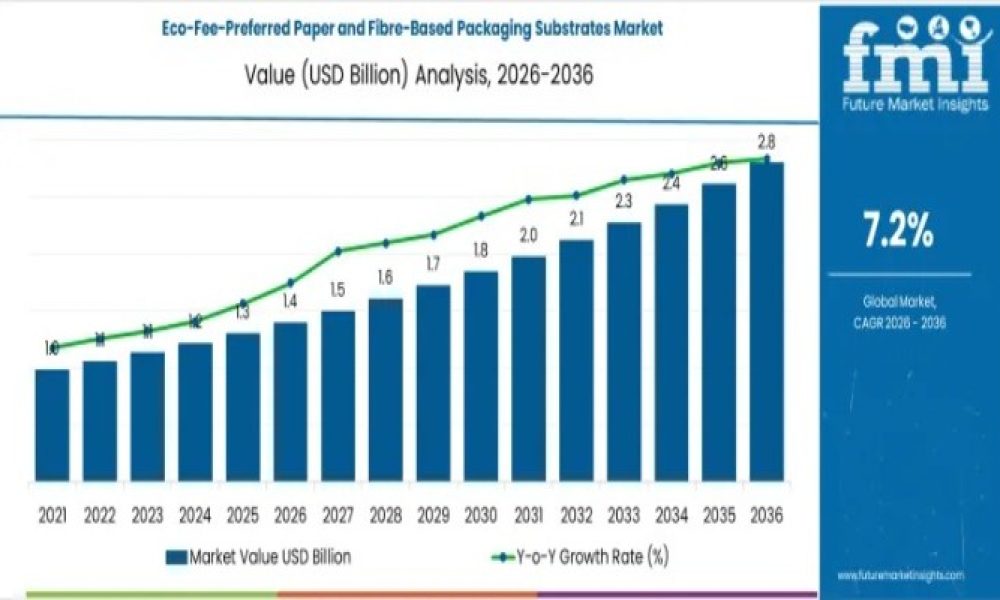
The global eco-fee-preferred paper and fibre-based packaging substrates market is entering a decisive decade of structural growth as sustainability regulation, circular economy targets, and operational efficiency converge across packaging value chains. Valued at USD 1.4 billion in 2026, the market is projected to reach USD 2.8 billion by 2036, expanding at a steady CAGR of 7.2%. This growth trajectory reflects not a short-term material shift, but a long-term reconfiguration of packaging strategies among brand owners, converters, and retailers worldwide.
Eco-fee-preferred paper and fibre-based substrates—such as recycled paperboard, kraft paper, molded fibre, and repulpable barrier-coated formats—are increasingly favored under environmental levy and extended producer responsibility (EPR) frameworks. These materials help reduce eco-fee liabilities while aligning with recyclability standards, making them a strategic choice for multinational brands seeking compliance, cost stability, and sustainability credibility.
Unlock Growth Potential – Request Your Sample Now and Explore Market Opportunities!
Market Growth Outlook: From Early Adoption to Structural Integration
Between 2026 and 2031, the market is expected to grow from USD 1.4 billion to approximately USD 2.0 billion. This initial phase is characterized by early adoption, primarily within e-commerce, retail, foodservice, and fast-moving consumer goods (FMCG) packaging. During this period, uptake is concentrated in pilot programs, select SKUs, and secondary packaging formats as manufacturers validate performance, optimize fibre blends, and adapt substrates to existing production lines.
From 2031 to 2036, growth accelerates as eco-fee-preferred substrates transition from selective use to portfolio-wide standardization. Market value expands from USD 2.0 billion to USD 2.8 billion, driven by repeat procurement, standardized production processes, and integration with eco-fee incentive programs. By this stage, fibre-based substrates are structurally embedded in global packaging strategies rather than deployed as compliance experiments.
Quick Market Highlights
- Market Value (2026): USD 1.4 billion
- Forecast Value (2036): USD 2.8 billion
- Forecast CAGR (2026–2036): 7.2%
- Leading Packaging Format: Corrugated & Folding Cartons (45% share)
- Key Growth Regions: India, China, USA, Brazil, Germany, Japan
What Is Driving Demand?
Early demand was largely shaped by cost pressures associated with eco-fees and environmental levies, particularly in developed markets. Plastic and non-recyclable packaging formats incurred higher fees, making fibre-based alternatives more economical. Over time, however, demand drivers have evolved.
Looking ahead, growth is increasingly fueled by:
- Lifecycle-based regulatory frameworks linking fees to recyclability, recycled content, and end-of-life performance
- Circular economy alignment, with brands redesigning packaging to minimize environmental externalities
- Advancements in fibre engineering, including compostable coatings, bio-based additives, and moisture-resistant paper structures
- Expansion of recycling infrastructure, improving fibre recovery rates and reducing contamination
End-Use and Packaging Format Dynamics
E-commerce and retail packaging account for approximately 40% of total demand, making them the dominant end-use segment. High parcel volumes, repeated packaging use, and direct exposure to eco-fee calculations make these sectors early and consistent adopters.
Other key application areas include:
- Foodservice and takeaway packaging
- Retail and shelf-ready packaging
- Agriculture and bulk packaging
- Food and beverage applications with selective moisture and barrier requirements
By packaging format, demand is led by:
- Corrugated boxes and folding cartons (45%), favored for strength, recyclability, and logistics efficiency
- Food trays and cups for disposability and waste system compatibility
- Paperboard wraps, tubes, and kraft sacks for retail and bulk transport needs
Rather than radical format changes, producers are focusing on incremental optimization of established fibre-based formats, ensuring equipment compatibility and predictable performance.
Regional Growth Snapshot
- India (CAGR 11.5%): Rapid expansion in packaged food, beverages, and personal care, supported by organized manufacturing and urban retail growth
- China (CAGR 10.0%): Large-scale industrial and e-commerce packaging demand, with domestic suppliers scaling eco-fee-preferred substrate production
- Brazil (CAGR 8.0%): Growth driven by organized retail, regional distribution hubs, and packaging modernization
- United States (CAGR 7.0%): Steady adoption across food, beverage, and personal care packaging aligned with sustainability targets
- Germany (CAGR 6.5%): Compliance-driven demand supported by strict sustainability regulations
- Japan (CAGR 4.0%): Mature market with selective, quality-focused adoption
Competitive Landscape: Scale, Compliance, and Supply Reliability
Competition in the eco-fee-preferred paper and fibre-based packaging substrates market is shaped by integrated paper and packaging producers aligning their grades with regulatory fee modulation frameworks. Global leaders such as Smurfit Kappa, WestRock, International Paper, Mondi, and Stora Enso focus on substrate strength, recyclability, printability, and long-term supply reliability.
Regional players play an equally critical role:
- Nine Dragons Paper and Lee & Man Paper dominate containerboard supply in China
- Ballarpur Industries supports India’s growing demand with cost-aligned fibre substrates
Across markets, competitive positioning is defined less by design differentiation and more by fibre sourcing consistency, operational efficiency, and responsiveness to customer specifications.
Why FMI: https://www.futuremarketinsights.com/why-fmi
About Future Market Insights (FMI)
Future Market Insights, Inc. (FMI) is an ESOMAR-certified, ISO 9001:2015 market research and consulting organization, trusted by Fortune 500 clients and global enterprises. With operations in the U.S., UK, India, and Dubai, FMI provides data-backed insights and strategic intelligence across 30+ industries and 1200 markets worldwide.



