
The High Purity Tungsten Hexachloride Market is entering a decisive decade of growth as global semiconductor expansion accelerates, nanomaterial research intensifies, and fabrication facilities scale contamination-free production capabilities. New projections indicate the market will rise from USD 72.2 million in 2025 to USD 119.9 million by 2035, advancing at a 5.2% CAGR and expanding 1.6X over the forecast period.
Semiconductor Miniaturization and Purity Standards Reshape the Market
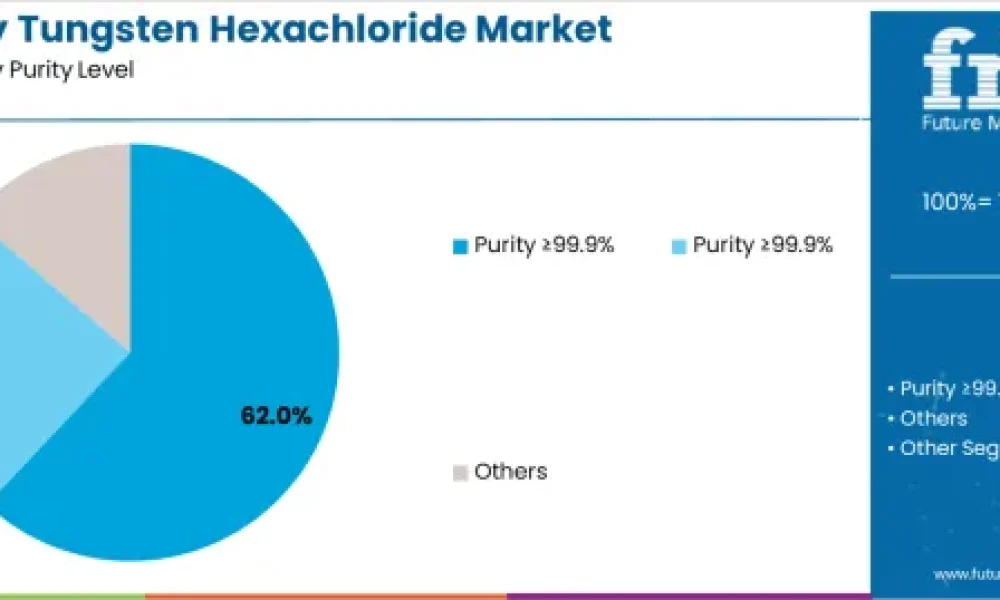
High purity tungsten hexachloride—an essential precursor for CVD and ALD processes—is witnessing rapid adoption as chipmakers migrate toward sub-nanometer nodes, AI-integrated systems, and 5G-enabled device architectures. With Purity ≥99.9% grades holding 62% market share, manufacturers are aggressively transitioning toward ultra-pure specifications to eliminate defect formation in thin-film deposition and barrier-layer fabrication.
The growing need for contamination control, automated handling workflows, and advanced material traceability is redefining procurement strategies for semiconductor fabs across East Asia, North America, Europe, and the Middle East.
Subscribe for Year-Round Insights → Stay ahead with quarterly and annual data updates: https://www.futuremarketinsights.com/reports/sample/rep-gb-27451
APAC Dominates Global Growth: China & India Lead Market Expansion
The strongest regional momentum continues to come from Asia-Pacific, particularly China (7.0% CAGR) and India (6.5% CAGR).
China – Fastest Growing Country Market
Government-supported semiconductor expansion in Beijing, Shanghai, and Shenzhen is accelerating the demand for ultra-pure tungsten precursors. Domestic producers are increasingly integrating advanced purification systems, enabling China to strengthen its position in global fabrication supply ecosystems.
India – Rising High-Growth Cluster
Semiconductor and nanotech hubs across Bengaluru, Hyderabad, and Mumbai are rapidly upgrading quality standards, embracing high-purity tungsten hexachloride for precision research and advanced electronic materials. Strengthening government incentives and international partnerships are expanding India’s material technology capabilities.
Europe Strengthens Its Advanced Materials Leadership
The European market is projected to grow from USD 16.8 million (2025) to USD 28.4 million (2035) at a 5.4% CAGR, supported by strong semiconductor infrastructure and quality compliance frameworks.
- Germany (42.1% share) remains the core of Europe’s semiconductor-grade chemical production, backed by high engineering standards and process automation.
- United Kingdom (26.3%) continues adopting high-purity materials for research-intensive applications.
- France, Netherlands & Switzerland further strengthen Europe’s footprint through specialty applications and advanced electronic component manufacturing.
United States Maintains Stable, Mature Market Growth
The U.S. market—growing at 4.9% CAGR—remains a global benchmark for quality compliance and semiconductor process integration. Demand is driven by leading clusters in California, Texas, and Oregon, where fabs increasingly require ultra-pure precursors for next-generation chips, AI processors, and specialized materials research.
Strong regulatory frameworks and mature distribution networks allow U.S. suppliers to expand advanced purity verification services, digital quality documentation, and purity-by-design material solutions.
Saudi Arabia & Middle East Turning into Strategic Technology Hubs
The Kingdom of Saudi Arabia (KSA) is emerging as a key market within the Middle East, supported by large-scale industrial diversification and investments in advanced materials, semiconductor pilot lines, and research infrastructure. Adoption is improving steadily as KSA aligns with international purity standards and strengthens partnerships with global chemical suppliers.
Market Dynamics: Opportunities, Challenges, and Growth Drivers
Key Growth Drivers
- Semiconductor expansion & advanced node development
Ultra-pure tungsten hexachloride is now essential for high-precision CVD/ALD processes and defect-minimization workflows. - Advances in purification technology
Integrated contamination monitoring, batch tracking, and ultra-clean packaging drive premium-grade adoption. - Nanotechnology and high-performance composites
Research institutions increasingly use high-purity materials for high-performance coatings, catalysts, and composites.
Restraints
- High purification costs continue to restrict adoption in emerging chemical manufacturing markets.
- Alternate precursor competition may slow growth in general industrial processing.
Need tailored insights? Request report customization to match your specific business objectives: https://www.futuremarketinsights.com/customization-available/rep-gb-27451
Segmental Insights: Purity, Application, and End-Use Trends
By Purity Level
- Purity ≥99.9% dominates (62% share)
Driven by semiconductor fabs that require strict contamination control, batch traceability, and purity certification. - Purity ≥99% holds 31% share
Used in chemical processing and standard applications where ultra-pure grades are not mandatory.
By Application
- Semiconductor industry accounts for 47% share
Rapid adoption driven by miniaturization and manufacturing modernization. - Chemical industry holds 35% share, while research applications capture 18%.
By End Use
- Semiconductor fabrication facilities lead with 35% share, reflecting their reliance on ultra-clean and stable chemical precursors.
- Research institutions and specialty materials manufacturers continue expanding their use of advanced precursors for innovation-driven projects.
Competitive Landscape: 8–12 Key Players Hold Market Leadership
Top players—including JX Advanced Metals Corporation, Nanoshel, Nano Research Elements, Hunan Huajing Powdery Material, American Elements, Merck KGaA, Thermo Fisher Scientific, Alfa Aesar, and Strem Chemicals—collectively command 70–75% of market revenue.
Competitive strengths include:
- Advanced purification systems
- Digital quality management and certification
- Semiconductor-grade contamination analytics
- Custom purity solutions and packaging innovations
Standard grades are becoming commoditized, while custom ultra-pure materials and semiconductor-integrated analytical services remain high-margin segments.
About Future Market Insights (FMI)
Future Market Insights, Inc. (FMI) is an ESOMAR-certified, ISO 9001:2015 market research and consulting organization, trusted by Fortune 500 clients and global enterprises. With operations in the U.S., UK, India, and Dubai, FMI provides data-backed insights and strategic intelligence across 30+ industries and 1200 markets worldwide.
Why Choose FMI: Empowering Decisions that Drive Real-World Outcomes: https://www.futuremarketinsights.com/why-fmi



