

Overview
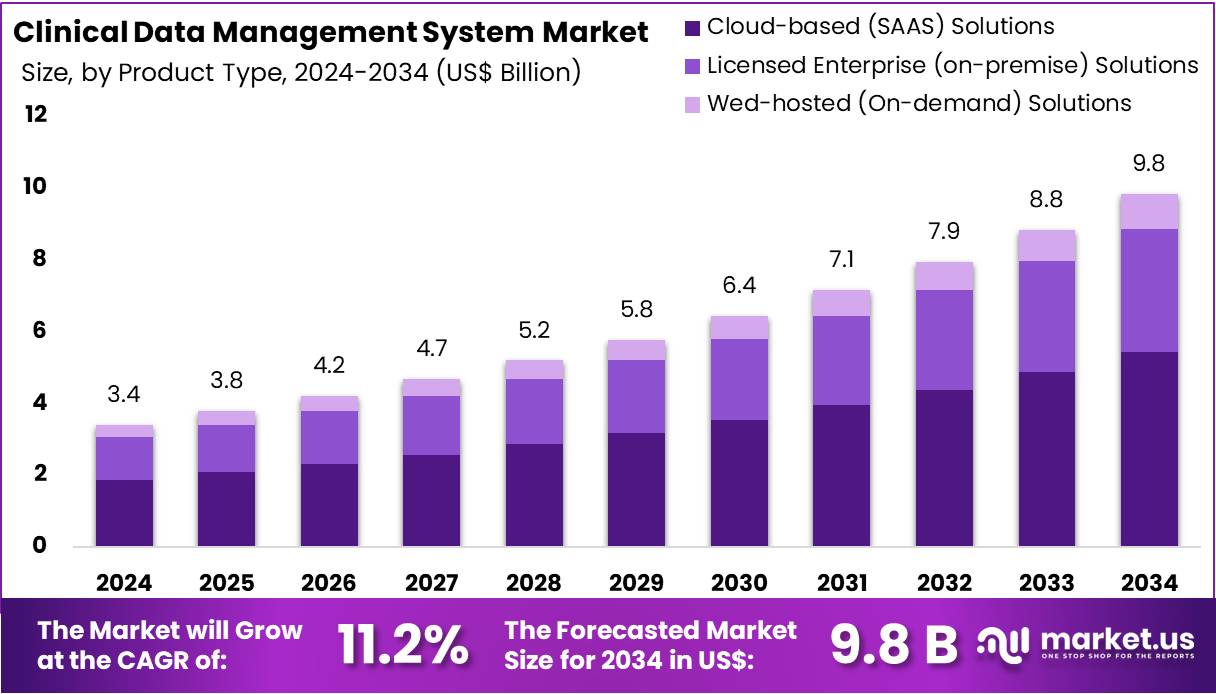
The Global Clinical Data Management System Market is projected to grow significantly over the next decade. It is expected to reach approximately USD 9.8 billion by 2034, rising from USD 3.4 billion in 2024. This expansion represents a robust compound annual growth rate (CAGR) of 11.2% from 2025 to 2034. This growth is mainly driven by the rising demand for efficient handling of clinical trial data and increased adoption of digital health technologies across pharmaceutical and research institutions.
The Clinical Data Management System market is evolving rapidly due to the growing complexity and scale of clinical trials. More organizations are transitioning from paper-based data management to advanced digital platforms. These systems ensure improved accuracy, real-time access, and faster validation of clinical data. Their implementation reduces delays and enhances decision-making during trials. As data requirements become stricter, CDMS platforms play a crucial role in helping sponsors maintain compliance with regulatory authorities such as the FDA and EMA.
The expansion of decentralized and hybrid clinical trial models is also fueling demand for advanced CDMS solutions. These trial formats require seamless data collection from multiple remote locations, making real-time integration and monitoring critical. The rising volume of clinical research worldwide is further contributing to market growth. According to ClinicalTrials.gov, more than 540,000 studies were registered globally across 229 countries as of 2024, indicating strong clinical activity.
Clinical trials now generate massive amounts of sensitive data, including patient demographics, treatment outcomes, and safety evaluations. This makes efficient data management essential. CDMS tools support streamlined data capture, secure storage, and compliance with international standards. Their use enables sponsors and research organizations to maintain high data quality and integrity while meeting global regulatory expectations. These systems are integral to improving the reliability and efficiency of clinical operations.
However, despite the promising growth trajectory, the Clinical Data Management System market faces notable challenges. High implementation costs remain a barrier for smaller institutions. Data interoperability across different platforms and trial phases also poses a significant issue. Concerns related to cybersecurity and data privacy are growing, especially with remote and cloud-based systems becoming more common. Additionally, the need for standardization across platforms can hinder adoption and scalability.
Nonetheless, strategic collaborations between CDMS providers, CROs, and biopharmaceutical firms are driving innovation. These partnerships are helping to create more robust, flexible, and user-friendly platforms. With the rise in chronic diseases and the demand for faster drug development, the importance of reliable data management systems continues to grow. As clinical trials become more data-intensive and globally interconnected, the role of CDMS platforms will be vital in ensuring effective trial execution and successful outcomes.
Key Takeaways
- In 2024, the global clinical data management system market was valued at USD 3.4 billion and is projected to reach USD 9.8 billion by 2034.
- The market is expected to grow at a strong compound annual growth rate (CAGR) of 11.2% throughout the forecast period from 2025 to 2034.
- Cloud-based (SAAS) solutions led the market in 2024, contributing 55.2% to the global revenue due to flexibility, scalability, and remote accessibility.
- Pharma and biotech companies emerged as the primary users in 2024, holding a 44.0% revenue share due to increasing clinical trial activity.
- North America dominated the regional landscape in 2024, accounting for more than 48.2% of the market revenue owing to advanced healthcare infrastructure.
Regional Analysis
North America holds a leading position in the global Clinical Trial Management System market. This dominance is driven by the presence of advanced research institutions, universities, and global pharmaceutical and medical device companies. These organizations rely on CTMS platforms to streamline clinical trial planning, improve monitoring, and ensure regulatory compliance. The region’s well-developed healthcare infrastructure further supports large-scale clinical research. As a result, North America offers optimal conditions for conducting trials and deploying digital tools that enhance trial efficiency and oversight.
In January 2023, the Canadian government introduced several initiatives to strengthen its healthcare research capabilities. These efforts included the launch of national training platforms and the creation of a clinical trial consortium. The initiatives were backed by nearly USD 60.0 million in funding. This funding was used to support 22 clinical trial-related projects. These projects were designed to improve health outcomes and advance Canada’s Biomanufacturing and Life Sciences Strategy (BLSS). This strategy supports the expansion of the country’s clinical research infrastructure.
The Canadian government’s investments highlight a strong national commitment to clinical trial innovation. These projects aim to boost collaboration among researchers and healthcare providers. They also promote the use of advanced technologies in clinical trials. As a result, demand for CTMS solutions in Canada continues to grow. Government support remains a key driver in this upward trend.
Together, these developments reinforce North America’s leadership in the global CTMS market. The combination of government funding, technological innovation, and strong infrastructure fosters long-term growth. The region is expected to maintain its dominant position through continuous investment in research. This supportive environment encourages the broader adoption of CTMS platforms across the clinical research landscape.
Segmentation Analysis
The global Clinical Data Management System (CDMS) market is segmented by product type into cloud-based (SaaS) solutions, licensed enterprise (on-premise) solutions, and web-hosted (on-demand) solutions. Among these, cloud-based (SaaS) solutions held the dominant position in 2024, capturing a 55.2% market share. This growth is mainly due to their cost-effectiveness and flexibility. SaaS platforms allow easy deployment without significant capital investment. They support real-time access, which improves collaboration among research teams. The shift toward digital trials has further fueled the demand for cloud-based CDMS platforms globally.
Cloud-based solutions offer notable benefits, including scalable data storage, seamless integration, and remote access. These features make them ideal for modern decentralized clinical trials. Researchers, sponsors, and CROs can collaborate efficiently from different locations. This enhances trial speed and data accuracy. The demand for remote monitoring and real-time data analytics has made cloud CDMS the preferred choice. As the clinical trial landscape evolves, cloud solutions are expected to remain at the forefront due to their operational advantages and adaptability.
By application, the CDMS market is segmented into pharmaceutical/biotech companies, CROs, medical device firms, and others. In 2024, the pharmaceutical and biotechnology segment led with a 44.0% market share. These companies manage large-scale, complex trials and require reliable platforms for data handling. Regulatory compliance and data precision are crucial, driving their preference for advanced CDMS systems. As drug development becomes more intricate, these firms increasingly invest in digital tools to streamline operations and ensure submission readiness.
Pharma and biotech companies are also embracing AI and ML-enabled CDMS solutions. These technologies help automate data entry, detect errors, and optimize trial workflows. The trend toward personalized medicine and targeted drug development further amplifies the need for robust data platforms. Innovation in rare diseases and oncology is generating complex datasets that require intelligent analysis. Consequently, the dominance of pharma/biotech firms in the CDMS market is expected to strengthen as they continue seeking efficient, scalable, and regulatory-compliant data management solutions.
By Product Type
- Cloud-based (SAAS) Solutions
- Licensed Enterprise (on-premise) Solutions
- Wed-hosted (On-demand) Solutions
By Application
- Pharma/biotech Companies
- Contract Research Organizations (CROs)
- Medical Device Companies
- Others
Key Players Analysis
The global Clinical Data Management System market shows a highly competitive environment. It includes both established companies and innovative new entrants. Key players such as Oracle Corporation, Medidata Solutions, Veeva Systems, IBM Watson Health, and eClinical Solutions LLC are leading the space. These companies offer end-to-end platforms that support clinical trial processes. Services include data capture, validation, and analysis. Their integrated solutions enhance workflow efficiency and improve data integrity. The demand for scalable, compliant systems continues to drive growth in this sector.
Technology is a crucial enabler in this market. Major players use artificial intelligence (AI), machine learning (ML), and cloud computing to boost system performance. These technologies improve data accuracy and reduce operational complexity. They also assist with meeting regulatory standards across regions. The adoption of cloud-based systems allows real-time access and scalability. This is especially important for global trials. Vendors are also investing in automation to speed up data handling and minimize human error.
Specialized companies are gaining visibility in this space. CluePoints is a prominent example. The company focuses on risk-based quality management and advanced analytics. Their tools help monitor data anomalies and reduce trial risks. These solutions are being increasingly adopted for their role in improving trial oversight. Niche providers are complementing traditional CDMS offerings through innovation.
Veeva Systems Inc. is a leader in life sciences software solutions. It provides cloud-based platforms for clinical trials, quality management, and regulatory compliance. Its core products, including Veeva Vault and Veeva Clinical Suite, support collaboration and standardized data flow. The company addresses the unique needs of pharma and biotech firms. Oracle Corporation, a global technology leader, offers database and cloud-based data solutions. Oracle’s tools, especially Oracle Database, are widely used in clinical data operations for their robustness and flexibility.
Get in Touch with Us:
Market.us (Powered By Prudour Pvt. Ltd.)
Address: 420 Lexington Avenue, Suite 300, New York City, NY 10170, United States.
Contact No: +1 718 874 1545 (International), +91 78878 22626 (Asia).
Email: [email protected]
View More
Veterinary Telehealth Market
Pharmaceutical Quality Management Software Market



