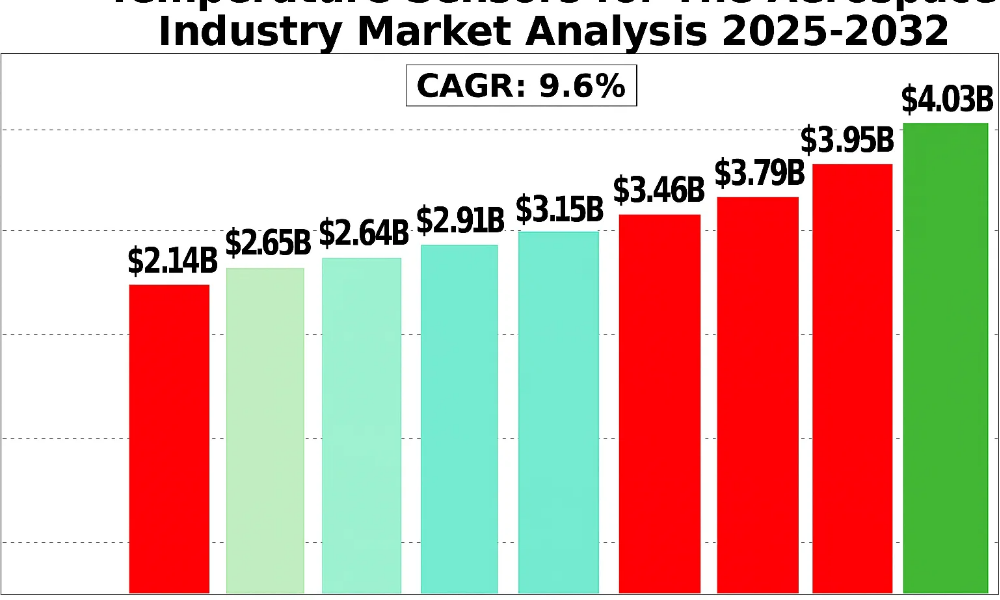
Temperature Sensors for The Aerospace Industry Market size was valued at US$ 2.14 billion in 2024 and is projected to reach US$ 4.03 billion by 2032, at a CAGR of 9.6% during the forecast period 2025-2032
The global Temperature Sensors for The Aerospace Industry Market size was valued at US$ 2.14 billion in 2024 and is projected to reach US$ 4.03 billion by 2032, at a CAGR of 9.6% during the forecast period 2025-2032.
Temperature sensors in aerospace are critical components that monitor environmental and system temperatures to ensure operational safety and performance. These devices include thermocouples, resistive temperature detectors (RTDs), infrared sensors, and other specialized variants. They are deployed across aircraft engines, avionics systems, cabin environments, and structural components to provide real-time thermal data for flight control systems.
Market growth is driven by increasing aircraft production rates and technological advancements in sensor miniaturization. Airbus plans to increase A320 production to 75 units monthly by 2025, up from 60 in 2019, directly boosting sensor demand. The global aerospace industry generated USD 386.4 billion revenue in 2021 (4.1% YoY growth), with military modernization programs and commercial fleet expansions further accelerating adoption. Key players like Honeywell, TE Connectivity, and Collins Aerospace are developing high-precision sensors with enhanced durability for extreme aerospace conditions.
Download Free Sample Report: https://semiconductorinsight.com/download-sample-report/?product_id=107446
MARKET DRIVERS
Rising Aircraft Production and Fleet Expansion to Fuel Temperature Sensor Demand
The commercial aerospace sector is witnessing robust growth, with Airbus and Boeing ramping up production rates to meet pent-up demand post-pandemic. Airbus increased production of its A320 family to 65 units per month in 2023, with plans to reach 75 per month by 2025 – up from just 40 during the pandemic lows. This production surge directly correlates with increased demand for temperature sensors used in engine monitoring, environmental control systems, and avionics cooling. Each new generation aircraft requires 15-20% more sensors than previous models due to enhanced monitoring requirements, creating substantial market opportunities.
Aviation Safety Regulations Mandating Advanced Monitoring Systems
Strict aviation safety standards are compelling manufacturers to incorporate more sophisticated temperature monitoring solutions. The Federal Aviation Administration (FAA) and European Union Aviation Safety Agency (EASA) have introduced regulations requiring real-time temperature monitoring in critical aircraft systems. These regulations are driving adoption of smart temperature sensors with predictive analytics capabilities. Recent accidents attributed to thermal runaway in lithium-ion batteries have further accelerated regulatory focus, with the aerospace temperature sensor market expected to benefit from these mandated upgrades across commercial and military fleets.
Recent Development:
Distributed fiber / FBG sensing for high-temperature, high-speed flight
Why: immune to EMI, can measure temperature and strain along structure, thin/light for hypersonic skins and rocket structures.
Evidence: NASA FOSS flight program and industry market reports.
High-temperature materials & sensors for hypersonics and reentry
Development of sensors (thin-film, ceramic encapsulation, high-temp FBGs or strain-temp sensors) that tolerate extreme heating and thermal gradients during reentry or sustained hypersonic flight. NASA and hypersonic researchers have active programs testing these.
MARKET OPPORTUNITIES
Emerging Electric Aircraft Market Creating Demand for Next-Gen Sensors
The burgeoning electric vertical takeoff and landing (eVTOL) and hybrid-electric aircraft market represents a significant growth opportunity. These aircraft require specialized temperature monitoring systems for high-voltage battery packs, electric motors, and power electronics. Current estimates suggest each eVTOL aircraft will need 40-60% more temperature sensors than conventional helicopters, with the global eVTOL market projected to reach $30 billion by 2030. Sensor manufacturers investing in high-voltage compatible, lightweight solutions stand to gain substantial market share as these aircraft enter commercial service.
Additionally, the increasing adoption of additive manufacturing in aerospace enables new sensor integration approaches. Embedded temperature sensors in 3D-printed components are opening possibilities for distributed temperature monitoring that were previously impractical.
List of Key Temperature Sensor Providers for Aerospace
- Honeywell International Inc. (U.S.)
- TE Connectivity Ltd. (Switzerland)
- Collins Aerospace (U.S.)
- Meggitt Sensing Systems (U.K.)
- Conax Technologies (U.S.)
- TT Electronics (U.K.)
- IST AG (Switzerland)
- Thermocoax (France)
- Emerson Electric Co. (U.S.)
- Ametek Fluid Management Systems (U.S.)
- San Giorgio S.E.I.N. s.r.l. (Italy)
- Minco (U.S.)
Segment Analysis:
By Type
Thermocouple Segment Dominates Due to High Accuracy and Durability in Extreme Aerospace Conditions
The market is segmented based on type into:
- Thermocouple
- Subtypes: Type K, Type J, Type T, and others
- Resistive Type
- Subtypes: RTDs (Resistance Temperature Detectors), Thermistors, and others
- Infrared
- Others
By Application
Military Aircraft Segment Leads Due to Critical Temperature Monitoring Requirements
The market is segmented based on application into:
- Military Aircraft
- Civil Aircraft
- Spacecraft
- Unmanned Aerial Vehicles (UAVs)
- Others
By End User
OEMs Maintain Largest Market Share Due to Direct Integration in Aircraft Manufacturing
The market is segmented based on end user into:
- OEMs (Original Equipment Manufacturers)
- MRO (Maintenance, Repair and Overhaul) Providers
- Airlines
- Space Agencies
By Aircraft Type
Commercial Aviation Leads with Rising Passenger Traffic and Fleet Expansion
The market is segmented based on aircraft type into:
- Narrow-body Aircraft
- Wide-body Aircraft
- Regional Jets
- Business Jets
- Military Aircraft
Download Free Sample Report: https://semiconductorinsight.com/download-sample-report/?product_id=107446
Report Scope
This market research report provides a comprehensive analysis of the global and regional Temperature Sensors for The Aerospace Industry market, covering the forecast period 2024–2032. It offers detailed insights into market dynamics, technological advancements, competitive landscape, and key trends shaping the industry.
Key focus areas of the report include:
- Market Size & Forecast: Historical data and future projections for revenue, unit shipments, and market value across major regions and segments. The market was valued at US$ 2.14 billion in 2024 and is projected to reach US$ 4.03 billion by 2032, growing at a CAGR of 9.6%.
- Segmentation Analysis: Detailed breakdown by product type (thermocouple, resistive, infrared), application (military aircraft, civil aircraft), and end-user industry to identify high-growth segments.
- Regional Outlook: Insights into market performance across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa, with country-level analysis of key markets like the US, China, and Germany.
- Competitive Landscape: Profiles of 25+ leading market participants including Honeywell, TE Connectivity, and Collins Aerospace, covering their product portfolios, market share (top 5 players hold 35% share), and strategic developments.




