
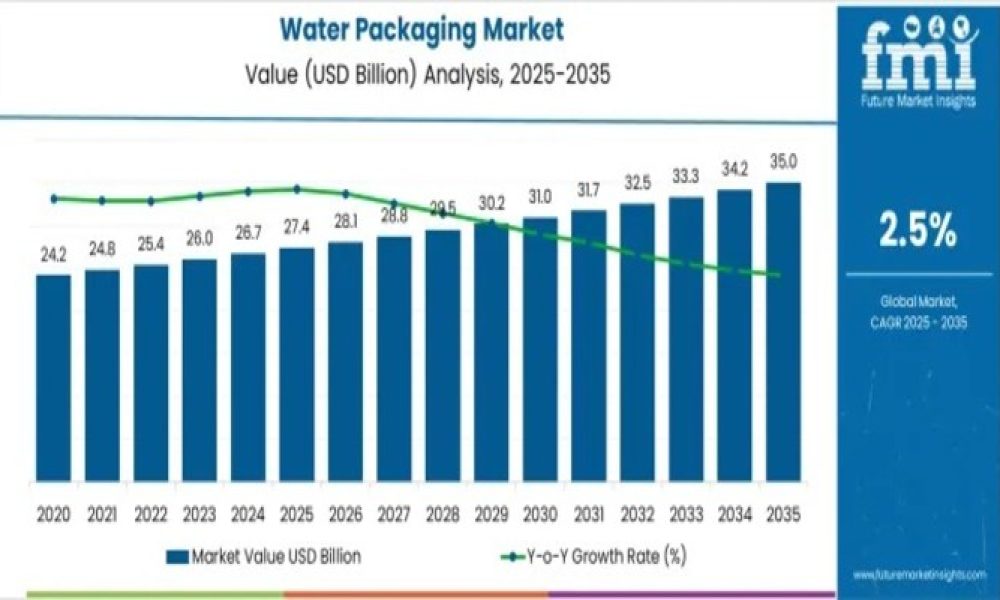
The global Water Packaging Market is entering a phase of steady, resilience-driven growth as consumer demand for safe, portable, and hygienic drinking water solutions continues to rise worldwide. Valued at USD 27.4 billion in 2025, the market is projected to reach USD 35.0 billion by 2035, expanding at a compound annual growth rate (CAGR) of 2.5% during the forecast period.
This growth trajectory reflects structural shifts in consumer behavior, including increased health consciousness, rapid urbanization, and a preference for on-the-go hydration. Across households, workplaces, recreational venues, and travel environments, packaged water has become a daily essential rather than an occasional purchase.
Unlock Growth Potential – Request Your Sample Now and Explore Market Opportunities!
Market Momentum Driven by Safety, Convenience, and Innovation
The water packaging industry is benefiting from sustained investments in advanced packaging technologies, including tamper-evident seals, lightweight designs, and improved barrier properties that enhance shelf life and product integrity. Regulatory emphasis on water quality, labeling accuracy, and food safety compliance is further reinforcing adoption, encouraging manufacturers to implement robust quality management systems.
At the same time, sustainability is reshaping competitive strategies. Circular economy initiatives, recyclable materials, and biodegradable packaging solutions are increasingly central to long-term growth plans, ensuring environmental alignment without compromising performance or cost efficiency.
Quick Stats: Water Packaging Market at a Glance
- Market Value (2025): USD 27.4 billion
- Forecast Value (2035): USD 35.0 billion
- Forecast CAGR (2025–2035): 2.5%
- Leading Packaging Format (2025): Bottles – 61.2% share
- Leading Material (2025): Plastic – 59.6% share
- Top Growth Regions: North America, Asia-Pacific, Europe
- Key Players: Tetra Pak International, Elopak, SIG Group, Stora Enso Oyj, Sidel International, Silgan Holdings, LamiPak, Adam Pack
Bottles Dominate Packaging Formats
The bottle packaging format is projected to account for 61.2% of total market revenue in 2025, making it the most dominant format across global markets. Bottles remain the preferred choice due to their portability, ease of handling, secure sealing, and compatibility with both carbonated and non-carbonated water.
Technological advancements in ergonomic and lightweight bottle designs are improving logistics efficiency and consumer convenience, while scalable manufacturing capabilities enable consistent quality across retail and commercial distribution channels. Sustainability efforts—such as increased use of recycled plastics—are further strengthening the long-term viability of bottles as the leading format.
Plastic Remains the Material of Choice
By material, plastic packaging is expected to hold 59.6% of market revenue in 2025, driven by its lightweight nature, durability, cost efficiency, and versatility. Plastic allows for tamper-evident closures, extended shelf life, and mass production at lower operational costs, making it ideal for large-scale distribution.
Ongoing innovations in food-grade, recyclable, and bio-based plastics are helping manufacturers balance performance with environmental responsibility. Reduced transportation emissions due to lighter weight also support sustainability goals, reinforcing plastic’s leadership position.
Everyday Consumption Leads End-Use Demand
The everyday end-use segment is projected to capture 41.8% of market revenue in 2025, reflecting the integration of packaged water into daily routines at home, work, and during commutes. Urbanization, lifestyle shifts, and heightened hygiene awareness are driving consistent demand.
Manufacturers are responding with diverse bottle sizes, improved closures, and widespread retail availability across supermarkets, convenience stores, vending machines, and e-commerce platforms—ensuring accessibility and convenience for consumers.
Regional Growth Highlights
- India: Fastest growth at 6.5% CAGR, fueled by urbanization, e-commerce expansion, and rising health awareness
- China: Strong growth at 5.7% CAGR, driven by safety concerns around tap water and demand for single-serve formats
- United States: Stable growth at 2.3% CAGR, supported by hydration awareness and single-serve bottle demand
- United Kingdom: 2.5% CAGR, shaped by sustainability initiatives and preference for functional and flavored waters
- Japan: 2.6% CAGR, boosted by tourism and demand for premium bottled water
Key Market Trends and Highlights
- Growing adoption of smart packaging technologies for traceability and transparency
- Rising demand for eco-friendly and recyclable packaging materials
- Increased popularity of single-serve and portable packaging formats
- Expansion of functional and wellness-oriented water products
Competitive Landscape and Outlook
The water packaging market remains highly fragmented and competitive, with global and regional players focusing on product quality, regulatory compliance, and sustainability leadership. Companies such as Tetra Pak and Elopak are advancing carton-based alternatives, offering lightweight, recyclable solutions that appeal to environmentally conscious consumers.
Why FMI: https://www.futuremarketinsights.com/why-fmi
About Future Market Insights (FMI)
Future Market Insights, Inc. (FMI) is an ESOMAR-certified, ISO 9001:2015 market research and consulting organization, trusted by Fortune 500 clients and global enterprises. With operations in the U.S., UK, India, and Dubai, FMI provides data-backed insights and strategic intelligence across 30+ industries and 1200 markets worldwide.



