Definition
The Global Silicon Carbide (SiC) Discrete Product Market represents one of the most transformative segments within the global power electronics industry. Silicon Carbide (SiC) is a compound semiconductor material composed of silicon and carbon atoms, known for its exceptional thermal conductivity, high breakdown voltage, and ability to operate efficiently at elevated temperatures and frequencies. SiC discrete products—such as SiC diodes, MOSFETs, and thyristors—are used to manage and convert power efficiently across a range of demanding applications, including electric vehicles (EVs), renewable energy systems, industrial motor drives, and power supply units.
Unlike conventional silicon-based devices, SiC-based components exhibit significantly lower switching losses, higher energy efficiency, and superior reliability under high-voltage conditions. This makes them ideal for next-generation power conversion systems, where energy efficiency, compact design, and thermal stability are critical. The growing adoption of SiC technology is not limited to automobiles alone—it extends to grid infrastructure modernization, aerospace, defense electronics, and rail transportation. SiC discrete devices are essential in enabling the shift toward sustainable electrification, reducing carbon emissions, and supporting global initiatives for net-zero energy systems.
The ongoing industrial transformation, characterized by the proliferation of smart manufacturing, IoT integration, and energy-efficient automation, further emphasizes the importance of SiC discrete components. These products are now seen as cornerstone technologies enabling faster, smaller, and more energy-efficient devices that can handle higher loads with reduced cooling requirements. As industries across the globe aim for decarbonization and digitalization, SiC discrete devices are emerging as the preferred choice for efficient and reliable power conversion.
Get Full Report Here:
Market Size
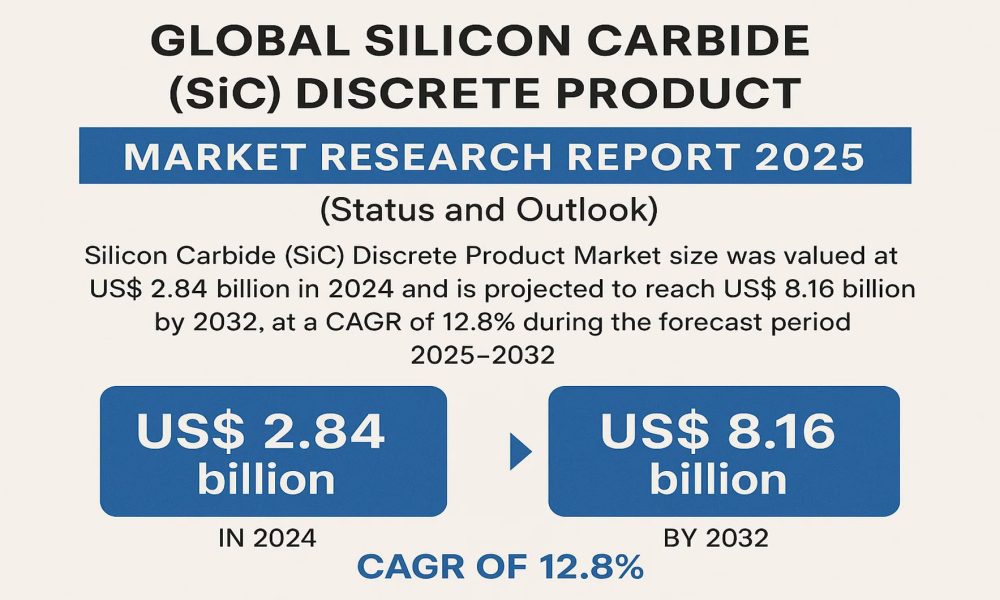
Global Silicon Carbide (SiC) Discrete Product Market is experiencing a period of remarkable expansion. Valued at US$ 2.84 billion in 2024, it is projected to reach an impressive US$ 8.16 billion by 2032, reflecting a strong compound annual growth rate (CAGR) of 12.8% from 2025 to 2032. This growth trajectory underscores the accelerating adoption of SiC devices across industries that demand high power density and efficiency.
A significant portion of this growth is attributed to the electric vehicle (EV) industry, which has become the largest consumer of SiC discrete components, accounting for over 42% of total market revenue in 2024. The ongoing transition to 800V EV architectures requires components capable of withstanding higher voltages and temperatures, areas where SiC technology outperforms conventional silicon solutions. With global EV production expected to exceed 40 million units annually by 2030, demand for SiC MOSFETs and diodes will continue to soar.
In addition, renewable energy applications—particularly in solar inverters, wind turbines, and energy storage systems—are contributing significantly to market growth. SiC-based devices improve system efficiency and power density, making renewable installations more compact and cost-effective. The industrial automation and rail traction sectors are also seeing increased integration of SiC-based components for their superior endurance and switching capabilities.
From a macroeconomic standpoint, global decarbonization initiatives, investments in smart grids, and electrification of transport and manufacturing are reinforcing the long-term demand outlook. Asia-Pacific dominates the market, driven by rapid industrialization, EV adoption, and the expansion of semiconductor manufacturing capacity. Collectively, these factors establish SiC discrete products as a vital enabler of the global energy transition.
Regional Analysis
Asia-Pacific: The Dominant Force
The Asia-Pacific (APAC) region commands more than 65% of the global SiC discrete product market, with countries like China, Japan, and South Korea leading in both production and consumption. The region’s dominance stems from its strong EV manufacturing base, robust semiconductor fabrication ecosystem, and government-backed policies promoting clean energy. China’s aggressive push toward electrification—supported by massive investments exceeding US$ 300 billion in EV infrastructure—continues to drive SiC demand. Meanwhile, Japan’s semiconductor leaders, including ROHM and Toshiba, are pioneering technological innovations that enhance performance and scalability.
North America: Innovation and Industrial Growth
North America, led by the United States, is witnessing significant expansion fueled by EV adoption, renewable integration, and industrial automation. The presence of major SiC players like Wolfspeed, ON Semiconductor, and Microchip Technology has positioned the region as a global innovation hub. Federal incentives and investments in clean energy infrastructure, combined with collaborations between automotive giants and semiconductor manufacturers, are further accelerating the adoption of SiC discrete components across multiple sectors.
Europe: Pioneering Sustainable Electrification
Europe remains at the forefront of sustainability-driven innovation. Countries such as Germany, France, and Sweden are leading in EV manufacturing and renewable integration. European companies like Infineon Technologies and STMicroelectronics are expanding their SiC production capacities to meet surging demand from the automotive and industrial sectors. The European Green Deal and stringent energy efficiency regulations have also boosted market adoption of SiC technology for applications in charging infrastructure, rail transport, and renewable energy grids.
Rest of the World: Emerging Opportunities
Regions such as the Middle East, Africa, and Latin America are gradually entering the SiC landscape. Growing investments in solar power generation, smart grid development, and transportation electrification are expected to open new opportunities. While still nascent compared to established markets, these regions are poised to become important contributors to global SiC demand as industrial and energy modernization accelerates.
Competitor Analysis (in brief)
The competitive landscape of the global SiC discrete product market is defined by rapid technological advancements, strategic partnerships, and large-scale capacity expansions. Industry leaders are focusing on vertical integration, from raw SiC wafer production to final device fabrication, ensuring better control over quality, cost, and supply chain resilience.
- Infineon Technologies AG (Germany) – A leading innovator in SiC MOSFET technology, emphasizing high-voltage automotive and industrial applications.
- Wolfspeed, Inc. (U.S.) – The global pioneer in SiC wafer manufacturing, recently expanding its 200mm wafer production facilities to meet exponential market demand.
- ROHM Semiconductor (Japan) – Focused on automotive-grade SiC devices, partnering with major OEMs to enable next-generation EV platforms.
- STMicroelectronics (Switzerland) – A key supplier of SiC power modules for leading EV manufacturers, expanding SiC production capacity in Italy and Singapore.
- ON Semiconductor (U.S.) – Strengthening its SiC portfolio through acquisitions and alliances aimed at the automotive and renewable energy sectors.
- Mitsubishi Electric, Toshiba, and Fuji Electric (Japan) – Major contributors to industrial power applications and smart grid solutions.
- Microchip Technology and Littelfuse (U.S.) – Known for innovation in power management and protection devices using SiC-based technology.
- BASiC Semiconductor (China) and ASCatron (Sweden) – Emerging players focusing on customized high-performance SiC devices.
The industry is witnessing a wave of mergers, acquisitions, and collaborations designed to enhance technological capabilities, reduce production costs, and accelerate the transition to larger SiC wafer sizes (200mm). These competitive dynamics are expected to intensify as demand continues to outpace supply globally.
Global Silicon Carbide (SiC) Discrete Product Market: Market Segmentation Analysis
This report provides a deep insight into the global Silicon Carbide (SiC) Discrete Product Market, covering all its essential aspects. This ranges from a macro overview of the market to micro details of the market size, competitive landscape, development trend, niche market, key market drivers and challenges, SWOT analysis, value chain analysis, etc.
The analysis helps the reader to shape the competition within the industries and strategies for the competitive environment to enhance the potential profit. Furthermore, it provides a simple framework for evaluating and assessing the position of the business organization. The report structure also focuses on the competitive landscape of the Global Silicon Carbide (SiC) Discrete Product Market. This report introduces in detail the market share, market performance, product situation, operation situation, etc., of the main players, which helps the readers in the industry to identify the main competitors and deeply understand the competition pattern of the market.
In a word, this report is a must-read for industry players, investors, researchers, consultants, business strategists, and all those who have any kind of stake or are planning to foray into the Silicon Carbide (SiC) Discrete Product Market in any manner.
Download FREE Sample Report:Global Silicon Carbide (SiC) Discrete Product Market – View in Detailed Research Report
Market Segmentation (by Application)
- Electric Vehicles & Charging Infrastructure
- Industrial Motor Drives
- Renewable Energy Systems
- Power Supplies
- Rail Traction
- UPS Systems
Market Segmentation (by Type)
- SiC MOSFETs
- SiC Diodes
- SiC Thyristors
- Other Discrete Products
Key Company
- Infineon Technologies AG (Germany)
- Wolfspeed, Inc. (U.S.)
- ROHM Semiconductor (Japan)
- STMicroelectronics (Switzerland)
- ON Semiconductor (U.S.)
- Toshiba Electronic Devices & Storage Corporation (Japan)
- Mitsubishi Electric Corporation (Japan)
- Microchip Technology Inc. (U.S.)
- GeneSiC Semiconductor Inc. (U.S.)
- Fuji Electric Co., Ltd. (Japan)
- Littelfuse, Inc. (U.S.)
- BASiC Semiconductor (China)
- SanRex Corporation (Japan)
- ASCatron (Sweden)
Geographic Segmentation
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East & Africa
Download FREE Sample Report:Global Silicon Carbide (SiC) Discrete Product Market – View in Detailed Research Report
FAQ
Q1. What is the current market size of the Silicon Carbide (SiC) Discrete Product Market?
The market is valued at US$ 2.84 billion in 2024 and is projected to reach US$ 8.16 billion by 2032, growing at a CAGR of 12.8%.
Q2. Which are the key companies operating in the Silicon Carbide (SiC) Discrete Product Market?
Major players include Infineon Technologies, Wolfspeed, ROHM Semiconductor, STMicroelectronics, and ON Semiconductor, among others.
Q3. What are the key growth drivers in the Silicon Carbide (SiC) Discrete Product Market?
The main drivers include the rapid adoption of electric vehicles, renewable energy expansion, smart grid modernization, and demand for high-efficiency power electronics.
Q4. Which regions dominate the Silicon Carbide (SiC) Discrete Product Market?
The Asia-Pacific region leads the global market, accounting for over 65% of total consumption, followed by North America and Europe.
Q5. What are the emerging trends in the Silicon Carbide (SiC) Discrete Product Market?
Emerging trends include the shift toward 200mm wafer production, integration of SiC in 800V EV architectures, and strategic collaborations between semiconductor manufacturers and automotive OEMs to scale production and innovation.




