
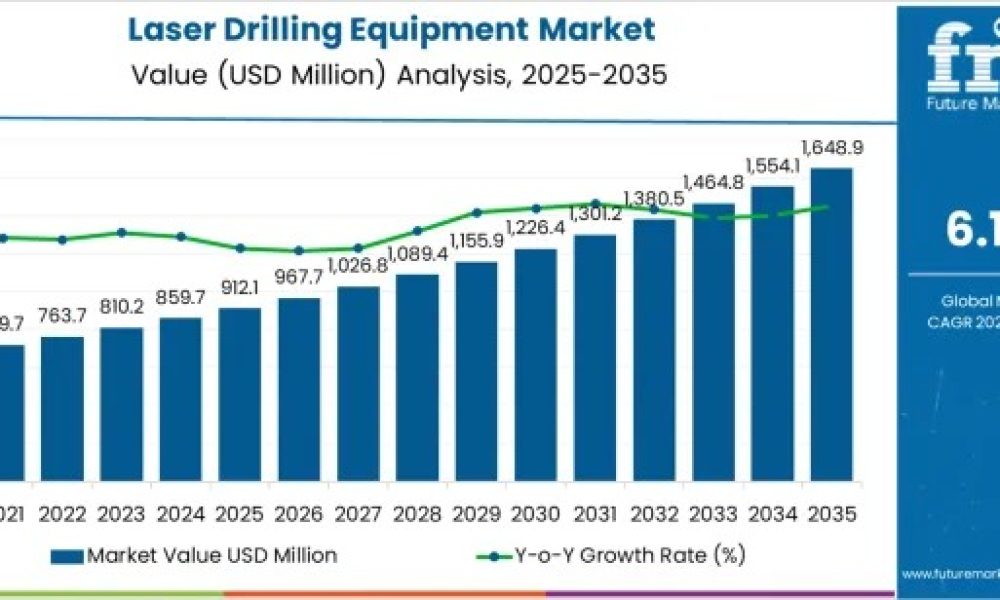
The Laser Drilling Equipment Market is entering a robust growth phase, projected to expand from USD 912.1 million in 2025 to USD 1,648.9 million by 2035 at a CAGR of 6.1%. Increasing adoption of precision manufacturing across aerospace, automotive, electronics, and energy sectors is driving demand for high-accuracy, non-contact machining solutions. Fiber and ultrafast laser technologies are dominating the market due to their superior beam quality, energy efficiency, and seamless integration into automated production lines.
Subscribe for Year-Round Insights → Stay ahead with quarterly and annual data updates: https://www.futuremarketinsights.com/reports/sample/rep-gb-27680
A key driver of this market is the shift from traditional mechanical drilling to laser-based systems, enabling faster throughput, reduced thermal distortion, and higher precision. Multi-axis laser platforms are increasingly deployed in aerospace turbine blade manufacturing, PCB fabrication, and battery component production. Automation and AI-assisted calibration enhance micro-drilling accuracy, improve repeatability, and reduce rework, particularly in electronics and semiconductor industries.
Material versatility is another growth factor. Laser drilling equipment can now process titanium alloys, carbon fiber composites, and sapphire substrates with minimal edge damage. Hybrid solutions combining laser with water-jet or plasma assistance are emerging to address thicker or layered material challenges. Manufacturers are adopting modular designs, offering flexible system scaling and easier maintenance, while compact architectures support space-constrained and cleanroom environments.
Regional Insights and Growth Patterns
Asia Pacific leads the market, driven by electronics and consumer device production, while North America and Europe dominate aerospace and automotive component manufacturing. China is the fastest-growing market at 8.2% CAGR, fueled by government-backed industrial modernization programs and high-speed system adoption. India follows at 7.6% CAGR, with manufacturing hubs like Bangalore, Mumbai, and Chennai implementing advanced laser systems under “Make in India” initiatives.
Germany maintains technology leadership at a 7.0% CAGR, leveraging engineering expertise and integration of advanced laser systems into automotive and aerospace production. Brazil grows steadily at 6.4% CAGR, emphasizing cost-effective solutions for diversified industrial needs, while North America benefits from aerospace investment and precision manufacturing infrastructure. Japan and South Korea are advancing laser drilling adoption in electronics and automotive sectors through high-precision, automated systems.
Market Segmentation
By laser type, fiber laser drilling equipment dominates with a 54% market share, thanks to superior precision, operational efficiency, and integration with automated production lines. CO2 laser systems account for 32% of the market, ideal for thicker materials and high-volume industrial applications, while other laser systems (14%) cater to niche R&D, prototype development, and advanced material processing.
By application, aerospace leads with 40% market share, driven by turbine blade drilling and lightweight material processing. Medical equipment accounts for 25%, emphasizing implant and surgical instrument precision. Automotive applications hold 20%, focused on fuel injection, engine, and transmission component drilling.
Industry Trends and Market Drivers
- Drivers: Aerospace modernization programs, medical device precision, and automotive lightweighting with advanced materials.
- Restraints: High capital investment, multi-material compatibility challenges, and process validation complexity.
- Trends: Industry 4.0 integration, miniaturization, micro-drilling, and real-time process analytics.
Competitive Landscape
The market is moderately consolidated, with top players holding 62–68% revenue share. Leading manufacturers include IPG Photonics Corporation, KLA Corporation, Mitsubishi Electric, Hitachi, and TZTEK. Vendors differentiate via precision technology, application engineering, and comprehensive service networks. Emerging opportunities focus on digital solutions, predictive maintenance, and subscription-based performance services. Regional specialists leverage proximity and cost-effective support to capture mid-sized manufacturing clients.
Strategic Recommendations for Stakeholders
- Invest in automated, precision-ready systems for aerospace and medical applications.
- Adopt digital monitoring and predictive maintenance capabilities.
- Offer value-based pricing, validation packages, and subscription models for analytics and services.
Get data that aligns with your strategic priorities — ask for report customization today: https://www.futuremarketinsights.com/customization-available/rep-gb-27680
Have a specific Requirements and Need Assistant on Report Pricing or Limited Budget please contact us – [email protected]
About Future Market Insights (FMI)
Future Market Insights, Inc. (FMI) is an ESOMAR-certified, ISO 9001:2015 market research and consulting organization, trusted by Fortune 500 clients and global enterprises. With operations in the U.S., UK, India, and Dubai, FMI provides data-backed insights and strategic intelligence across 30+ industries and 1200 markets worldwide.
Contact Us:
Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531



