
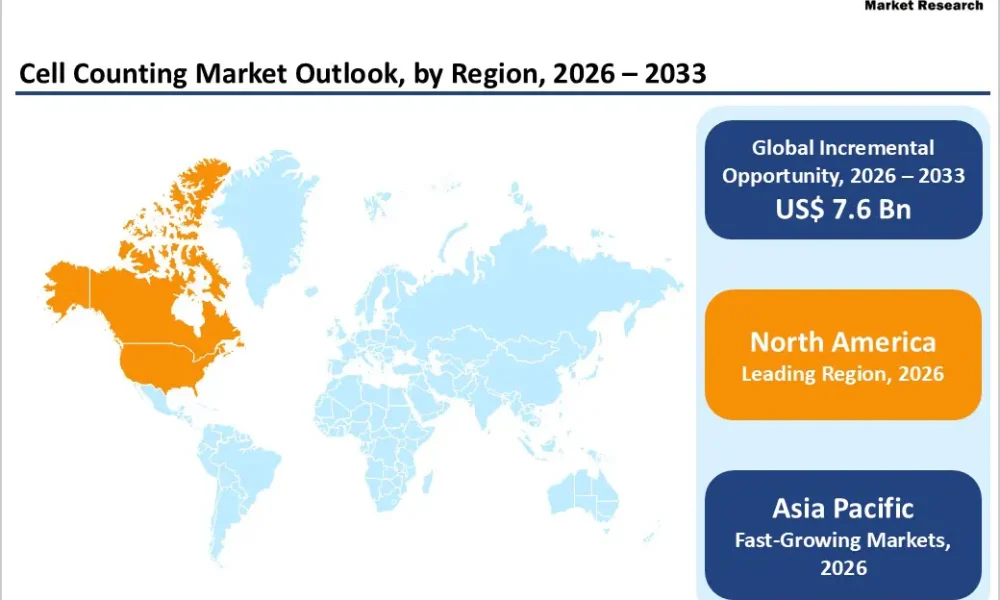
The global cell counting market is poised for substantial growth, with the market size projected to increase from US$ 11.8 billion in 2026 to US$ 19.4 billion by 2033, reflecting a compound annual growth rate (CAGR) of 6.1% during the forecast period. Rising demand for precise, high-throughput cell analysis is being fueled by expanding diagnostic testing volumes, growing biomedical research, and the accelerated adoption of automated laboratory technologies. The increasing prevalence of chronic diseases such as cancer, hematological disorders, autoimmune conditions, and infectious diseases has amplified routine testing requirements, including complete blood count and immune profiling assays. Aging populations and a heightened focus on preventive healthcare further underpin market growth.
Cell counting solutions are extensively utilized across hospitals, diagnostic laboratories, research institutes, and biopharmaceutical facilities to deliver reliable and reproducible results efficiently. Investment in life sciences research, drug discovery, and bioprocessing is reinforcing global adoption, while the expansion of contract research organizations, academic collaborations, and clinical trial activity continues to drive sustained market growth. Technological advancements, including automated and image-based cell counters, fluorescence detection, AI-assisted analysis, and digital data integration, are enhancing accuracy, workflow efficiency, and laboratory productivity. Additionally, increasing healthcare infrastructure and research investments in emerging markets, alongside rising public and private funding for biotechnology and genomics, are further strengthening long-term demand for cell counting solutions.
Download Your Free Sample & Explore Key Insights: https://www.persistencemarketresearch.com/samples/33176
Key Industry Highlights
Leading Region: North America holds the largest share of 47.3%, supported by advanced healthcare infrastructure, high diagnostic testing volumes, robust biomedical research funding, widespread adoption of automated laboratory systems, and the presence of major life sciences companies.
Fastest-Growing Region: Asia Pacific is witnessing the fastest growth due to increasing healthcare expenditure, expanding diagnostic access, rapid growth of pharmaceutical and biotechnology sectors, flourishing academic research activity, and government initiatives supporting life sciences.
Leading Product Segment: Consumables and accessories dominate the market due to recurring usage, regulatory requirements, high testing frequency, and their essential role across clinical, research, and bioprocessing workflows.
Fastest-Growing Product Segment: Instruments are rapidly gaining traction as laboratories adopt automated and image-based systems to improve accuracy, throughput, and operational efficiency.
Leading Application Segment: Complete blood count (CBC) remains the most prominent application, driven by high routine diagnostic volumes and its critical role in disease detection and monitoring.
Fastest-Growing Application Segment: Cell-based therapeutics is expanding quickly as cell and gene therapy development escalates demand for precise cell quantification throughout manufacturing and clinical stages.
Market Size and Forecast: The market is expected to grow from US$ 11.8 billion in 2026 to US$ 19.4 billion by 2033, with a projected CAGR of 6.1%. Historically, the market recorded a CAGR of 5.2% between 2020 and 2025.
Market Dynamics
Drivers – Rising Diagnostic Volumes, Expansion of Cell-Based Research, and Laboratory Automation: The market growth is primarily driven by the increasing need for accurate, high-throughput cell analysis across clinical diagnostics, biomedical research, and biopharmaceutical production. Rising prevalence of chronic and lifestyle-related diseases, along with aging populations and preventive healthcare measures, has elevated routine diagnostic testing volumes, particularly for CBC and immune profiling assays. Expansion of cell-based research, including stem cell studies, regenerative medicine, and cell and gene therapy, is accelerating adoption in research and academic settings. Accurate cell quantification is vital throughout drug discovery, toxicity testing, and bioprocess monitoring, supporting the use of both instruments and consumables. Technological advancements such as automated cell counters, image-based analysis, fluorescence detection, and integration with laboratory information systems have improved accuracy, reproducibility, and workflow efficiency, reducing manual errors, shortening turnaround times, and enabling high-throughput laboratory operations. Continued investment in biotechnology, pharmaceutical R&D, and translational research globally further reinforces long-term market momentum.
Restraints – High Equipment Costs, Technical Complexity, and Regulatory Compliance Burden: Despite growth potential, the market faces constraints, primarily due to the high upfront cost of advanced automated and image-based instruments, which can limit adoption among small laboratories, academic institutes, and facilities in cost-sensitive regions. Ongoing expenses for consumables, calibration, software updates, maintenance, and service contracts increase the total cost of ownership. Technical complexity and the requirement for skilled personnel pose additional challenges, as advanced platforms demand trained professionals for accurate operation, data interpretation, and adherence to standardized protocols. Regulatory requirements for diagnostic validation, quality control, and data integrity further increase operational complexity. In emerging markets, limited laboratory infrastructure, lower awareness of advanced tools, and affordability constraints can restrict adoption. Variability in regional regulatory frameworks may delay product approvals and elevate compliance costs for manufacturers, slowing market penetration.
Opportunities – Growth in Emerging Markets, Advanced Automation, and Cell & Gene Therapy Expansion: Emerging economies present significant growth opportunities due to expanding healthcare infrastructure and increased research investments. Development of diagnostic laboratories, academic research centers, and pharmaceutical manufacturing hubs across Asia Pacific, Latin America, and the Middle East is driving demand for scalable cell counting solutions. Government support for biotechnology, genomics, and life sciences research further encourages adoption. Technological advancements emphasizing automation, artificial intelligence, and real-time analytics offer additional opportunities. Compact, user-friendly, fully automated cell counters reduce operator dependency and enhance consistency, making them suitable for high-throughput and decentralized laboratories. Integration with digital platforms and cloud-based data management optimizes workflows and ensures compliance. Growth in cell and gene therapy development amplifies the need for precise cell counting across manufacturing, quality control, and clinical trials. Expansion of bioprocessing, contract research organizations, and biologics production reinforces demand, while strategic collaborations between manufacturers, research institutions, and biopharma companies accelerate innovation, standardization, and long-term market expansion.
Get Custom Insights Designed for Your Businecss: https://www.persistencemarketresearch.com/request-customization/33176
Category-Wise Analysis
By Product – Consumables & Accessories Dominate Due to Recurring Usage: Consumables and accessories are expected to capture a 54.0% revenue share in 2026, driven by their recurring use in routine laboratory workflows, including reagents, assay kits, slides, chambers, and calibration components. High testing volumes for hematology, oncology research, immunology, and cell-based assays further bolster adoption. Emphasis on accuracy, contamination control, and regulatory compliance enhances dependence on high-quality consumables. Expanding bioprocessing and cell therapy pipelines necessitate consistent monitoring, reinforcing repeat purchases. Technological advancements improving assay sensitivity, shelf life, and automation compatibility support sustained dominance. Operational continuity and validated consumable performance ensure this segment retains leadership throughout the forecast period.
By Application – Complete Blood Count Leads Due to High Diagnostic Volumes: The CBC segment is anticipated to dominate with a 59.2% revenue share in 2026, driven by its role as a first-line diagnostic test in hospitals, diagnostic laboratories, and outpatient facilities. CBC testing detects infections, anemia, hematological disorders, immune conditions, and monitors chronic diseases, resulting in consistently high testing volumes globally. Rising lifestyle-related diseases, aging populations, and preventive health initiatives further elevate test frequency. Automation in hematology laboratories enhances throughput, accuracy, and turnaround time, strengthening reliance on cell counting technologies. Expanded access to diagnostics in emerging markets and adoption of point-of-care hematology analyzers support sustained demand. CBC’s indispensable role ensures its position as the leading application segment throughout the forecast period.
By End User – Research & Academic Institutes Lead Due to Intensive Cell-Based Research: Research and academic institutes are projected to dominate the market with a 39.8% revenue share in 2026, driven by extensive cell-based experimentation in life sciences research, including oncology, immunology, stem cell biology, and molecular diagnostics. Academic laboratories perform routine cell viability, proliferation, and concentration analyses, resulting in high usage of instruments and consumables. Government and private funding for biomedical research, translational medicine, and regenerative therapies supports demand. These institutes often adopt advanced automated and image-based systems to improve reproducibility and data accuracy. Collaborative research programs with pharmaceutical and biotechnology companies further sustain equipment utilization. While hospitals and diagnostic labs generate steady demand, research and academic institutes remain primary revenue contributors due to continuous experimentation cycles and high dependency on precise cell quantification tools.
Region-Wise Insights
North America Cell Counting Market Trends: North America is expected to hold a 47.3% market share in 2026, led by the United States. The region benefits from a highly developed healthcare and life sciences ecosystem, strong research infrastructure, and early adoption of advanced laboratory technologies. High prevalence of chronic diseases, cancer, and immune disorders drives routine diagnostic testing, particularly CBC procedures. North America hosts numerous pharmaceutical, biotechnology, and contract research organizations, supporting demand for cell counting solutions in drug discovery and bioprocessing. Government funding for biomedical research and NIH-supported academic programs accelerates growth. Regulatory emphasis on data accuracy, standardization, and quality assurance encourages adoption of automated and validated systems. Continuous technological innovation and laboratory upgrades, alongside increasing focus on personalized medicine, reinforce North America’s market leadership.
Europe Cell Counting Market Trends: The Europe market is growing steadily due to strong regulatory oversight, high laboratory standards, and expanding biomedical research in countries such as Germany, the U.K., France, Italy, and Spain. Well-established diagnostic infrastructure and focus on early disease detection and preventive healthcare support market expansion. Rising incidence of hematological disorders, cancer, and autoimmune diseases drives routine cell analysis across clinical and research settings. Emphasis on accuracy, reproducibility, and compliance with stringent regulations supports demand for high-quality instruments and consumables. Growth in biopharmaceutical manufacturing, particularly biosimilars and cell-based therapies, enhances market penetration. Academic research expansion and cross-border collaborations further sustain adoption. Innovation in life sciences ensures consistent long-term growth across Europe.
Asia Pacific Cell Counting Market Trends: Asia Pacific is expected to register a CAGR of 8.3% between 2026 and 2033, driven by rapid healthcare expansion, rising research investments, and improved diagnostic access. Countries such as China, India, Japan, South Korea, and Australia are witnessing growing demand due to increasing disease burden, pharmaceutical manufacturing, and clinical testing volumes. Government initiatives supporting biotechnology, genomics, and translational research enhance laboratory infrastructure development. Adoption of automated hematology analyzers improves testing efficiency and accuracy. Cost-effective instruments, local manufacturing, and outsourcing of research and bioprocessing further increase accessibility. Growing medical research output, academic collaborations, and rising healthcare expenditure position Asia Pacific as the fastest-growing regional market.
Checkout Now & Download Complete Market Report: https://www.persistencemarketresearch.com/checkout/33176
Market Competitive Landscape
The global cell counting market is highly competitive, featuring prominent companies such as Thermo Fisher Scientific, Inc., Merck KGaA, Agilent Technologies, PerkinElmer, Inc., and BD. These players leverage global distribution networks, strong brand recognition, and diversified product portfolios to meet growing demand for high-throughput, accurate cell analysis solutions.
Their offerings focus on automation, imaging- and impedance-based technologies, analytical precision, workflow efficiency, and compatibility across clinical diagnostics, stem cell research, bioprocessing, and cell-based therapeutics. Continuous innovation, regulatory compliance, clinical accuracy, product reliability, and adherence to international quality standards are critical to maintaining competitive positioning.
Key Industry Developments: In January 2025, Illumina, Inc. launched the Illumina Billion Cell Atlas, the world’s largest genome-wide genetic perturbation dataset, aiming to accelerate AI-driven drug discovery across the pharmaceutical ecosystem. This initiative will construct a 5 billion–cell atlas over three years, providing comprehensive insights into gene function, disease mechanisms, and therapeutic target identification. In August 2024, DeNovix Inc. introduced the CellDrop FLi Automated Cell Counter, featuring enhanced hardware for improved accuracy and six new cell counting applications, including fixed samples, hepatocytes, and Erythrosin B–based viability assays.
Companies Covered: Thermo Fisher Scientific, Inc., Merck KGaA, Agilent Technologies, PerkinElmer, Inc., BD, Danaher, Bio-Rad Laboratories, Inc., BioTek Instruments, Inc., GE Healthcare, DeNovix Inc., Abbott Laboratories, Beckman Coulter, Inc., Sysmex Corporation, Olympus Corporation.
The global cell counting market continues to experience robust growth driven by technological innovation, rising diagnostic and research needs, and expanding healthcare infrastructure worldwide. With the combined impact of emerging markets, advanced automation, and the expansion of cell and gene therapy pipelines, the market is well-positioned for long-term growth and sustained adoption across clinical, research, and biopharmaceutical applications.




