
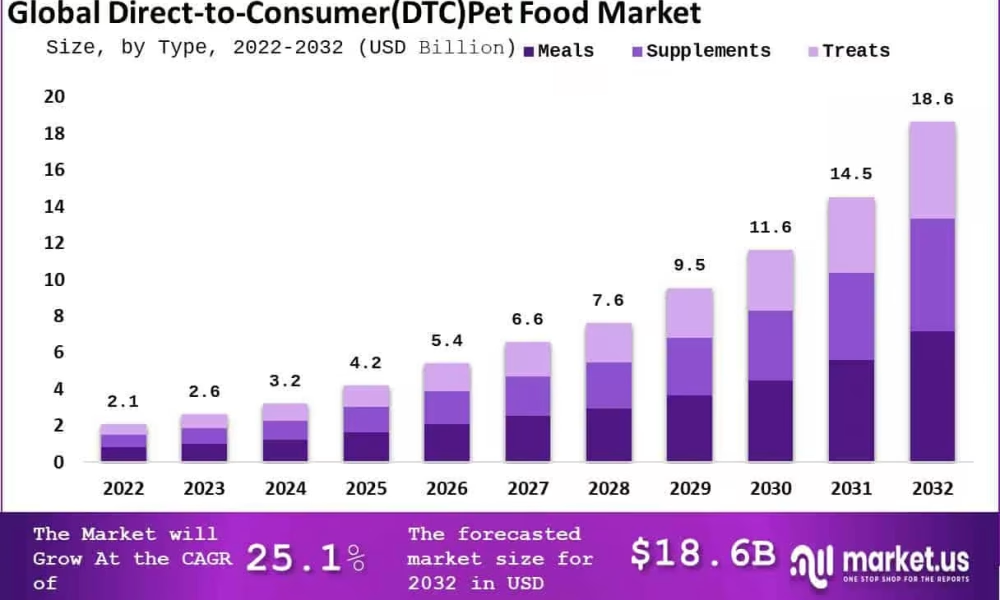
According to market.us, in 2022, the global Direct-To-Consumer (DTC) pet food market reached a value of USD 2.1 billion and is expected to grow substantially to USD 18.6 billion by 2032. This reflects a strong compound annual growth rate (CAGR) of 25.1% from 2023 to 2032. The surge in demand is being influenced by the growing popularity of online shopping, increasing awareness about pet health, and the expanding trend of treating pets as part of the family. Pet owners are increasingly choosing premium, organic, grain-free, and personalized food options, which DTC platforms are well-positioned to deliver.
The convenience of direct home delivery, along with flexible subscription services, has made DTC a preferred option for many consumers. These platforms also allow brands to maintain closer relationships with their customers, enhancing trust and satisfaction. Improvements in digital tools and logistics systems have further strengthened the efficiency of DTC services.
The shift toward digital shopping, accelerated during the COVID-19 pandemic, has firmly established DTC as a prominent channel in the pet food space. The United States continues to lead in this domain due to high pet ownership and spending, while developing regions are seeing faster growth with rising pet adoption and disposable income.
Key Takeaways
- Market Size and Growth: The DTC Pet Food market was valued at USD 2.1 billion in 2022 and is projected to reach USD 18.6 billion by 2032, with a CAGR of 25.1% between 2023 and 2032.
- DTC Pet Food Definition: DTC Pet Food refers to a business model where pet food manufacturers sell their products directly to consumers through online channels or in retail stores. This approach emphasizes quality, ingredient transparency, and customization for pet owners.
- By Type Analysis: Market Share (2022): The meal segment accounted for the highest market revenue share of 38.5%.
- By Pet Analysis: Market Share (2022): The dog segment dominated the largest market revenue share of 54.6% during the forecast period.
- By Health Condition Analysis: Digestive Health Segment Market Share (2022) The digestive health segment registers the highest CAGR during the forecast period, but specific market share data is not provided.
- Regional Analysis: North America and North America accounted for a significant market revenue share of 37.5%. The Asia-Pacific region is expected to register a CAGR of 4.2% during the forecast period.
Access a Complimentary Sample of This Premium Report: https://market.us/report/direct-to-consumerdtc-pet-food-market/request-sample/
Factors Affecting the Growth of the Direct-to-Consumer(DTC) Pet Food Market
Growing Humanization of Pets: The increasing tendency among pet owners to treat pets as family members has significantly influenced buying behavior. Consumers are prioritizing pet health and wellness, opting for high-quality, specialized nutrition that aligns with human food trends such as organic, natural, and allergen-free ingredients.
Rising Demand for Personalized Nutrition: DTC platforms allow for customized meal plans based on pet breed, age, weight, activity level, and health conditions. This personalized approach to feeding is gaining traction as pet owners seek tailored dietary solutions that traditional retail formats struggle to offer.
Expansion of E-commerce and Digital Infrastructure: The widespread availability of high-speed internet, mobile apps, and user-friendly online platforms has made it easier for pet owners to order food directly from brands. Enhanced logistics and real-time tracking capabilities have also improved the overall customer experience and delivery reliability.
Subscription-Based Business Models: Flexible subscription services that offer scheduled deliveries and automatic refills are encouraging repeat purchases and fostering brand loyalty. These models provide convenience for consumers while helping brands maintain steady revenue streams.
Health and Safety Awareness Post-Pandemic: The COVID-19 pandemic heightened consumer focus on health and hygiene. This shift extended to pet care, with more consumers preferring to order pet food online rather than visiting physical stores, reinforcing DTC platforms as a safer and more convenient option.
Key Market Segmentation
By Type Analysis
In 2022, the global direct-to-consumer (DTC) pet food market was segmented into meals, treats, and supplements, with the meals segment leading at 38.5% of the total revenue share. This dominance was driven by growing attention to pet health, rising spending on premium meals, and increasing demand for customized nutrition, especially in emerging markets.
Factors such as higher ingredient quality, longer shelf life, and the growing trend of pet humanization have further supported the global growth of this segment. Customized meals also help monitor dietary habits and address specific health conditions, fueling their popularity.
The supplements segment, which held a dominant position during the historical period, is projected to retain the second-largest share. Supplements are concentrated ingredients added to pet diets for both therapeutic and nutritional benefits, supporting their continued demand.
By Pet Analysis
Based on pet type, the global direct-to-consumer (DTC) pet food market is categorized into dogs, cats, and others. The dog segment accounted for the highest revenue share of 54.6% during the forecast period, driven by the growing adoption of dogs, rising demand for premium dog food, and the increasing humanization of pets. In the U.S. alone, 69.0 million households own a dog, according to the American Pet Products Association.
Meanwhile, the cat segment is expected to register the fastest growth, supported by the emotional comfort cats offer to their owners, which has contributed to rising demand and adoption rates.
By Health Condition Analysis
Based on health condition, the global direct-to-consumer (DTC) pet food market is segmented into nutrition, digestive health, heart health, dental health, skin problems, stress, joint health, allergies, and others. The digestive health segment is projected to register the highest CAGR during the forecast period, driven by the growing availability of customized nutritional formulations aimed at preventing digestive issues, along with the inclusion of probiotics and prebiotics in pet diets.
The nutrition segment is expected to hold the second-largest revenue share, supported by the expansion of premium pet food brands and increasing awareness among pet owners regarding their pets’ specific health needs and dietary preferences.
By Distribution Channel Analysis
Based on distribution channel, the global direct-to-consumer (DTC) pet food market is segmented into online and offline channels. In 2022, the online segment held the largest revenue share, driven by growing consumer preference for personalized offerings, greater accessibility to discounts compared to offline outlets, and enhanced convenience in purchasing.
The offline segment is projected to grow at a CAGR of 5.3%, supported by the expanding availability of pet supplements, including skin and coat care products and multivitamins, in physical retail stores.
Key Market Segments
By Type
- Meal
- Treats
- Supplements
By Pet
- Dogs
- Cats
- Other Pets
By Health Condition
- Nutrition
- Digestive Health
- Heart Health
- Dental Health
- Skin Problems
- Stress
- Joint Health
- Allergies
- Other Health Conditions
By Distribution Channel
- Online Channel
- Offline Channel
Regional Analysis
North America leads the global direct-to-consumer (DTC) pet food market, accounting for 37.5% of the total revenue share. This dominance is attributed to the growing number of affluent pet owners, the wide availability of personalized pet products, and heightened attention to pet health and nutrition. The strong presence of major market players in the region further boosts demand for DTC pet food.
Meanwhile, the Asia-Pacific region is projected to grow at a CAGR of 4.2% during the forecast period. Growth in this region is driven by the rising number of pet-owning households and rapid urbanization, particularly in emerging economies like India, China, and Indonesia. Additionally, increased investments by key companies in new production facilities and market expansion are contributing to regional growth.
Top Key Players
- Nestle S.A.
- General Mills, Inc.
- Mars, Incorporated
- Hill’s Pet Nutrition, Inc.
- Diamond Pet Foods, Inc.
- Wellness Pet Company
- The Farmers Dog Inc.
- Jinx Inc.
- The J.M. Smucker Company
- Other Key Players
Get in Touch with Us:
Market.us (Powered By Prudour Pvt. Ltd.)
Address: 420 Lexington Avenue, Suite 300 New York City, NY 10170, United States
Send Email: [email protected]
Refer to More Related Reports:



