
Market Overview
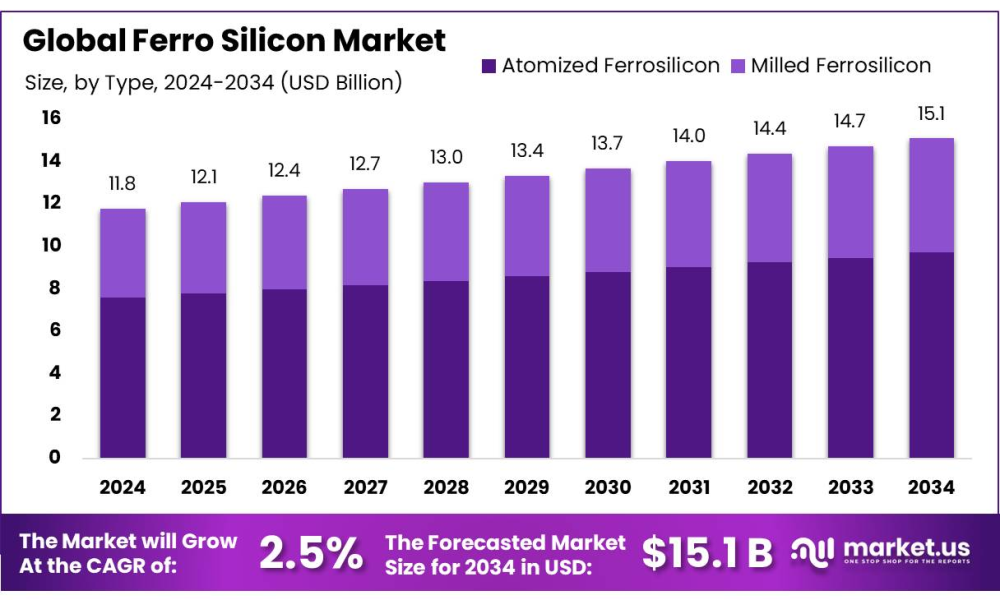
According to market.us, the global Ferro Silicon Market is projected to reach approximately USD 15.1 billion by 2034, rising from USD 11.8 billion in 2024, with a steady compound annual growth rate (CAGR) of 2.5% between 2025 and 2034.
Ferro Silicon (FeSi) plays a critical role in the metallurgical sector, primarily serving as a deoxidizer and alloying element in the production of steel and cast iron. Its inclusion enhances steel’s mechanical characteristics such as strength, hardness, and corrosion resistance making it essential across a wide range of industrial applications. The industry’s growth is strongly supported by government policies and initiatives. For example, India’s National Steel Policy (NSP) 2017 targets a crude steel production capacity of 300 million tons and aims to increase per capita steel consumption to 160 kg by 2030. Complementary initiatives like “Make in India” and the Production-Linked Incentive (PLI) scheme are also encouraging domestic manufacturing, thereby fueling demand for ferrosilicon.
The transition in the automotive sector toward electric and lightweight vehicles is another major growth factor. These developments demand advanced steel grades, where ferrosilicon is essential for improving mechanical performance. As per the Indian Ministry of Steel, domestic steel demand is projected to grow by 9–10% in FY25, further bolstering ferrosilicon consumption. Infrastructure growth also contributes significantly to market expansion. Initiatives such as the Smart Cities Mission and ongoing construction investments are boosting the need for high-quality steel. A notable example is the ₹225 crore investment announced in October 2024 by Metro Group for a new housing project in the Mumbai Metropolitan Region, underscoring the increasing demand for ferrosilicon in infrastructure development.
Important Revelation
- The Ferro Silicon Market is projected to reach approximately USD 15.1 billion by 2034, up from USD 11.8 billion in 2024, growing at a CAGR of 2.5%.
- Atomized Ferrosilicon led the market with a dominant share of 64.3%.
- Deoxidizer applications accounted for the largest segment, holding a 69.4% share of the global market.
- Carbon & Other Alloy Steel emerged as the leading end-use segment, capturing 44.8% of the market.
- The Asia Pacific (APAC) region dominated the global market, holding a 43.9% share, valued at approximately USD 5.1 billion.
Download Exclusive Sample Of This Premium Report (Including Full TOC, Table & Figures):
https://market.us/report/ferro-silicon-market/free-sample/
Factors Affecting the Growth of the Ferro Silicon Market
- Rising Steel and Iron Production: The increasing demand for steel and cast iron across industries such as construction, automotive, and infrastructure significantly boosts the consumption of ferrosilicon as a deoxidizer and alloying agent.
- Government Infrastructure Initiatives: Large-scale government projects like Smart Cities Mission, housing schemes, and metro expansions are driving the need for high-strength steel, thereby increasing ferrosilicon usage.
- Automotive Industry Advancements: The shift towards electric and lightweight vehicles requires high-performance steel alloys, where ferrosilicon plays a vital role in enhancing mechanical properties.
- Supportive Government Policies: Policies such as India’s National Steel Policy 2017 and incentives under the Production-Linked Incentive (PLI) scheme encourage domestic steel production, indirectly boosting ferrosilicon demand.
- Expansion of Renewable Energy and Power Infrastructure: Growing investments in renewable energy and transmission infrastructure require durable, high-quality steel, further increasing the use of ferrosilicon.
- Technological Developments in Metallurgy: Advances in steel manufacturing processes and alloy innovation enhance the applicability of ferrosilicon, expanding its role in specialized applications.
- Volatility in Raw Material Prices: Fluctuations in the prices of raw materials such as silica, coke, and scrap metal can impact production costs and limit profit margins for ferrosilicon manufacturers.
Report Segmentation
By Type: In 2024, atomized ferrosilicon dominated the global ferro silicon market by type, accounting for over 64.3% of the total share. This dominance is attributed to its superior density control, clean separation capabilities, and stable performance, particularly in mineral processing industries. Its fine granulation allows for precise suspensions in heavy media separation, making it the preferred choice in coal and iron ore processing.
By Application: Deoxidizers captured a leading 69.4% share of the ferro silicon market by application in 2024. This commanding position stems from the crucial role ferro silicon plays in removing oxygen during steel production, thereby enhancing the metal’s strength, durability, and processing efficiency.
By End-use: In 2024, the carbon and other alloy steel segment accounted for more than 44.8% of the global ferro silicon market by end-use. The dominance of this segment is due to the vital role ferro silicon plays in producing alloyed steels with enhanced mechanical properties such as improved tensile strength, corrosion resistance, and hardenability.
To Purchase this Premium Report@ https://market.us/purchase-report/?report_id=149857
Market Key Segmentation List
By Type
- Atomized Ferrosilicon
- Milled Ferrosilicon
By Application
- Deoxidizer
- Inoculants
- Others
By End-use
- Carbon & Other Alloy Steel
- Stainless Steel
- Electric Steel
- Cast Iron
- Others
Regional Analysis
Asia Pacific Leads Ferro Silicon Market with 43.9% Share, Valued at USD 5.1 Billion
In 2024, the Asia Pacific (APAC) region dominated the global ferro silicon market, holding a 43.9% share, which translates to a market value of approximately USD 5.1 billion. This leadership is largely attributed to the region’s strong steel production and consumption, particularly in major economies like China and India. China alone accounts for about 81% of APAC’s ferro silicon demand, followed closely by Japan and India.
The region’s rapid industrialization especially in construction and automotive sectors continues to fuel the need for ferro silicon. In India, government policies such as the National Steel Policy are aimed at expanding steel manufacturing capacity, further driving demand for ferro silicon in its role as a deoxidizer and alloying element.
Additionally, the growth of electric vehicle production in countries like Japan and South Korea has heightened the demand for advanced steel grades, boosting ferro silicon consumption. Infrastructure development projects across the region have also increased steel usage, creating a ripple effect on the ferro silicon market.
Furthermore, APAC’s growing focus on sustainable and energy-efficient manufacturing has led to the adoption of modern technologies in ferro silicon production, improving quality and aligning with the evolving needs of various end-use industries.
Competitive Landscape
- China National Bluestar (Group) Co. Ltd.
- DMS Powders
- Elkem ASA
- Eurasian Resources Group
- Ferroglobe PLC
- FINNFJORD AS
- Finnfjord AS
- Hindustan Alloys Private Limited
- Indian Metals & Ferro Alloys Limited
- Maithan Alloys Limited
- Mechel PAO
- OM Holdings Ltd.
- Russian Ferro-Alloys Inc.
- SINOGU CHINA
- VBC Ferro Alloys Limited
- Westbrook Resources Ltd.
Recent Developments
- In 2024, Finnfjord AS, located in Finnsnes, Norway, maintained its strong position in the ferro silicon industry with an annual production capacity of 100,000 tonnes.
- In the same year, Eurasian Resources Group (ERG), headquartered in Luxembourg, reinforced its global leadership in ferroalloy production. Through its subsidiary Kazchrome, ERG recorded a ferroalloy output of 1.864 million tonnes, reflecting a 14% year-over-year increase.
Get in Touch with Us
Market.us (Powered By Prudour Pvt. Ltd.)
Address: 420 Lexington Avenue, Suite 300 New York City, NY 10170, United States
Send Email: [email protected]



