
Increase in the adoption of advanced connectivity solutions such as AI and ML in vehicles, rise in demand for autonomous and connected vehicles, and the ongoing shift toward electrification drive the global software defined vehicle market growth.
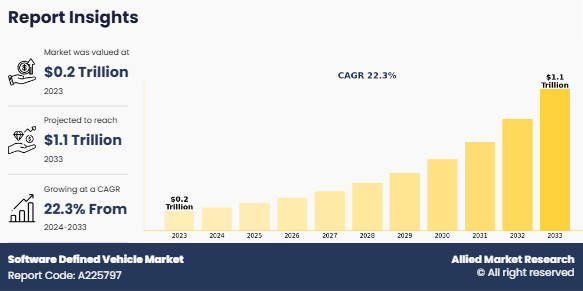
Allied Market Research published a report, titled, “Software Defined Vehicle Market by SDV Type (Semi-SDV and SDV), Electrical And Electronic Architecture (Distributed Architecture, Domain Centralised Architecture, Zonal Control Architecture, and Hybrid Architecture), Vehicle Type (Passenger Car and Commercial Vehicle), Propulsion (ICE, Electric, Hybrid, and Others), Offering (Software, Hardware, and Services), and Application (Infotainment systems, Advanced Driver Assistance Systems (ADAS), Autonomous driving, Telematics, Powertrain control, Battery Management Systems, V2X communication, and Others): Global Opportunity Analysis and Industry Forecast, 2024-2033″. According to the report, the software defined vehicle market was valued at $0.2 trillion in 2023, and is estimated to reach $1.1 trillion by 2033, growing at a CAGR of 22.3% from 2024 to 2033.
Request Sample Pages: https://www.alliedmarketresearch.com/request-sample/A225797
The Semi-SDVs segment held the highest market share in 2023.
By SDV type, the Semi-SDVs segment held the highest software defined vehicle market market share in 2023, due to their balanced approach to integrating software-defined capabilities while maintaining cost efficiency. These vehicles combine advanced software-driven features such as over-the-air (OTA) updates and basic autonomous functions, making them accessible to mainstream consumers and adaptable to infrastructure limitations in developing regions. However, the SDV segment is expected to portray the highest CAGR of 23.1% during the forecast period due to the growing adoption of fully software-driven architectures in next-generation vehicles, which allow for enhanced connectivity, over-the-air (OTA) updates, and advanced features integration.
The domain centralized architecture held the highest market share in 2023.
By electrical and electronic architecture, the domain centralised architecture segment accounted for a dominant market share in 2023 as it offers a cost-effective transition from traditional distributed systems to modernized, software-centric frameworks. This architecture consolidates multiple ECUs into domains (e.g., ADAS, infotainment), reducing complexity, enabling enhanced performance, and facilitating easier OTA updates. However, the zonal control architecture segment is expected to portray the highest CAGR of 24.1% during the forecast period due to its capability to significantly reduce wiring complexity, weight, and cost, which is essential for electric and connected vehicles.
The passenger car segment held the highest market share in 2023.
By vehicle type, the passenger car segment accounted for the largest market share and is anticipated to maintain its dominance till 2033, and the same segment is forecasted to have the highest CAGR of 22.5% during the forecast period. This is because of the high consumer demand for advanced features such as infotainment, ADAS, and V2X communication. With the global push towards electrification and autonomous driving, passenger cars are adopting SDV technologies at a faster rate compared to commercial vehicles.
Buy this Complete Report (340 Pages PDF with Insights, Charts, Tables, and Figures) at:
https://www.alliedmarketresearch.com/software-defined-vehicle-market/purchase-options
The ICE segment held the highest market share in 2023.
By propulsion, the ICE segment accounted for the largest software defined vehicle market market share as ICE vehicles are well-established, with a global manufacturing infrastructure, widespread fueling networks, and affordability compared to electric or hybrid vehicles. However, the electric segment is expected to portray the highest CAGR of 24% during the forecast period, owing to its alignment with global sustainability goals, government incentives, and consumer preference for environment-friendly options. EVs inherently rely on software-defined systems for battery management, efficiency optimization, and seamless connectivity, driving their dominance in the software defined vehicle market.
The software segment held the highest market share in 2023.
By offering, the software segment accounted for the largest market share and is anticipated to maintain its dominance till 2033, and the same segment is projected to have the highest CAGR of 23.4% during the forecast period. Software serves as the core enabler of SDVs, powering key features such as ADAS, autonomous driving, and infotainment systems. Automakers and technology providers are heavily investing in software development, focusing on OTA updates and data-driven functionalities, which are integral to SDVs.
The advanced driver assistance systems (ADAS) segment held the highest market share in 2023.
By application, the advanced driver assistance systems (ADAS) segment accounted for the largest market share and is anticipated to maintain its dominance till 2033, due to the increasing demand for safety and convenience features, driven by regulations mandating advanced safety technologies. However, the autonomous driving segment is projected to witness the highest CAGR of 25.3% during the forecast period as automakers and technology companies invest heavily in self-driving technology.
Asia-Pacific held the highest market share in 2023.
By region, Asia-Pacific accounted for the largest software defined vehicle market market share and is anticipated to maintain its dominance till 2033, and the same segment is projected to witness the highest CAGR of 23.6% during the forecast period. It is home to major automotive and technology hubs like China, Japan, and South Korea, which lead in EV production, connected car technologies, and autonomous driving advancements. China drives the region’s growth with government incentives, strong EV adoption, and massive investments in smart mobility.
Enquiry Before Buying: https://www.alliedmarketresearch.com/purchase-enquiry/A225797
Leading Market Players: –
- Aptiv PLC
- Tesla, Inc.
- Continental AG
- NVIDIA Corporation
- Robert Bosch GmbH
- Li Auto Inc.
- Rivian Automotive, Inc.
- Volkswagen AG
- General Motors Company
- Qualcomm Incorporated
The report provides a detailed analysis of these key players in the global software defined vehicle market. These players have adopted different strategies such as new product launches, collaborations, expansion, joint ventures, agreements, and others to increase their market share and maintain dominant shares in different regions. The report is valuable in highlighting business performance, operating segments, product portfolio, and strategic moves of market players to showcase the competitive scenario.
𝐀𝐛𝐨𝐮𝐭 𝐮𝐬 :
Allied Market Research (AMR) is a full-service market research and business-consulting wing of Allied Analytics LLP based in Wilmington, Delaware. Allied Market Research provides global enterprises as well as medium and small businesses with unmatched quality of “Market Research Reports” and “Business Intelligence Solutions.” AMR has a targeted view to provide business insights and consulting to assist its clients to make strategic business decisions and achieve sustainable growth in their respective market domain.
We are in professional corporate relations with various companies, and this helps us in digging out market data that helps us generate accurate research data tables and confirms utmost accuracy in our market forecasting. Each and every data presented in the reports published by us is extracted through primary interviews with top officials from leading companies of domain concerned. Our secondary data procurement methodology includes deep online and offline research and discussion with knowledgeable professionals and analysts in the industry.
𝐂𝐨𝐧𝐭𝐚𝐜𝐭 𝐔𝐬 :
David Correa
1209 Orange Street,
Corporation Trust Center,
Wilmington, New Castle,
Delaware 19801 USA.
Int’l: +1-503-894-6022
Toll Free: +1-800-792-5285
Fax: +1-800-792-5285
[email protected]




