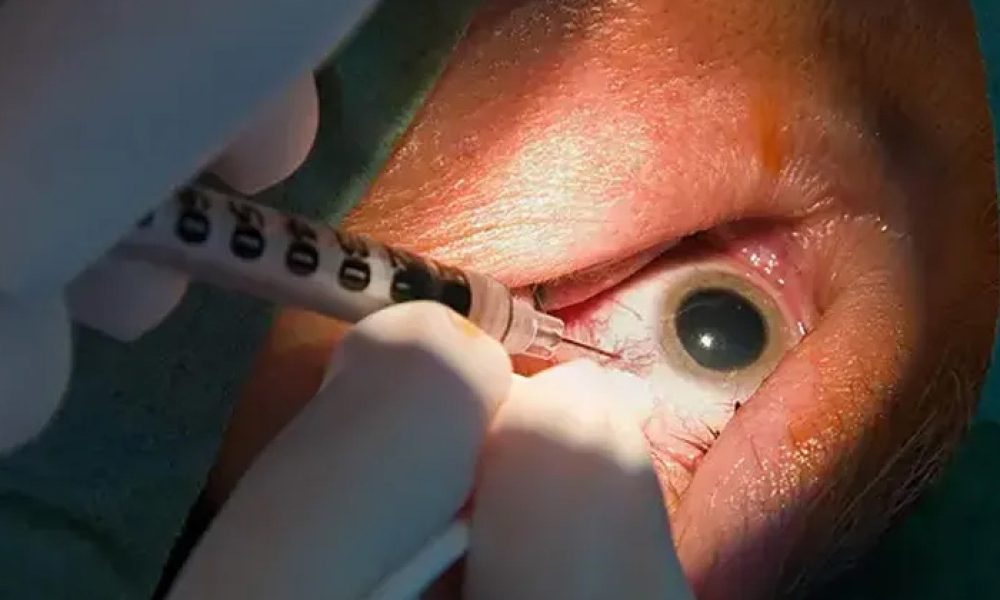
The global anti-VEGF (vascular endothelial growth factor) market has experienced remarkable growth over the past decade and is poised to continue expanding in the coming years. Anti-VEGF drugs, commonly referred to as VEGF inhibitors, are targeted therapies primarily used in oncology and ophthalmology. These drugs work by blocking VEGF proteins, which play a crucial role in angiogenesis, the formation of new blood vessels that tumors and other pathological conditions rely on for growth. By inhibiting VEGF activity, these drugs effectively restrict blood supply to tumors, thereby limiting cancer progression and improving patient outcomes. Apart from cancer, anti-VEGF therapies are widely used for retinal disorders, such as neovascular age-related macular degeneration (AMD), diabetic macular edema, and retinal vein occlusion, owing to their ability to reduce pathological blood vessel proliferation.
The global anti-VEGF market was valued at US$ 25.2 billion in 2025 and is projected to reach US$ 33.1 billion by 2032, registering a steady CAGR of 4.0% during this period. Biologics dominate the product segment, accounting for 73.3% of the market share in 2024, while anti-VEGF therapies contributed 11.4% to the overall global oncology therapeutics medicines market. Key growth drivers include the rising prevalence of cancer, advancements in drug delivery systems, increasing regulatory approvals, and the expanding use of combination therapies in cancer treatment. The leading segment of the market remains biologics due to their high specificity, longer half-life, and robust clinical efficacy, while the United States holds the largest regional market share owing to its advanced healthcare infrastructure, widespread access to targeted therapies, and strong presence of major pharmaceutical players.
Download Your Free Sample & Explore Key Insights: https://www.persistencemarketresearch.com/samples/33422
Key Highlights from the Report
• The global anti-VEGF market is expected to reach US$ 33.1 billion by 2032.
• Biologics dominate the product segment with a 73.3% market share in 2024.
• Anti-VEGF therapies accounted for 11.4% of the global oncology therapeutics market in 2024.
• The United States led the North American market with a 95.2% share in 2024.
• VEGF-A inhibitors hold the largest share among all VEGF inhibitor types at 49.1%.
• Oncology remains the dominant application segment, capturing 95.5% of the market in 2024.
Market Segmentation
The anti-VEGF market is broadly segmented based on product type, mechanism of action, therapeutic application, and end-user. By product type, the market is classified into biologics and small-molecule inhibitors, with biologics being the dominant segment due to their high specificity, longer half-life, and proven clinical efficacy. Mechanism-based segmentation includes VEGF-A inhibitors, VEGF-B inhibitors, and pan-VEGF inhibitors, with VEGF-A inhibitors leading due to their widespread use in treating multiple cancers and retinal disorders. In terms of therapeutic application, oncology holds the largest market share, driven by the rising incidence of various cancers such as kidney, colorectal, ovarian, and non-small cell lung cancer. Ophthalmology constitutes a significant secondary segment, largely focused on neovascular AMD and diabetic macular edema. The end-user segment encompasses hospitals, specialty clinics, and research institutions, with hospitals being the primary consumers due to their capability to administer complex treatment regimens and combination therapies.
Regional Insights
Geographically, the anti-VEGF market is dominated by North America, particularly the United States, which accounted for 95.2% of the North American market in 2024. This dominance is attributed to the presence of advanced healthcare infrastructure, high patient access to innovative treatments, and a strong base of pharmaceutical manufacturers actively developing and marketing VEGF inhibitors. Europe and Asia-Pacific are emerging as high-growth regions, with countries such as China and Japan showing increasing demand driven by government support, aging populations, and rising cancer incidence. China held 48.7% of the East Asia anti-VEGF market in 2024, benefiting from government initiatives like the inclusion of VEGF inhibitors in the National Reimbursement Drug List, making these treatments more accessible. Oceania, led by Australia with a 72.1% market share, is witnessing steady growth due to high cancer prevalence and adoption of combination therapies involving VEGF inhibitors.
Get Custom Insights Designed for Your Business: https://www.persistencemarketresearch.com/request-customization/33422
Market Drivers
The anti-VEGF market is primarily driven by the rising global incidence of cancer and other angiogenesis-related disorders, along with increasing awareness of the benefits of targeted therapies. Regulatory approvals for new VEGF inhibitors and biosimilars have further bolstered market growth by expanding the treatment options available to physicians and patients. Advancements in drug delivery technologies, such as dendrimer-encapsulated molecules and liposome-based intravitreal injections, have improved the efficacy and safety of these drugs, particularly for ocular applications. The growing adoption of combination therapies that pair VEGF inhibitors with chemotherapy or immunotherapy also enhances therapeutic outcomes, further driving demand. Additionally, the inclusion of anti-VEGF drugs in government healthcare reimbursement schemes, especially in countries like China, ensures wider accessibility and affordability, contributing significantly to market expansion.
Market Restraints
Despite the strong growth potential, the anti-VEGF market faces several challenges that could restrain expansion. Adverse effects associated with VEGF inhibitors, such as bleeding complications, thrombosis, hypertension, and gastrointestinal disturbances, limit their widespread use and require careful management. High treatment costs, particularly for biologics such as aflibercept and ranibizumab, also pose a significant barrier, making these therapies less accessible in price-sensitive regions. Off-label use of lower-cost alternatives like bevacizumab has gained prevalence in certain markets, which negatively impacts the sales of on-label, high-priced drugs. Additionally, the stringent regulatory approval process and prolonged timelines for introducing new VEGF inhibitors can delay product launches, restricting market growth in the short term.
Market Opportunities
The anti-VEGF market presents several promising opportunities for pharmaceutical companies and healthcare providers. The expansion of biosimilars offers an avenue to make these therapies more cost-effective while maintaining efficacy, opening new markets in developing countries. Ongoing research into novel drug delivery systems, including controlled-release ocular formulations and targeted nanoparticles, can enhance patient compliance and treatment outcomes. Moreover, the growing incidence of retinal disorders and the aging global population create a sustained demand for ophthalmic applications. Emerging markets in Asia-Pacific, Latin America, and the Middle East are also poised to benefit from improved healthcare infrastructure and government initiatives, presenting opportunities for regional market expansion. Additionally, the combination of VEGF inhibitors with emerging cancer immunotherapies offers potential for enhanced clinical efficacy and market differentiation.
Checkout Now & Download Complete Market Report: https://www.persistencemarketresearch.com/checkout/33422
Company Insights
Key players operating in the global anti-VEGF market include:
• Pfizer Inc.
• Bayer AG
• Novartis AG
• Sanofi SA
• Exelixis Inc.
• Eisai Co. Ltd.
• Amgen Inc.
• F. Hoffmann-La Roche Ltd.
• Eli Lilly and Company
• Amneal Pharmaceuticals Inc.
• Jiangsu Hengrui Pharmaceuticals Co. Ltd.
• Takeda Pharmaceutical Co. Ltd.
• Sino Biopharma
• HUTCHMED
Recent developments include the U.S. FDA approval of Eli Lilly’s CYRAMZA® in May 2023 for advanced non-small cell lung cancer patients with specific mutations, and the approval of Amneal Pharmaceutical’s biosimilar bevacizumab-maly (ALYMSYS) in April 2023, marking it as the third bevacizumab biosimilar licensed for sale in the United States. These developments highlight the ongoing innovation and regulatory support driving the anti-VEGF market forward.
Conclusion
The global anti-VEGF market is witnessing consistent growth driven by rising cancer prevalence, expanding ophthalmic applications, and technological advancements in drug delivery. Biologics continue to dominate the market due to their specificity and efficacy, while VEGF-A inhibitors remain the most widely used variant across oncology and ophthalmology indications. North America, particularly the United States, leads the market, supported by advanced healthcare infrastructure, strong regulatory frameworks, and active participation of major pharmaceutical companies. Emerging markets, such as China and Australia, also provide substantial growth opportunities due to government support and increasing access to targeted therapies. While high treatment costs and potential adverse effects pose challenges, ongoing innovation, biosimilar approvals, and combination therapy adoption present significant opportunities for market expansion. Overall, the anti-VEGF market is expected to maintain a robust growth trajectory, providing substantial benefits to patients and healthcare systems worldwide.




