
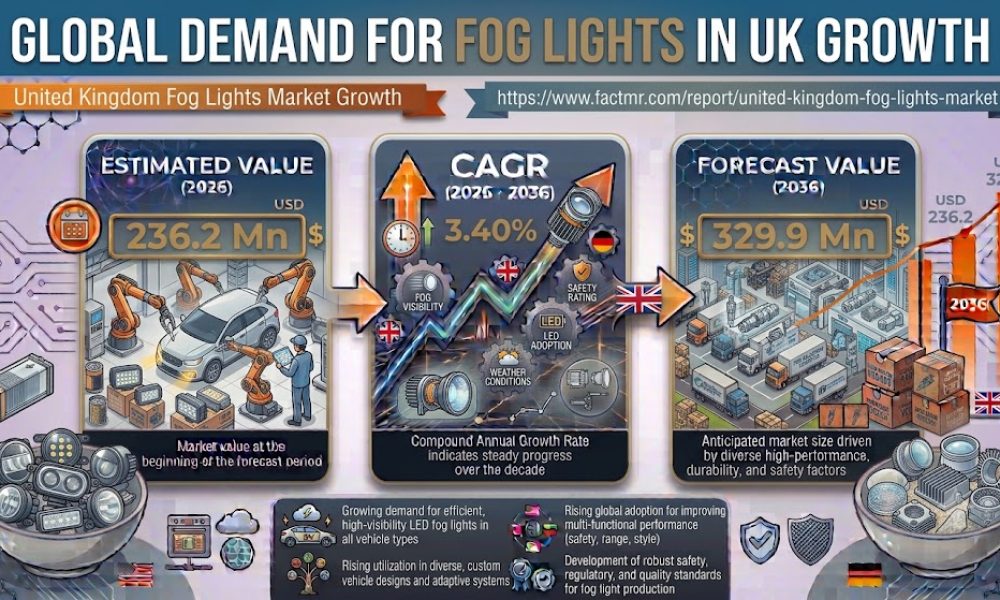
The Demand for Fog Lights in UK is projected to grow from USD 236.2 million in 2026 to USD 329.9 million by 2036, registering a 3.4% CAGR during the forecast period. The market was valued at USD 228.4 million in 2025, creating an absolute dollar opportunity of approximately USD 93.76 million between 2026 and 2036.
Fog lights are auxiliary forward-facing lighting units designed to provide a wide, low-mounted beam during fog, mist, heavy rain, and other low-visibility conditions. In the UK, demand is supported by weather conditions, vehicle replacement cycles, LED adoption, and recurring aftermarket requirements.
Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends: https://www.factmr.com/connectus/sample?flag=S&rep_id=12349
Key Market Segments
- LED fog lights hold a 44.6% share in 2026, making them the leading technology segment. Lower power consumption, longer service life, and consistent illumination are supporting their adoption across newer vehicle models.
- Aftermarket accounts for 52.7% of demand, making it the leading channel in the detailed segment analysis. Replacement needs linked to MOT inspections, lens damage, moisture ingress, bulb failure, and LED retrofit activity support this position.
UK Weather Conditions Sustain Baseline Demand
Fog, mist, drizzle, heavy rainfall, and prolonged winter darkness create recurring visibility challenges across the UK. These conditions help maintain demand for auxiliary lighting systems across passenger vehicles, commercial vehicles, and fleet applications.
The market is therefore less dependent on new vehicle sales alone. Existing vehicles continue to require replacement components as fog-light housings experience road debris, moisture exposure, lens damage, or normal wear.
England accounts for the largest share of UK fog-light demand because of its large vehicle population, dense commuting corridors, and extensive automotive-service infrastructure. Frequent MOT checks also contribute to regular component turnover.
LED Technology Gains Ground
LED fog lights are gradually replacing halogen systems on newer vehicle platforms. Their lower power consumption and longer service life make them attractive to manufacturers and vehicle owners seeking reduced maintenance requirements.
The UK market still has a substantial installed base of halogen-equipped vehicles. Fact.MR estimates that halogen fog lights hold a 36.2% share, supported by older vehicles, lower replacement costs, familiar installation procedures, and wide availability through independent workshops.
This creates a two-speed technology market. Newer vehicles increasingly use LED systems, while older passenger and commercial vehicles continue to sustain demand for halogen replacement products.
Aftermarket Demand Remains Strong
The aftermarket represents 52.7% of demand, reflecting the importance of replacement activity across the UK’s vehicle fleet.
MOT examinations can identify faulty auxiliary lighting, misalignment, or other defects that require corrective action. Road debris can also damage fog-light lenses and housings, while moisture ingress can affect long-term reliability.
Independent garages, regional distributors, national service networks, and fleet maintenance providers support the aftermarket by keeping both LED and halogen products readily available.
LED retrofit kits provide another opportunity. Vehicle owners with older halogen systems can upgrade to LED products where compatibility and installation requirements are met.
Integrated Lighting Creates New Opportunities
Automotive lighting design is moving toward compact systems that combine multiple functions. Fact.MR identifies integrated modules combining fog lighting with daytime running lights and cornering illumination as an emerging design direction.
Adaptive fog-light systems are another developing area. These systems can adjust beam behavior based on factors such as driving speed, steering angle, and environmental conditions.
For manufacturers, sealed LED modules are particularly relevant in the UK because resistance to moisture ingress, vibration, road debris, and stone-chip damage can influence component life and maintenance requirements.
Regional Performance Across the UK
- England: Demand is forecast to grow at a 3.4% CAGR, the highest rate among the four UK countries analyzed. Its large vehicle population, dense transportation corridors, frequent MOT activity, and extensive service network support steady component turnover.
- Scotland: Growth is projected at 3.2% CAGR. Longer winter periods, frequent fog, rural roads, highland terrain, and extended hours of darkness support demand for both LED and halogen systems.
- Wales: The market is expected to advance at 3.1% CAGR. Coastal weather, mountainous terrain, valley routes, and an older vehicle population support replacement demand.
- Northern Ireland: Growth is forecast at 3.0% CAGR, the lowest among the four markets. Coastal and inland fog conditions, rural-route use, older vehicles, and winter visibility challenges maintain steady replacement activity.
Market Drivers and Constraints
The strongest demand driver is the UK’s weather profile. Frequent fog, mist, drizzle, and winter darkness increase the importance of reliable auxiliary lighting.
LED migration provides a second growth engine. Improved manufacturing processes and declining component costs are making LED fog lights more accessible for both original equipment and retrofit applications.
MOT inspection requirements create another recurring source of replacement demand. Faulty lamps, misalignment, and reduced lighting performance can trigger maintenance work.
The main constraints include the higher upfront cost of LED systems, compatibility problems during retrofits, and installation quality. Incorrect alignment can affect beam performance and may create compliance issues during inspection.
Competitive Landscape
The UK fog-lighting market includes established automotive-lighting manufacturers, integrated lighting specialists, and aftermarket suppliers.
Key companies profiled by Fact.MR include Hella GmbH, Valeo SA, Osram GmbH, Stanley Electric Co. Ltd., Koito Manufacturing Co. Ltd., Philips Automotive Lighting, Ring Automotive, Marelli Automotive Lighting, ZKW Group, and Bosch Automotive Components.
Hella GmbH holds an estimated 14.2% share of the UK fog-lighting landscape. The company maintains a presence across OEM and aftermarket channels with LED and halogen auxiliary-lighting products.
Valeo SA, Osram GmbH, Stanley Electric, and Koito Manufacturing compete through lighting technology, optical performance, durability, and vehicle integration capabilities.
Philips Automotive Lighting, Ring Automotive, Marelli Automotive Lighting, ZKW Group, and Bosch Automotive Components provide additional competition across replacement products, lighting modules, and vehicle lighting systems.
Manufacturers are increasingly competing on beam precision, weather resistance, service life, vehicle compatibility, and compact module design.
Analyst Perspective
Fact.MR’s analysis describes UK fog-light demand as a climate-driven automotive lighting category with a stable demand base created by recurring low-visibility conditions.
The report also highlights a distinctive feature of the UK market: replacement activity remains important because weather exposure, road debris, moisture, vehicle age, and MOT requirements generate recurring component turnover.
LED systems are expected to gain further share on newer vehicles, while halogen products remain relevant across the older fleet. For suppliers, this creates an opportunity to serve both technology groups while developing retrofit products that address compatibility and installation requirements.
Report Coverage
The Fact.MR study analyzes the Demand for Fog Lights in UK across technology type, channel, and country.
Technology categories include LED Fog Lights and Halogen Fog Lights.
Channel categories include OEM and Aftermarket.
Country-level analysis covers England, Scotland, Wales, and Northern Ireland.
The report includes auxiliary forward-facing fog-light systems designed for reduced-visibility driving conditions. It excludes main-beam headlights, dipped-beam headlights, daytime running lights, rear fog lamps, interior vehicle lighting, lighting control modules, wiring harnesses, and headlamp-levelling motors sold separately.
Fact.MR uses a hybrid top-down and bottom-up methodology, supported by primary discussions with procurement and operations professionals, regulatory filings, standards records, corporate reports, public financial guidance, and industry benchmarks.
Explore More Related Studies Published by Fact.MR Research:
ADAS Quantum Sensors Market
Baked Food & Cereals Market
About Fact.MR
Fact.MR is a global market research and consulting firm, trusted by Fortune 500 companies and emerging businesses for reliable insights and strategic intelligence. With a presence across the U.S., UK, India, and Dubai, we deliver data-driven research and tailored consulting solutions across 30+ industries and 1,000+ markets. Backed by deep expertise and advanced analytics, Fact.MR helps organizations uncover opportunities, reduce risks, and make informed decisions for sustainable growth.



