
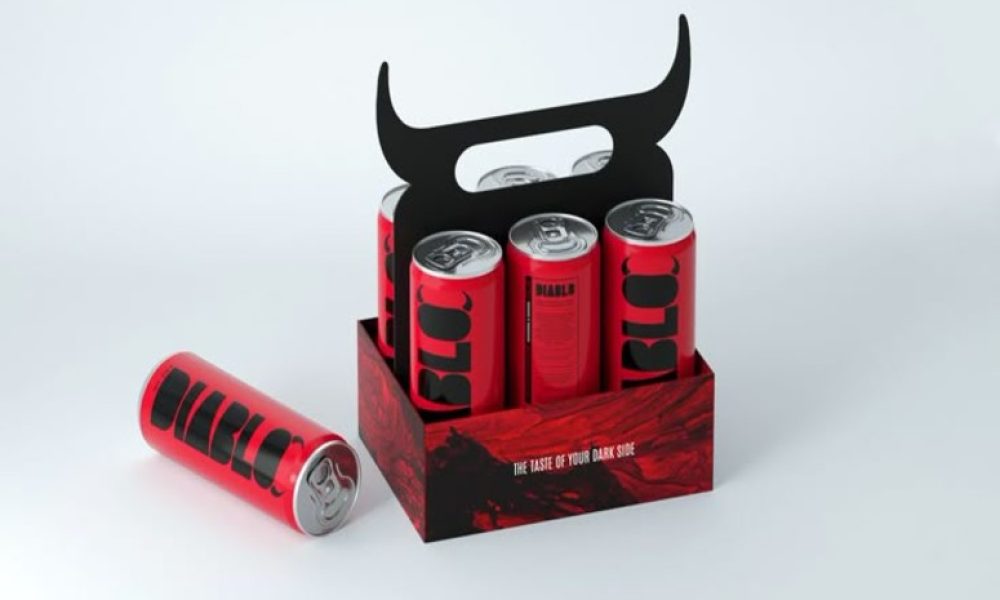
The global alcoholic drinks packaging market is entering a decade of accelerated transformation, with total revenues projected to grow from USD 55.8 billion in 2025 to USD 100.9 billion by 2035, registering a compound annual growth rate (CAGR) of 6.1%. The market’s expansion reflects the convergence of premiumization trends, sustainability initiatives, and advanced packaging technologies that are redefining how alcoholic beverages are presented, preserved, and perceived globally.
A Decade of Momentum and Market Transition
From 2025 to 2030, the market will experience steady growth, expanding from USD 55.8 billion to USD 75.0 billion, fueled by increased adoption of premium and craft alcoholic beverages across both developed and emerging economies. The Asia-Pacific region, in particular, is expected to record the highest growth, led by China (8.2% CAGR) and India (7.6% CAGR), as rising disposable incomes and urban lifestyles accelerate demand for branded and aesthetically packaged drinks.
Request Your Sample Now – Unlock Growth Potential and Discover Key Market Opportunities!
Innovations in lightweight glass bottles, recyclable aluminum cans, and visually appealing labeling are fostering product differentiation and enhancing brand appeal. Parallel growth in on-trade (restaurants, bars) and off-trade (retail, e-commerce) channels is further strengthening distribution efficiency and consumer access.
Between 2030 and 2035, growth will accelerate again—from USD 75.0 billion to USD 100.9 billion—driven by technological adoption, sustainability mandates, and premium packaging innovations in both mature and emerging markets. Regions such as Europe and North America are witnessing strong demand for recyclable and limited-edition packaging, while Latin America is becoming a focal point for cost-effective, lightweight packaging formats.
Market Composition and Value Chain Insights
The alcoholic drinks packaging market is strongly influenced by five interconnected sub-sectors:
- Spirits, Wine, and Beer Packaging (40–45%) — Bottles, cans, and specialty packaging remain the largest demand drivers.
- Glass, Plastic, and Metal Materials (20–22%) — Representing the backbone of production across bottles, closures, and labels.
- Luxury and Premium Packaging (15–17%) — Driven by limited editions, gifting, and collector packaging trends.
- E-commerce and Retail Distribution (10–12%) — Growth tied to digital retail expansion and protective, aesthetic design.
- Sustainable Packaging (5–6%) — Rapidly emerging due to consumer preference and environmental regulations.
Segmental Insights
- Product Segment: Bottles and growlers lead the market with a 36.8% share, maintaining dominance due to their association with premium beverage formats. Their ability to preserve product integrity, enhance visual appeal, and reinforce brand authenticity ensures continued adoption across both retail and hospitality sectors.
- Material Segment: Glass remains the leading material with a 42.5% share, valued for its recyclability, inertness, and premium perception. Lightweight glass technologies and closed-loop recycling initiatives are helping brands reduce costs and carbon footprints while maintaining aesthetic quality.
- End-Use Segment: The beer segment (39.4%) commands the largest end-use share. With the global craft beer movement gaining traction, brands are focusing on custom, sustainable, and visually distinct packaging formats that align with consumer preferences for authenticity and design appeal.
Regional Market Dynamics
China dominates with an 8.2% CAGR, driven by automation, digital labeling, and demand for limited-edition packaging. India follows closely at 7.6% CAGR, supported by organized retail growth, festive packaging demand, and expanding e-commerce penetration.
Europe led by France (6.4%) and Germany (7.0%) benefits from strong wine and spirits industries emphasizing luxury packaging, precision labeling, and compliance with EU sustainability standards.
In the United Kingdom (5.8% CAGR), automation, e-commerce, and premium gifting packaging continue to drive innovation. Meanwhile, the United States growing at 5.2% CAGR, is experiencing increased adoption of functional, high-quality packaging across spirits, wine, and craft beer, enhanced by digital decoration and direct-to-consumer models.
Market Drivers and Key Trends
- Premiumization & Brand Differentiation: Brands are investing in high-end designs—embossed labels, metallic finishes, and custom bottle shapes—to strengthen shelf presence and consumer engagement.
- Sustainability & Circular Economy: Rising regulatory pressure is pushing manufacturers toward recyclable, biodegradable, and returnable packaging materials.
- Digital Printing & Smart Labeling: Adoption of precision decoration, QR-enabled labels, and traceability systems is improving transparency and consumer trust.
- Functional Design & Convenience: Features like resealable caps, ergonomic bottles, and travel-friendly formats are meeting evolving lifestyle needs.
Purchase Full Report for In-Depth Insights
Gain complete access to detailed forecasts, market segmentation, competitive benchmarking, and trend evaluations — purchase the full report here:
Buy Full Report – Alcoholic Drinks Packaging Market
Competitive Landscape
The market remains highly competitive, led by Ardagh Group, O-I Glass, Verallia, Ball Corporation, and Tetra Pak Group, who are investing in lightweight, sustainable, and customizable packaging solutions. Other key players such as Amcor, Crown Holdings, DS Smith, SIG Combibloc, Smurfit Kappa, and WestRock are enhancing design capabilities through automation and material innovation.
Regional specialists AGI Glaspac, Big Sky Packaging, Golden West Packaging, and Orora Group are focusing on niche markets with tailored glass bottles, closures, and decorative finishes.
Collaborative partnerships between brand owners, packaging manufacturers, and technology providers are strengthening innovation pipelines, ensuring alcoholic drinks packaging continues to evolve as a blend of aesthetic excellence, environmental responsibility, and consumer-centric functionality.
Have a specific Requirements and Need Assistant on Report Pricing or Limited Budget please contact us – [email protected]
About Future Market Insights (FMI)
Future Market Insights, Inc. (FMI) is an ESOMAR-certified, ISO 9001:2015 market research and consulting organization, trusted by Fortune 500 clients and global enterprises. With operations in the U.S., UK, India, and Dubai, FMI provides data-backed insights and strategic intelligence across 30+ industries and 1200 markets worldwide.



