3D Semiconductor Packaging Market Overview:
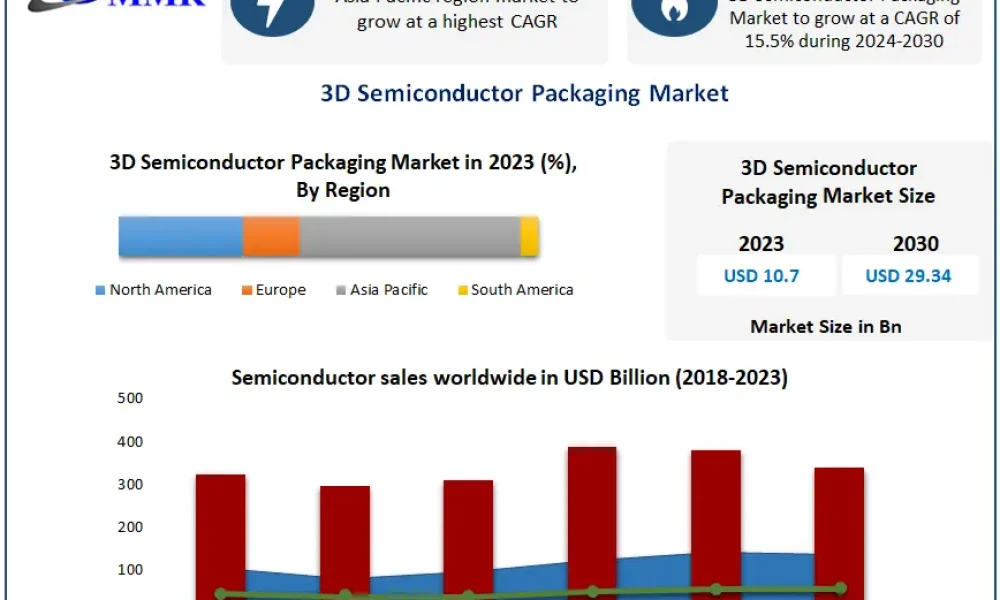
3D Semiconductor Packaging Market is accelerating rapidly, forecast to grow from USD 11.46 billion in 2025 to USD 33.68 billion by 2032 at a CAGR of 16.7%. Propelled by soaring demand for compact, high-performance electronics and the exponential expansion of applications in AI, 5G, IoT, and automotive, Asia Pacific takes the lead as the dominant region, driven by unrivaled consumer electronics demand, semiconductor production capacity, and innovation ecosystems.
Key Highlights & Insights
Market Size & Growth: The global 3D semiconductor packaging market is set to grow from USD 11.46 billion in 2025 to USD 33.68 billion by 2032 (CAGR: 16.7%).
Dominating Region: Asia Pacific leads, holding over 41% of global market share in 2024, underpinned by the region’s booming consumer electronics sector, production scale in China, Taiwan, and South Korea, and aggressive R&D in semiconductor packaging.
Leading Segment: Consumer electronics is the primary adoption segment, fueled by demand for smartphones, wearables, and compact electronics that require advanced packaging for enhanced function and reduced size.
Key Driver: The push for smaller, faster, and more energy-efficient devices in AI, cloud, automotive (especially EVs and ADAS), and HPC is a major force behind rising adoption of 3D packaging technologies such as TSV, FOWLP, and SiP.
► Get a sample of the report:https://www.maximizemarketresearch.com/request-sample/243005/
Recent Developments
2024–2025:
Samsung commenced mass production of 3nm 3D semiconductor chips, targeting crypto miners and high-performance computing.
Intel launched collaborative manufacturing with MediaTek, integrating 3D chips for smart devices based on Intel 16 technology.
A surge in automotive electronics—particularly in ADAS and EV architectures—drove a 30% YoY increase in 3D packaging adoption, now comprising 17% of segment share globally.
TSMC, ASE, Amkor, and JCET ramped up investments in organic substrate R&D to achieve better cost-performance ratios and further miniaturization.
Market Dynamics
Growth Drivers:
Explosive growth in AI, IoT, 5G, and cloud platforms demands highly integrated, reliable, and low-latency chip solutions, accelerating adoption of 3D IC and packaging.
Rising automotive applications (electric vehicles, ADAS, zonal architectures) increasingly rely on 3D packaging for compute density and thermal efficiency.
Manufacturers expand R&D in scalable, power-efficient technology to meet evolving market demands.
Shift toward environmentally sustainable packaging materials and processes, especially in leading Asian supply chains.
Challenges:
High complexity in testing, quality assurance, and integration with existing manufacturing infrastructure raises production costs and time-to-market.
Market fragmentation increases competition and interoperability concerns across technology ecosystems.
Skilled talent and high initial investment requirements can slow entry for smaller players.
Regional Analysis
Asia Pacific: Holds the largest share thanks to its massive electronics production base, advanced substrate and foundry infrastructure (especially Taiwan and South Korea), and surging demand for consumer devices and automotive semiconductors.
North America: Shows robust growth in design-led innovation and end-use in high-performance applications (cloud, HPC, AI).
Europe: Focus on automotive and industrial applications, with strong R&D and sustainable manufacturing practices.
Rest of World: Latin America, Middle East, and Africa experience
gradual expansionas digitalization accelerates and local assembly rises.
Product Segmentation
By Packaging Method: Through-Silicon Via (TSV), Package-on-Package, Fan-Out Wafer-Level Packaging (FOWLP), System-in-Package (SiP), Chip-on-Wafer (CoW), Wafer-on-Wafer (WoW).
By Material: Organic substrate (dominant in 2024), lead frame (fastest-growing), ceramic, encapsulation resin, die attach.
By Application: Consumer electronics (largest), automotive, IT & telecommunications, industrial, military & aerospace.
By Region: Asia Pacific, North America, Europe, Latin America, Middle East & Africa.
Key Trends
Advancements in vertical chip integration (TSV, FOWLP) enable higher compute density and energy efficiency.
Acceleration in automotive electronics adoption, especially in EVs and ADAS architectures.
Rise of organic substrates for lighter, low-cost, high-speed applications.
Ongoing investment in miniaturization and high-density multi-layer interconnects.
Strategic collaborations and acquisitions across supply chains to enhance process capability and meet market demand.
Quote
“Asia Pacific’s dominance in the 3D semiconductor packaging market illustrates the region’s unmatched edge in electronics manufacturing and R&D capacity. As the race for miniaturization and AI-driven devices heats up, advanced packaging stands at the heart of next-generation performance and innovation.”
About Maximize Market Research:
Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Contact Maximize Market Research:
3rd Floor, Navale IT Park, Phase 2
Pune Bangalore Highway, Narhe,
Pune, Maharashtra 411041, India
[email protected]
+91 96071 95908, +91 9607365656




