Definition
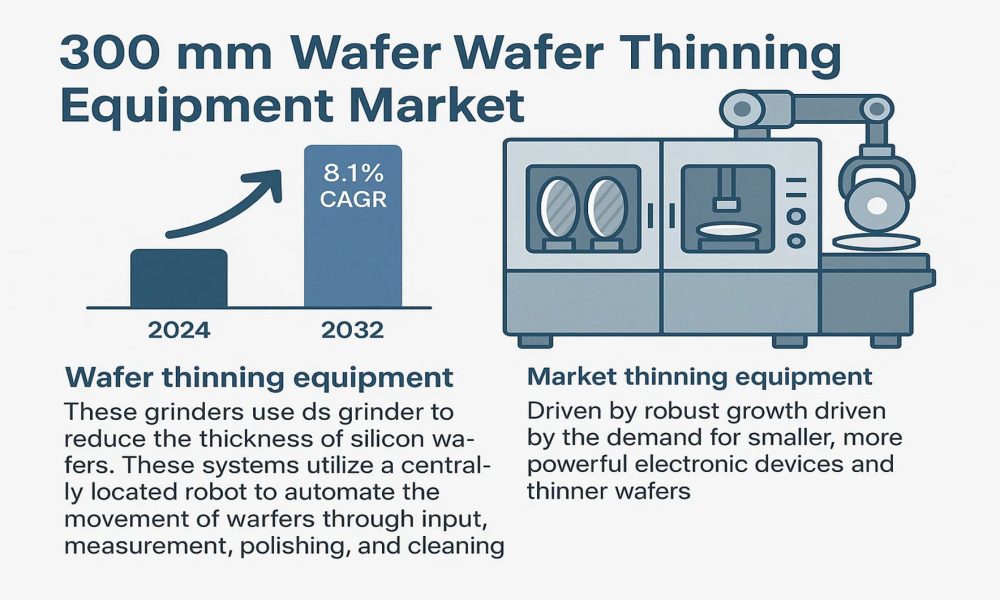
300 mm Wafer Thinning Equipment Market to precision machinery designed to reduce the thickness of silicon wafers used in semiconductor manufacturing. Also commonly referred to as wafer grinders, these systems are critical in producing thinner, more advanced semiconductor devices, which enable higher performance, miniaturization, and integration in modern electronics.
The wafer thinning process involves several interconnected operations:
- Input and loading – wafers are placed into the equipment via automated robotic handling systems.
- Measurement – precise thickness and surface measurements ensure uniformity and accuracy.
- Grinding and polishing – wafers are thinned using mechanical grinding or chemical-mechanical polishing (CMP), removing bulk material without damaging wafer integrity.
- Cleaning and drying – ensures the wafers are free of debris, contaminants, or slurry residues to maintain optimal semiconductor quality.
Download Sample Report https://semiconductorinsight.com/download-sample-report/?product_id=88228
These systems are particularly critical in the production of high-performance logic chips, memory devices, and microelectromechanical systems (MEMS), where wafer thinning improves thermal performance, mechanical reliability, and enables three-dimensional packaging in semiconductor devices.
The equipment is broadly categorized based on automation level, application type, technology, and processing stage, allowing semiconductor manufacturers to optimize production efficiency and wafer quality.
Read Full Report https://semiconductorinsight.com/report/300-mm-wafer-wafer-thinning-equipment-market/
Market Size
The 300 mm Wafer Wafer Thinning Equipment Market was valued at US$ 789 million in 2024 and is projected to reach US$ 1,371 million by 2032, growing at a CAGR of 8.1% during the forecast period.
Key Market Drivers:
- Increasing demand for advanced semiconductors – Growing requirements for AI, 5G, and IoT devices are driving the need for thinner wafers to support higher transistor density and better heat dissipation.
- Miniaturization trends – Thinner wafers enable the fabrication of smaller chips, crucial for mobile devices, wearable electronics, and high-performance computing.
- Shift towards 300 mm wafer manufacturing – Larger wafers increase output efficiency, reduce cost per chip, and improve production yields.
- Automated and high-precision equipment adoption – Fully automatic systems provide superior accuracy, reducing defects and downtime.
- Expansion of foundry operations – Outsourced semiconductor manufacturing drives demand for high-volume wafer thinning solutions.
Historical Trends:
- 2018–2023: Moderate market growth due to adoption of wafer thinning in legacy 200 mm fabs transitioning to 300 mm wafers.
- 2024–2032: Accelerated growth expected due to scaling of semiconductor nodes, high-volume foundry expansion, and advanced packaging requirements.
Key Statistics:
- Fully automatic equipment dominates market adoption due to precision and high throughput capabilities.
- Foundries account for the largest application segment, as high-volume production benefits from automated thinning processes.
- Grinding technology remains the primary method, favored for bulk material removal efficiency.
- Dual-side grinding equipment is gaining popularity for improved wafer strength and device performance.
Regional Analysis
The market demonstrates distinct regional trends driven by semiconductor manufacturing concentration and technological capabilities:
Asia-Pacific (APAC)
- Dominates the global market, with Japan, Taiwan, and South Korea as leading manufacturing hubs.
- Companies like Disco Corporation, TOKYO SEIMITSU, and Okamoto drive adoption of automated wafer thinning equipment.
- Strong foundry growth in Taiwan and South Korea contributes significantly to equipment demand.
North America
- Growth fueled by high-tech semiconductor manufacturing facilities and innovation in wafer thinning technology.
- U.S. manufacturers and fabs prioritize high-precision equipment to support advanced node production.
Europe
- Moderate market expansion with emphasis on high-quality, precision manufacturing and R&D-driven equipment innovations.
- Germany-based G&N Genauigkeitstechnik Nürnberg GmbH provides specialized solutions for European semiconductor fabs.
China and Emerging Markets
- Rapid expansion in CETC (China Electronics Technology Group Corporation)-supported semiconductor fabs.
- Taiwan and Korea continue to adopt TSD and NTS systems to meet growing domestic semiconductor demand.
Overall, APAC leads in volume and adoption rate, followed by North America and Europe, with emerging regions in China and Southeast Asia showing high growth potential.
Competitor Analysis
The 300 mm wafer wafer thinning equipment market is highly specialized and dominated by a few key global players:
- Disco Corporation (Japan) – Market leader with a focus on fully automated, high-precision grinding and polishing systems.
- TOKYO SEIMITSU (Japan) – Offers integrated solutions for dual-side grinding and polishing.
- G&N Genauigkeitstechnik Nürnberg GmbH (Germany) – Provides precision equipment for European semiconductor fabs.
- Okamoto Semiconductor Equipment Division (Japan) – Specializes in CMP and grinding solutions for high-performance wafers.
- CETC (China) – Expanding domestic market footprint with cost-effective automated equipment.
- Koyo Machinery (Japan), SpeedFam (Japan), TSD (Taiwan), NTS (Korea) – Serve regional fabs with semi-automatic and fully automatic solutions.
Competitive Strategies:
- Focus on automation and robotics integration to improve throughput.
- Continuous R&D in grinding and CMP technologies for thinner and more robust wafers.
- Expanding after-sales service and technical support networks to maintain equipment reliability.
- Strategic partnerships with foundries and IDM companies to embed advanced wafer thinning equipment into production lines.
Global 300 mm Wafer Wafer Thinning Equipment Market: Market Segmentation Analysis
This report provides a deep insight into the global 300 mm Wafer Wafer Thinning Equipment Market, covering all its essential aspects. This ranges from a macro overview of the market to micro details of the market size, competitive landscape, development trend, niche market, key market drivers and challenges, SWOT analysis, value chain analysis, etc.
The analysis helps the reader to shape the competition within the industries and strategies for the competitive environment to enhance the potential profit. Furthermore, it provides a simple framework for evaluating and assessing the position of the business organization. The report structure also focuses on the competitive landscape of the Global 300 mm Wafer Wafer Thinning Equipment Market. This report introduces in detail the market share, market performance, product situation, operation situation, etc., of the main players, which helps the readers in the industry to identify the main competitors and deeply understand the competition pattern of the market.
In a word, this report is a must-read for industry players, investors, researchers, consultants, business strategists, and all those who have any kind of stake or are planning to foray into the 300 mm Wafer Wafer Thinning Equipment Market in any manner.
Market Segmentation (by Application)
Foundry Segment Leads Due to High-Volume Outsourced Semiconductor Manufacturing
The market is segmented based on application into:
- IDM (Integrated Device Manufacturer)
- Foundry
Market Segmentation (by Type)
Fully Automatic Segment Dominates the Market Due to Superior Precision and High-Volume Production Capabilities
The market is segmented based on type into:
- Fully Automatic
- Semi Automatic
Download Sample Report https://semiconductorinsight.com/download-sample-report/?product_id=88228
Key Company
- Disco Corporation (Japan)
- TOKYO SEIMITSU (Japan)
- G&N Genauigkeitstechnik Nürnberg GmbH (Germany)
- Okamoto Semiconductor Equipment Division (Japan)
- CETC (China)
- Koyo Machinery (Japan)
- SpeedFam (Japan)
- TSD (Taiwan)
- NTS (Korea)
Geographic Segmentation
- Asia-Pacific – Largest market; Japan, Taiwan, and South Korea are major adoption hubs.
- North America – Focused on high-precision fabs and advanced semiconductor technology.
- Europe – Moderate growth; Germany leads in precision equipment adoption.
- China and Emerging Markets – Rapid expansion driven by domestic semiconductor industry growth.
Download Sample Report https://semiconductorinsight.com/download-sample-report/?product_id=88228
FAQ
Q1. What is the current market size of the 300 mm Wafer Wafer Thinning Equipment Market?
The market was valued at US$ 789 million in 2024 and is projected to reach US$ 1,371 million by 2032.
Q2. Which are the key companies operating in the 300 mm Wafer Wafer Thinning Equipment Market?
Key players include Disco Corporation, TOKYO SEIMITSU, G&N Genauigkeitstechnik Nürnberg GmbH, Okamoto, CETC, Koyo Machinery, SpeedFam, TSD, and NTS.
Q3. What are the key growth drivers in the 300 mm Wafer Wafer Thinning Equipment Market?
- Increasing adoption of 300 mm wafer fabs
- Demand for advanced and miniaturized semiconductors
- Expansion of foundries and outsourced semiconductor manufacturing
- Advances in fully automatic wafer thinning systems
Q4. Which regions dominate the 300 mm Wafer Wafer Thinning Equipment Market?
Asia-Pacific leads the market, followed by North America and Europe, with emerging regions in China and Southeast Asia growing rapidly.
Q5. What are the emerging trends in the 300 mm Wafer Wafer Thinning Equipment Market?
- Increased adoption of dual-side grinding equipment
- Integration of automated robotics and measurement systems




